Cash App Clone: Features, Cost & Business Model
Explore cashapp clone features, development costs, revenue models, security requirements, and the steps to launch a digital payment application.
 Taylor Morgan
Digital payments have changed how people send money, manage everyday expenses, and make online transactions. Customers increasingly expect payment applications to offer quick transfers, simple account management, secure transactions, and convenient mobile access. This growing demand has created opportunities for entrepreneurs who want to enter the digital payment industry with their own financial technology products.
A cashapp clone is one approach to building a peer-to-peer payment application inspired by the core functionality of popular payment platforms. Instead of developing every feature from scratch, businesses can use a ready-made or customizable application framework and adapt it to their target market, business requirements, and branding.
However, launching a successful payment application requires more than an attractive interface. Entrepreneurs must consider security, payment processing, regulatory requirements, customer experience, and long-term revenue generation. Understanding these elements can help businesses make informed decisions before investing in development.
What Is a Cash App Clone?
A Cash App clone is a payment application designed to support digital transactions and related financial services. Depending on the product's scope, it may allow users to register accounts, send and receive money, view transaction histories, manage payment methods, and receive transaction notifications.
The goal is to build an application that addresses similar customer needs while offering its own features, branding, and business strategy. Businesses should develop an original product rather than copy another company's protected branding, proprietary design, or intellectual property.
Startups can customize the application for specific audiences, such as freelancers, small businesses, online sellers, or communities that need convenient digital payment solutions.
Essential Features of a Cash App Clone
Choosing the right features is an important part of developing a reliable payment application. The initial version should focus on the functions customers need most, with advanced services introduced as the business grows.
1. User Registration and Identity Verification
The registration process should be simple while meeting applicable identity verification requirements. Depending on the market and services offered, users may need to provide personal information and complete identity checks before accessing certain payment features.
Secure authentication, account recovery, and appropriate verification procedures help protect customer accounts.
2. Digital Wallet Management
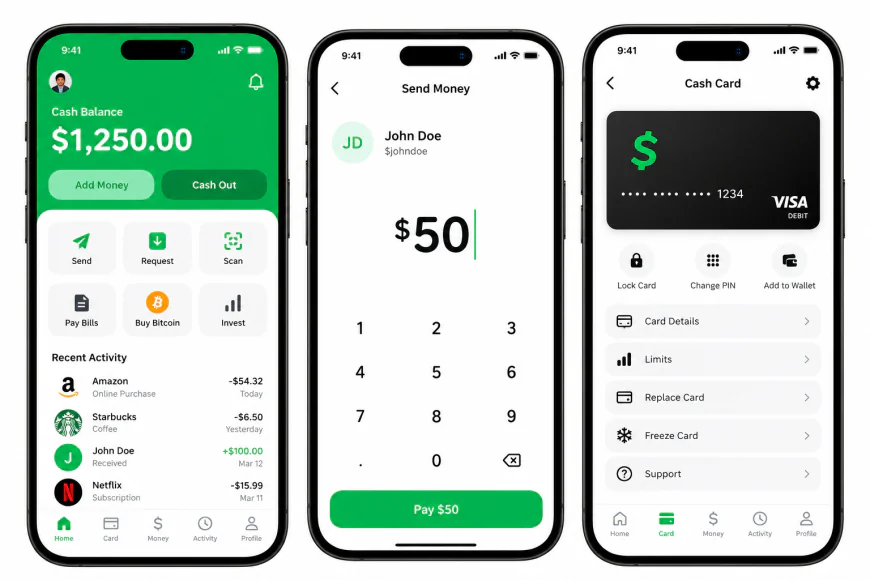
A digital wallet allows users to view their available balance, review transactions, and manage supported payment methods. The application should display transaction details clearly and provide useful information about completed, pending, or failed payments.
Wallet functionality must be supported by an appropriate financial and payment infrastructure. Displaying a balance in an app does not, by itself, establish a compliant system for holding customer funds.
3. Peer-to-Peer Money Transfers
Sending and receiving money is a central feature of this type of application. Users should be able to select a recipient, enter an amount, review the transaction, and receive confirmation.
Clear payment statuses and transaction references help users understand what happened to their money. The system should also include suitable controls to reduce duplicate transfers, unauthorized transactions, and payment errors.
4. Bank Account and Payment Gateway Integration
Payment integrations connect the application with supported financial institutions, payment processors, or other authorized service providers. They enable the application to process transactions through the available payment methods.
Integration requirements depend on the target country, currencies, payment rails, and intended financial services. Businesses should evaluate provider fees, settlement times, technical documentation, and compliance responsibilities before selecting an integration partner.
5. Transaction History and Notifications
Users need an accessible record of their financial activity. A transaction history should include relevant information such as the amount, date, recipient, status, and transaction reference.
Push notifications or other alerts can inform users about transfers, payment confirmations, account changes, and potentially suspicious activity. Notification preferences should be configurable where appropriate.
6. Security and Fraud Prevention
Security should be considered from the beginning of development rather than added after launch. Depending on the product, useful measures include multifactor authentication, encryption, secure session management, risk-based transaction checks, rate limiting, and suspicious-activity monitoring.
Businesses should also plan for incident response, data protection, account recovery, and security testing. The appropriate controls depend on the application's architecture, payment partners, regulatory obligations, and risk profile.
7. Admin Dashboard
An administrative dashboard helps authorized staff monitor platform activity and manage operational tasks. It may include user management, transaction monitoring, support requests, verification statuses, and reporting.
Access should be restricted according to staff responsibilities, with audit logs for sensitive actions. Administrators should not have unrestricted access to customer financial information without a legitimate operational reason.
How Much Does a Cash App Clone Cost?
The development cost depends on the application's complexity, required integrations, security architecture, compliance needs, and development approach. There is no single price that applies to every payment application.
For initial budgeting, businesses can use the following illustrative estimates. These are planning ranges rather than verified vendor quotations.
-
Basic MVP: $5,000–$12,000. A limited application with essential user flows, basic transaction functionality, and a relatively small feature set.
-
Mid-level application: $12,000–$20,000. A more developed product with additional integrations, stronger administrative tools, reporting, and expanded security controls.
-
Advanced payment platform: $20,000–$28,000 or more. A complex solution with broader payment capabilities, advanced risk monitoring, multiple integrations, and more extensive operational infrastructure.
Actual costs may fall outside these ranges. Licensing, payment processing, legal advice, identity verification, audits, cloud infrastructure, customer support, and ongoing maintenance may require separate budgets.
Factors That Affect Development Costs
Feature requirements: A basic transfer application generally requires less work than a platform with multiple payment methods, business accounts, advanced analytics, and additional financial services.
Third-party integrations: Payment processors, banking partners, identity verification providers, and fraud prevention services may charge setup fees or recurring usage fees.
Platform selection: Building for one mobile platform may have different costs from developing native applications for iOS and Android alongside a web-based administration panel.
Security and compliance: Financial applications need careful planning around applicable laws, data protection, transaction monitoring, and operational risk. Requirements vary by jurisdiction and business model.
Maintenance and scalability: Updates, infrastructure monitoring, customer support, security patches, and performance improvements contribute to the total cost of ownership.
Business Models for a Cash App Clone
A payment application needs a sustainable revenue model that aligns with its users' needs and the costs of operating the platform. Several approaches are worth evaluating.
1. Transaction Fees
The business may charge fees for selected transactions, such as certain instant transfers or specialized payment services. Fees should be transparent and competitive, and the company must account for payment processing costs before estimating profit.
2. Business Payment Services
Small businesses and independent professionals may pay for additional payment tools, transaction reports, reconciliation features, or business account capabilities. This model can create recurring revenue when the services provide clear value.
3. Subscription Plans
A platform can offer paid plans with additional features, higher usage limits, or specialized business tools. Subscription pricing should be based on genuine customer demand rather than placing essential payment information behind unnecessary restrictions.
4. Premium Transfers and Convenience Features
Some users may be willing to pay for optional convenience features, provided the pricing and delivery times are clearly explained. Whether such services are available depends on payment partners and applicable regulations.
5. Merchant and Platform Partnerships
Businesses may explore partnerships with merchants, software platforms, or authorized financial service providers. Revenue-sharing arrangements can support growth, but agreements should define responsibilities, customer protections, and payment terms.
The best model will depend on transaction volume, operating expenses, the target market, and the value delivered to customers. Revenue projections should account for fraud losses, refunds, customer acquisition, support, and compliance costs.
Steps to Launch a Cash App Clone
Launching a payment application requires a structured development and business process.
Step 1: Research the target market. Identify the customers you want to serve, their payment habits, existing alternatives, and the problems your application will solve.
Step 2: Define the product scope. Decide which payment methods, account features, currencies, and transaction types are necessary for the first release.
Step 3: Assess regulatory requirements. Determine which licensing, registration, identity verification, anti-money-laundering, privacy, and consumer protection requirements apply in your intended markets. Work with qualified legal and compliance professionals.
Step 4: Choose a development approach. Compare custom development with a ready-made solution. Review source code access, customization options, integration capabilities, security practices, documentation, and ongoing support.
Step 5: Integrate payment infrastructure. Select suitable payment processors and financial partners. Confirm their eligibility requirements, supported services, settlement processes, and commercial terms.
Step 6: Test the application thoroughly. Test transaction flows, failed payments, account recovery, security controls, performance, and edge cases before accepting real customer transactions.
Step 7: Launch and improve. Start with a controlled release, monitor customer feedback and transaction performance, and prioritize improvements based on actual usage.
Why Choose a Customizable Payment Application Solution?
Developing a financial application entirely from the ground up can require significant time, technical resources, and project management. A customizable solution may provide a practical starting point for businesses that want to establish their product identity without building every component independently.
A suitable solution can help teams focus on branding, customer experience, market positioning, and the integrations required for their business model. However, ready-made software does not automatically provide payment authorization, regulatory approval, banking partnerships, or guaranteed security. These areas must be evaluated separately.
CloneAppz provides white-label and clone application development services for businesses exploring customizable digital products. Before selecting any provider, entrepreneurs should review the proposed architecture, source code ownership, delivery scope, security documentation, integration responsibilities, and post-launch support.
Challenges to Consider Before Launch
Payment applications operate in a trust-sensitive market. Customers expect transactions to work reliably and their financial information to remain protected.
Businesses should prepare for fraud attempts, account takeovers, transaction disputes, payment failures, and customer support requests. They must also consider the availability of payment partners and the regulatory requirements of every market they enter.
Another challenge is customer acquisition. Competing with established payment platforms can be difficult, so a new application should offer a clear reason to switch or adopt an additional service. Serving a focused audience or addressing an underserved payment need may provide a more realistic starting point than attempting to serve everyone immediately.
Conclusion
A cashapp clone can provide a foundation for entrepreneurs who want to enter the digital payments market with a branded payment application. Its long-term potential depends on selecting the right features, choosing reliable payment partners, maintaining strong security, and developing a realistic business model.
Before investing, businesses should define their target audience, estimate development and operating costs, assess regulatory obligations, and validate customer demand. A focused minimum viable product can help test the concept before expanding into more complex financial services.
With careful planning and an appropriate development strategy, businesses can build a payment platform designed around their customers' needs while creating a foundation for future growth.
Frequently Asked Questions
1. What is a cashapp clone?
A cashapp clone is a customizable payment application inspired by the core functionality of peer-to-peer payment platforms. It can include money transfers, transaction history, notifications, and supported payment integrations.
2. How much does it cost to develop a Cash App clone?
An initial planning budget might range from $5,000 to $12,000 for a basic MVP, while more complex solutions may cost $12,000 to $25,000 or more. Actual costs depend on the feature scope, integrations, security, and regulatory requirements.
3. How long does development take?
A basic MVP may take a few months, while a more complex financial application may require six months or longer. Integration approvals, testing, and compliance work can affect the timeline.
4. Can a Cash App clone integrate with banks?
Yes, where appropriate banking or payment integrations are available. The specific capabilities depend on the chosen provider, market, technical requirements, and applicable authorization rules.
5. How can a payment application generate revenue?
Possible revenue sources include selected transaction fees, subscriptions, business payment services, premium convenience features, and partnerships. Each model should be evaluated against operating costs and customer expectations.
6. Is a ready-made payment application suitable for startups?
It can be suitable for startups seeking a faster development starting point. However, businesses should verify customization options, code ownership, integration support, security standards, and compliance responsibilities before committing.
7. What should businesses prioritize before launching?
They should prioritize market validation, secure transaction processing, regulatory assessment, reliable integrations, transparent pricing, customer support, and thorough testing.