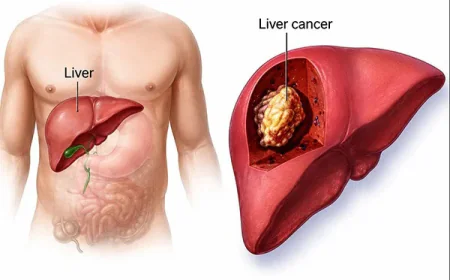
Companion Diagnostics Drive Demand in the Anatomic Pathology Market
Market Segmentation The anatomic pathology market is segmented by product and service, technology, application, and end use.
 Eknath Girhepunje
The global anatomic pathology market plays an essential role in disease detection and clinical decision-making through the examination of tissues, cells, and organs. Technologies such as histopathology, cytopathology, immunohistochemistry, molecular pathology, and digital pathology support accurate disease identification and characterization. Demand for tissue-based diagnostics, companion diagnostic testing, personalized medicine, and AI-assisted pathology solutions is supporting the adoption of advanced instruments, consumables, and laboratory services.
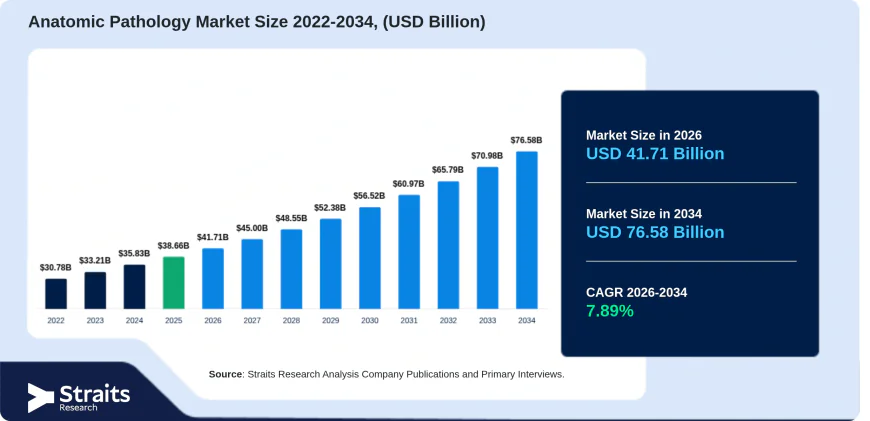
The global anatomic pathology market size was valued at USD 38.66 billion in 2025 and is projected to grow from USD 41.71 billion in 2026 to USD 76.58 billion by 2034, registering a CAGR of 7.89% during the forecast period from 2026 to 2034. North America dominated the market with a 39.12% share in 2025.
For detailed market insights, growth forecasts, and competitive analysis, visit: https://straitsresearch.com/report/anatomic-pathology-market
Market Drivers
Companion Diagnostic Testing Drives Market
The use of companion diagnostics in oncology is supporting demand for anatomic pathology procedures that identify treatment-specific biomarkers from tissue samples. Laboratories are strengthening immunohistochemistry, in situ hybridization, and tissue-based molecular testing capabilities to support targeted therapies. These procedures help healthcare professionals evaluate tumor characteristics and select appropriate treatment options. The need for biomarker assessment is supporting investment in advanced pathology instruments, reagents, and diagnostic services.
Digital Biobank Integration Supports Pathology Market Growth
Digital biobank-integrated pathology networks are connecting archived tissue repositories with clinical diagnostics and translational research. These networks enable healthcare institutions and research organizations to access tissue information for disease analysis, biomarker studies, and clinical investigations. Their implementation requires reliable pathology imaging, digital storage, and analytical infrastructure. Greater integration of tissue repositories with diagnostic workflows is supporting demand for digital pathology platforms and related laboratory technologies.
Personalized Medicine and Advanced Tissue Analysis Drive Market
Personalized medicine relies on detailed tissue examination and biomarker identification to support treatment decisions. Techniques such as immunohistochemistry, molecular pathology, and spatial tissue profiling provide information about disease characteristics and cellular interactions. These methods are particularly relevant to oncology, where tissue-based testing helps classify tumors and evaluate treatment suitability. Their use is encouraging laboratories to adopt specialized instruments, advanced reagents, and integrated diagnostic workflows.
Market Challenges
Complexity of Multiplex Assays Limits Market Adoption
Multiplex immunofluorescence and spatial biology techniques require specialized instruments, advanced imaging systems, complex reagent panels, and trained personnel. Differences in laboratory procedures and the absence of standardized workflows can complicate implementation across healthcare institutions. These requirements may increase operational costs and make advanced tissue profiling difficult for laboratories with limited technical resources.
Limited Availability of Annotated Pathology Datasets
Digital and computational pathology solutions depend on large collections of accurately annotated tissue images. Preparing expert-validated datasets requires substantial pathologist involvement and considerable time. Differences in staining protocols, specimen characteristics, and disease representation across institutions can also affect data consistency. These limitations create difficulties for developing and validating AI-based pathology applications.
Variability in Tissue Staining and Shortage of Specialist Pathologists
Differences in tissue preparation, staining procedures, reagent performance, and scanner calibration can affect the consistency of pathology images. Such variability may influence diagnostic interpretation and computational analysis, particularly across laboratories operating at multiple locations. A shortage of specialists in areas such as hematopathology, neuropathology, and molecular oncology also creates pressure on diagnostic services. Limited access to subspecialty expertise can contribute to consultation delays and longer case turnaround times.
Market Segmentation
The anatomic pathology market is segmented by product and service, technology, application, and end use. By product and service, the market includes instruments, consumables, and services. Consumables accounted for a 47.36% share in 2025 because tissue examination requires reagents, paraffin wax, antibodies, stains, slides, and coverslips. The instruments segment is projected to register a CAGR of 8.47% during the forecast period, supported by the deployment of automated tissue processors, slide scanners, and robotic staining platforms. By technology, the market includes histopathology, cytopathology, immunohistochemistry, in situ hybridization, digital pathology, molecular pathology, AI-enabled pathology, and others. Histopathology held a 29.85% share in 2025, while AI-enabled pathology is projected to grow at a CAGR of 10.3% during the forecast period, driven by automated image analysis and biomarker quantification. By application, disease diagnosis accounted for a 76.19% share in 2025, reflecting the importance of tissue examination in cancer and other disease identification. Drug discovery and development is projected to register a CAGR of 8.73% during the forecast period, supported by tissue profiling and biomarker assessment in pharmaceutical research. By end use, the market includes hospitals, diagnostic laboratories, research laboratories, and others. Hospitals accounted for a 38.52% share in 2025, supported by their requirement for biopsy examination, surgical pathology, and intraoperative consultations. Diagnostic laboratories also represent an important end-use category due to specialized testing capabilities and centralized pathology services.
Regional Insights
North America dominated the anatomic pathology market with a 39.12% share in 2025. The region benefits from established diagnostic infrastructure, extensive use of companion diagnostic testing, and adoption of digital pathology technologies. In the U.S., biomarker-guided cancer treatment pathways and computational pathology applications are supporting demand for advanced tissue diagnostics. In Canada, province-wide digital pathology networks and telepathology services are supporting access to specialist expertise across geographically dispersed populations.
Asia Pacific is projected to be the fastest-growing region, registering a CAGR of 9.66% during the forecast period. Cancer screening programs, higher biopsy volumes, and modernization of pathology laboratories are supporting market development. China is deploying digital hospital infrastructure and pathology image management systems, while India is adopting centralized diagnostic networks and telepathology services. Japan's use of immunohistochemistry and companion diagnostic testing is supporting demand for advanced tissue examination and biomarker-based diagnosis.
Europe represents an important market for anatomic pathology, supported by established healthcare systems, diagnostic laboratory infrastructure, and the adoption of advanced tissue analysis technologies. Demand for histopathology, immunohistochemistry, and molecular diagnostic procedures supports the use of specialized laboratory instruments and consumables across the region.
Key Players Analysis
The anatomic pathology market includes diagnostic technology manufacturers, laboratory solution providers, and companies specializing in tissue analysis and pathology equipment. Major players focus on product development, laboratory automation, diagnostic accuracy, and digital pathology integration. The leading companies include:
- Leica Biosystems
- Roche Tissue Diagnostics
- Sakura Finetek Japan
- PHC Holdings Corporation
- Epredia
Conclusion
The anatomic pathology market is projected to maintain steady growth through 2034 as healthcare providers and research organizations rely on tissue-based diagnosis, biomarker testing, and advanced pathology technologies. North America holds the leading market position, while Asia Pacific is expected to record the fastest growth. Consumables and disease diagnosis currently account for major market shares, whereas AI-enabled pathology and diagnostic laboratory services support technology and service development. Continued adoption of digital pathology, personalized medicine, and specialized tissue analysis will influence the industry's future.
About Us
Straits Research provides market intelligence, industry analysis, market forecasts, and competitive assessments across global industries. Its research helps organizations understand market dynamics, identify opportunities, and make informed strategic decisions.
Contact Us
Website: https://straitsresearch.com
Email: [email protected]
U.S.: +1 646 905 0080
India: +91 8087085354
U.K.: +44 203 695 0070