Spain Paper Packaging Market Size, Share, Trends and Outlook Report 2034
The Spain paper packaging market size was valued at USD 7.18 Billion in 2025 and is projected to reach USD 8.75 Billion by 2034, growing at a compound annual growth rate of 2.22% from 2026-2034.
 Yadwender Kumar
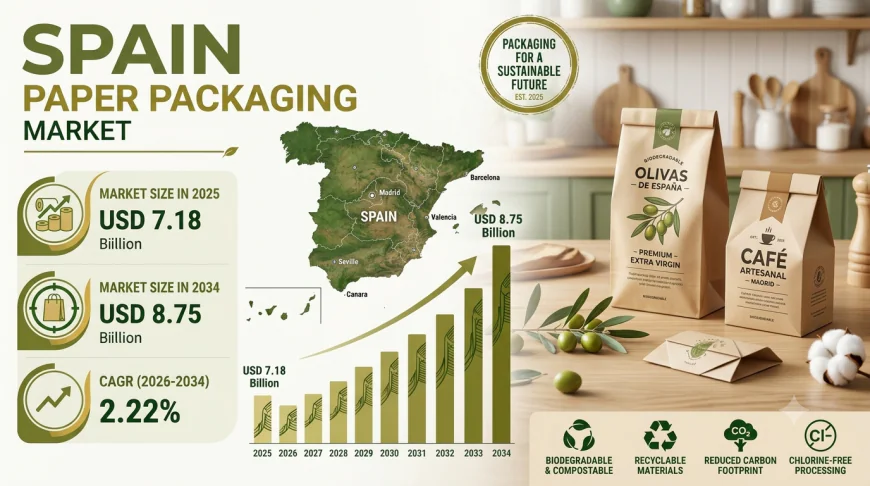
Spain’s packaging industry is in the middle of a decisive material transition. For decades, plastics defined how food, beverages and household goods reached the shelf. Today, regulation, retailer commitments and consumer expectations are pulling the sector firmly towards fibre-based solutions that are recyclable, reusable or compostable. Corrugated boxes are being right-sized for online orders, paperboard trays are replacing plastic ones in chilled aisles, and paper-based pouches are arriving in categories once thought out of reach. The Spain Paper Packaging Market is at the centre of this shift. Valued at USD 7.18 billion in 2025, the market is projected to reach USD 8.75 billion by 2034, growing at a compound annual growth rate of 2.22 per cent from 2026 to 2034. These figures describe a mature, resilient industry that is steadily reinventing itself around sustainability.
What’s Driving Growth of Spain’s Paper Packaging Market?
Packaging regulation is turning sustainability into a baseline requirement. A Royal Decree announced in July 2025 requires packaging placed on the Spanish market to be recyclable, reusable or compostable, supported by eco-design and labelling rules. Because paper and paperboard already fit comfortably within this framework, converters and brand owners are accelerating their move to fibre-based formats. Compliance is no longer a differentiator; it is the entry ticket, and paper is the most established route to meet it.
A growing food and beverage sector is anchoring everyday demand. Packaged foods, bakery products, dairy and ready meals continue to expand, and the food segment alone accounts for 45 per cent of paper packaging demand. Investment is following: in October 2025, Stolt Sea Farm announced a food processing and R&D centre in Rianxo, Galicia, expected to employ more than 100 people. Spain’s foodservice sector, valued at USD 154.4 billion in 2024, adds a further layer of demand for cups, trays, bags and takeaway packaging.
Spain’s e-commerce boom is multiplying the need for protective paper formats. With the country’s e-commerce market valued at USD 431.3 billion in 2024, every parcel represents a packaging opportunity. Corrugated boxes, the largest product category with a 40 per cent share, are being redesigned for right-sized, damage-resistant shipping. Retail platforms are playing their part too: in May 2025, Amazon announced custom-fit cardboard and paper packaging across Europe, including Spain, supported by automated machines in its fulfilment centres.
A strong recycling and manufacturing base gives Spain a structural advantage. Spain is Europe’s third-largest producer of corrugated cardboard, with output of €6.97 billion and more than 25,000 employees, and the corrugated segment achieves a recycling rate of 90 per cent. Improved sorting, fibre recovery and municipal collection programmes are strengthening the supply of recycled paper, which supports a genuinely circular model and gives domestic converters a dependable raw-material loop.
Three Trends Reshaping the Industry
Paper is steadily replacing plastic in trays, pouches and flexible formats.
Brand owners are moving beyond boxes and bags into categories that were previously dominated by plastic. In February 2025, Mondi and Proquimia launched paper-based stand-up pouches for dishwashing tabs in Spain and Portugal, made up of 85 per cent paper. In December 2024, Graphic Packaging International and Elaborados Naturales introduced the PaperSeal Shape paperboard tray for refrigerated potato products. In November 2024, All4Labels launched STARPACK, a paper alternative that reduces plastic use by 80 per cent and went on to win the Liderpack Award. In November 2025, Lecta’s EraCup Natural board received flustix certification as at least 99.25 per cent plastic-free.
Why it matters: Material substitution is opening entirely new addressable categories for paper, well beyond traditional cartons and sacks.
Business implication: Converters that invest in barrier coatings, heat-sealable paper and tray-forming technology can capture share from plastic incumbents.
Future impact: As certified plastic-free solutions multiply, fibre-based packaging will become the default option for chilled, dry and household products.
E-commerce-ready corrugated is becoming a design discipline of its own.
Spanish online retail is pushing corrugated manufacturers to think beyond standard shipping cartons. Right-sized boxes reduce damage, void fill and shipping costs, while automated packaging lines are now being installed directly inside fulfilment centres. Consolidation is reinforcing the trend: in May 2025, Nefab Group acquired Embalajes Echeberria, expanding its footprint in Spain’s packaging landscape. With corrugated boxes already holding a 40 per cent share of the market, innovation in this format has an outsized effect on the industry as a whole.
Why it matters: Parcel volumes and retailer sustainability targets are rewarding packaging that is lighter, stronger and tailored to the product.
Business implication: Suppliers that offer custom-fit formats, automation-friendly designs and integrated service models will become preferred partners for large retailers and marketplaces.
Future impact: Data-driven sizing and automated packaging will shift value towards converters with engineering and digital capabilities.
Lightweight, high-strength grades and digital printing are raising the value of paper.
Advances in paper science are allowing lighter materials to deliver the strength and print quality that premium brands demand. Solid bleached grades already account for 35 per cent of the market, reflecting the importance of clean, high-quality surfaces for food, beverage and personal care applications. Digital printing is enabling short runs, personalised campaigns and sharper branding without the cost of traditional plates, helping paper compete on shelf appeal as well as sustainability. Primary packaging, which commands a 50 per cent share, is where these innovations are most visible to consumers.
Why it matters: Paper is no longer just the sustainable choice; it is increasingly the premium, brand-enhancing choice.
Business implication: Investment in high-quality grades and digital print capability allows converters to move up the value chain and win higher-margin work.
Future impact: Customisation and shorter product cycles will make flexible, digitally printed paper packaging a growth engine for brands of every size.
What the Market Numbers Actually Tell Us
A market advancing from USD 7.18 billion in 2025 to USD 8.75 billion by 2034 adds roughly USD 1.57 billion in annual value over nine years, equivalent to an overall increase of around 22 per cent. The 2.22 per cent compound annual growth rate points to steady, dependable expansion rather than a speculative surge, which is precisely what long-horizon investors and capital-intensive manufacturers look for. The composition of demand reinforces that stability: food accounts for 45 per cent of end-use consumption, primary packaging for 50 per cent, solid bleached grades for 35 per cent and corrugated boxes for 40 per cent. Revenue is therefore anchored in everyday consumption categories that continue to grow, while sustainability regulation and e-commerce volumes provide additional, structural tailwinds. In a market of this maturity, the winners will be those who grow value per tonne through innovation, not just volume.
Where New Opportunities Are Emerging
The most compelling opportunities lie where regional strengths meet the shift to fibre-based materials. Eastern Spain, including Catalonia and Valencia, is a manufacturing, logistics and export hub with strong e-commerce activity and premium food demand. Northern Spain, with the Basque Country and Galicia, offers steady demand from food processing, dairy and fisheries. Southern Spain’s agriculture, horticulture, beverages and tourism-linked foodservice create consistent need for trays, cartons and takeaway formats, while Central Spain, led by Madrid’s commercial and retail base, is a natural home for sustainable paper packaging across FMCG and convenience food. Beyond geography, openings are emerging in liquid paperboard cartons for beverages, paper bags and sacks supported by initiatives such as Paper Sacks Go Circular Spain, which Mondi joined in October 2024, and plastic-free paperboard for cups and trays. For companies that can combine recycled-fibre sourcing, strong design capability and regulatory expertise, the pathway to sustained growth in Spain Paper Packaging Market is increasingly clear.