Business Protection That Goes Beyond Vehicle Coverage
Routeway360 provides specialized insurance and business solutions
 Routeway 360
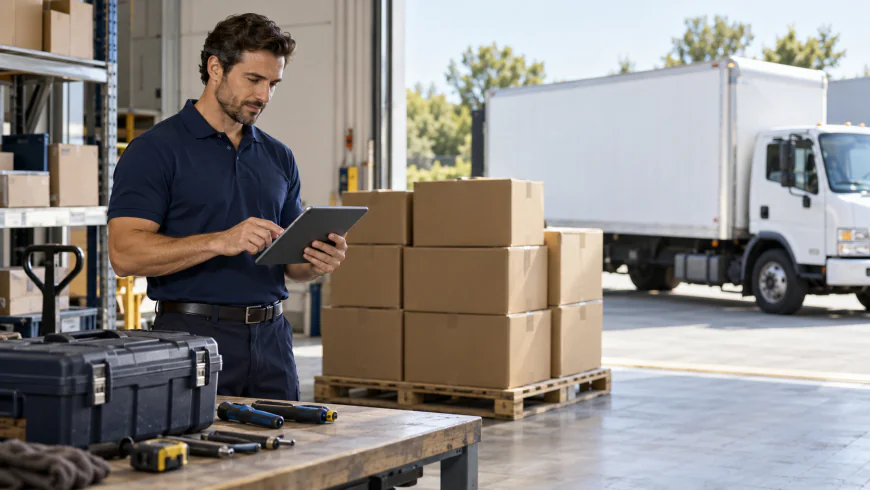
A dependable vehicle keeps your business moving, but it is only one part of the operation you need to protect. Independent distributors, contractors, route owners, and mobile businesses also depend on products, tools, customer relationships, and reliable financial processes. When something goes wrong in any of these areas, the consequences can extend beyond a damaged truck or missed delivery. A stolen shipment may interrupt sales. Damaged equipment can delay a project. A customer claim may create expenses that affect your ability to invest in the business. Looking beyond vehicle coverage means considering how these responsibilities connect and where separate protection may be needed. Commercial auto insurance is an important starting point, but owners should also review cargo, liability, equipment, and exposures associated with their particular services. Alongside insurance, organized banking, payroll, accounting, and route support can help keep everyday responsibilities manageable. Through routeway360, business owners can explore specialized coverage and business solutions based on how their operations work. This broader approach encourages informed decisions rather than assumptions about what a vehicle policy includes. Understanding your business as a whole helps you identify potential gaps, ask better questions, and create a practical foundation for dependable service and future growth over time.
Why Vehicle Insurance Is Only the Starting Point
Vehicle insurance addresses specific risks connected with the vehicles used in your business, but that does not mean every related loss falls under the same policy. The goods inside a truck, tools carried between projects, and activities performed at customer locations can involve different exposures. Assuming that everything is protected because the vehicle is insured may leave important questions unanswered. For example, a delivery business should ask how transported products are covered, while a contractor should clarify protection for equipment removed from a vehicle at a job site. Owners also need to understand how their business activities are described in policy documents. Delivery work, mobile services, and specialty operations should be communicated accurately during coverage discussions. Reviewing limits, deductibles, exclusions, and conditions helps you compare options more meaningfully. Customer agreements can add further requirements that deserve attention before work begins. A broader review does not automatically mean buying every available policy. It means identifying the risks that matter to your operation and discussing appropriate options with a qualified insurance professional who understands your business activities and the responsibilities they involve.
Protecting the Goods You Carry
For distributors and route owners, the value of a delivery often sits inside the vehicle rather than in the vehicle itself. Products may be damaged, stolen, or lost while being transported, creating costs and disrupting commitments to customers. Cargo coverage deserves its own discussion because vehicle protection does not automatically explain how transported goods are insured. Start by describing the products you carry, their ownership, their maximum value per load, and any special handling requirements. Consider whether shipments involve multiple stops, overnight parking, or temporary storage. Ask how those circumstances are treated under the proposed coverage. Keep shipment records, delivery confirmations, and information about product values organized so you can explain your operation accurately. Understanding applicable limits and conditions helps you evaluate whether an option suits your delivery responsibilities. Careful loading, secure storage, and consistent handling procedures also support a stronger approach to protecting goods throughout their journey to customers.
Safeguarding Tools and Mobile Equipment
Tools and equipment allow contractors and mobile service businesses to complete work efficiently. When essential items are stolen or damaged, the effect may include replacement expenses, postponed appointments, and lost working time. Protection should therefore account for how equipment is used and where it travels. A tool kept at a business location may raise different questions from equipment transported between customer sites every day. Explain whether items are owned, rented, or borrowed, and ask how each category is handled. Include storage arrangements, overnight vehicle use, and the replacement value of major assets in your discussion. Maintain an inventory with purchase details, serial numbers, and photographs where practical. These records help you review protection as equipment changes and document ownership if necessary. Insurance should work alongside sensible security and maintenance practices. Together, these measures help owners address the financial and operational consequences of losing equipment that their daily work depends on.
Building Protection Around Your Entire Operation
Your business faces responsibilities beyond its vehicles and physical assets. Customer interactions, work performed on someone else's property, and the services you deliver can all create exposure to claims. At the same time, everyday financial tasks influence how well you manage expenses, payments, and growth. Considering liability and business support together provides a more complete view of operational needs. Liability discussions should reflect your activities, including deliveries, installation work, mobile services, and any specialized tasks. Business support discussions should focus on where administrative demands consume time or make decisions harder. Through routeway360, owners can explore liability coverage alongside services such as business banking, payroll, accounting, and route support. Choosing suitable assistance can help organize responsibilities and improve visibility into the operation. The purpose is to build a system that supports the way your business works, rather than collecting services without a clear need. When protection and administration receive consistent attention, owners are better positioned to recognize changes, maintain useful records, and make informed decisions about new customers, projects, employees, and business opportunities as their operations develop and expand over time.
Addressing Liability Beyond the Road
Working with customers brings responsibilities that deserve attention before a claim occurs. An accidental injury, property damage, or dispute involving your work can interrupt operations and create financial pressure. Business liability coverage should be discussed in relation to the services you provide. Explain where work takes place, whether customers visit your premises, and whether employees or subcontractors perform tasks on your behalf. Ask which activities are covered and which may require additional consideration. Contracts can also specify insurance requirements, coverage limits, or documentation needed before a project or delivery arrangement begins. Reviewing these details early helps you avoid misunderstandings and delays. Clear work descriptions, careful procedures, and accurate records remain valuable regardless of the insurance selected. A useful liability review gives you a clearer understanding of your responsibilities and how available options address them. Repeat that review when your services change or you begin working with different types of customers.
Supporting Your Business with Better Financial Organization
Strong administrative processes make it easier to understand what your business earns, spends, and needs next. Separating business and personal transactions through suitable banking arrangements creates clearer records. Accounting support can help track expenses, customer payments, and the performance of different routes or services. Payroll support can help organize worker payments and related documentation as your team develops. Route support can address operational needs that become more demanding as the business grows. These services should be selected according to responsibilities, available resources, and the complexity of your operation. Begin with the tasks that regularly cause delays, confusion, or incomplete records. Better organization can make it easier to prepare information for insurance reviews and identify changes in assets or activities. It also helps owners evaluate whether new opportunities fit their financial position. Consistent administrative habits create a practical foundation for managing daily work and planning future expansion with clearer business information.
Conclusion
Protecting a business means looking at the full operation, including the assets, activities, and responsibilities that support your income. Vehicle coverage plays an important role, but goods in transit, essential equipment, customer interactions, and specialty services may need separate consideration. Understanding these areas helps you ask specific questions instead of relying on assumptions about what one policy includes. Start by documenting your vehicles, cargo, tools, work locations, and services. Review customer agreements and explain any unusual activities when discussing coverage. Then consider whether banking, payroll, accounting, or route support could improve the way you manage everyday responsibilities. Organized information supports better conversations and makes changes easier to identify. As your business develops, revisit both protection and administrative processes so they continue to reflect your operation. The right approach depends on what you do, what you own, and the obligations you accept. With thoughtful guidance and consistent reviews, independent distributors, contractors, route owners, and mobile businesses can build a stronger foundation for reliable service, informed decisions, and sustainable growth while remaining better prepared for the challenges that arise along the way.