Philippines Ammonia Market Projected to Reach USD 2,476.56 Million by 2034
Philippines ammonia market is set to grow from USD 1.73B to USD 2.48B by 2034. Explore fertilizer demand, mining expansion, and opportunities.
 Ranjeet Sharma
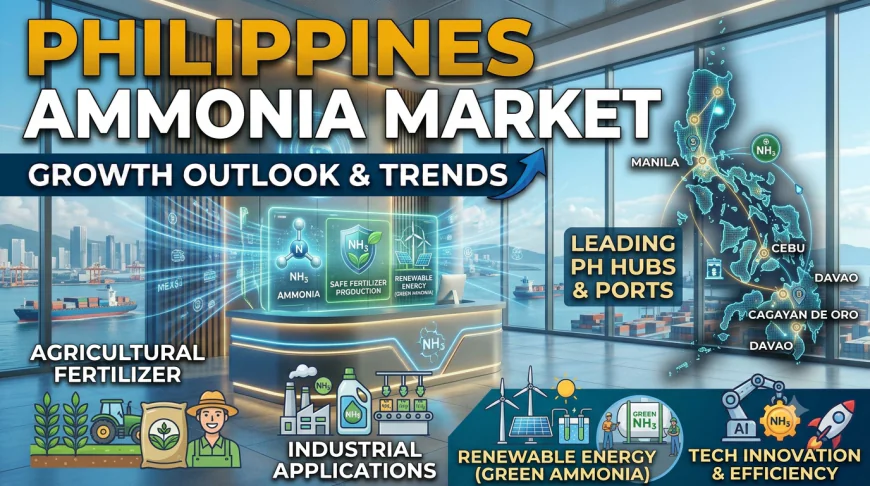
Philippine agricultural planners are confronting a challenge that strikes at the heart of national food security. The country's population continues to expand while per-capita arable land diminishes, creating relentless pressure to elevate crop yields. Ammonia-based nitrogenous fertilizers constitute essential inputs for rice cultivation, which remains the staple food crop supporting millions of Filipinos. Yet the Philippines relies heavily on imported ammonia due to limited domestic production capacity, exposing the market to global price volatility and supply chain disruptions. The Philippines ammonia market sits at the centre of this strategic vulnerability. Valued at USD 1,733.75 million in 2025, the market is projected to reach USD 2,476.56 million by 2034, growing at a compound annual growth rate of 4.04 per cent from 2026 to 2034. These figures reflect an industry balancing agricultural necessity with industrial diversification.
What's Driving Growth of the Philippines Ammonia Market?
Agricultural intensification and rising fertilizer demand are anchoring baseline consumption. The Philippines confronts mounting pressure to elevate agricultural productivity amid expanding population demographics and diminishing per-capita arable land availability. Ammonia-based nitrogenous fertilizers constitute essential inputs for rice cultivation, which remains the staple food crop supporting millions of Filipinos. The Department of Agriculture's ongoing campaigns aimed at promoting hybrid seed adoption, alongside appropriate fertilizer regimens, are demonstrating measurable yield improvements across key rice-producing regions including Central Luzon, Cagayan Valley, and Western Visayas. Government distribution programmes, combined with private sector supply chains, ensure fertilizer accessibility for smallholder farmers who constitute the backbone of Philippine agriculture.
Government infrastructure investment and mining sector expansion are driving industrial demand. Industrial ammonia consumption is experiencing substantial growth, driven by accelerating mining and quarrying activities across the Philippines. The Department of Environment and Natural Resources has issued numerous quarrying licences throughout Mindanao and Luzon regions, directly stimulating procurement of ammonium nitrate for limestone and granite extraction operations essential to construction material supply chains. These mining expansions align with government infrastructure development priorities under comprehensive economic planning frameworks targeting transportation network improvements and urban development initiatives.
Energy transition initiatives and green ammonia development are creating new opportunities. As the country seeks to reduce carbon emissions and adopt cleaner energy pathways, ammonia is gaining attention as a viable hydrogen carrier and a potential low-carbon fuel for future power systems. This drives investment interest in renewable-powered ammonia plants, pilot hydrogen-ammonia blending projects, and research partnerships focused on decarbonising fertilizer and industrial processes. The Department of Energy's Hydrogen and Fusion Energy Roadmap, established to facilitate carbon neutrality objectives, positions ammonia as a pivotal energy carrier for power generation decarbonisation.
AI and digital technologies are transforming safety and supply chain operations. IoT-enabled monitoring systems integrated with AI algorithms provide real-time surveillance of ammonia storage facilities and transportation networks, significantly reducing accident risks associated with this hazardous substance. These digitalised solutions enable predictive maintenance scheduling, leak detection capabilities, and automated emergency response mechanisms. AI-driven precision agriculture platforms are optimising fertilizer application strategies by analysing soil health metrics, weather patterns, and crop-specific nutrient requirements.
Three Trends Reshaping the Industry
Green ammonia is emerging as a strategic energy vector.
Energy transition initiatives and the shift towards green ammonia production are aligning the sector with national sustainability goals. Government emphasis on renewable energy expansion, particularly solar, wind, and geothermal, is creating opportunities to integrate these sources into green ammonia production. Global supply chain pressure for low-carbon agricultural inputs encourages local producers to explore greener technologies. These trends enhance long-term market prospects by positioning ammonia as both a strategic energy vector and an environmentally aligned industrial chemical.
Why it matters: Green ammonia aligns agricultural and industrial demand with national decarbonisation objectives.
Business implication: Producers must invest in renewable-powered production capabilities and explore hydrogen-ammonia blending applications.
Future impact: Green ammonia will create new demand categories in power generation and clean fuel applications.
Mining expansion is diversifying demand beyond agriculture.
Industrial ammonia consumption is experiencing substantial growth driven by accelerating mining and quarrying activities. Ammonium nitrate-based explosives dominate blasting applications due to favourable handling characteristics and storage compliance with local regulatory frameworks. Infrastructure construction supporting renewable energy installations, port facility expansions, and flood control systems further compounds industrial ammonia derivatives demand. This industrial diversification is creating resilience against agricultural sector volatilities while generating higher-value market segments characterised by specialised product specifications and premium pricing structures.
Why it matters: Industrial diversification reduces the market's vulnerability to agricultural cycles.
Business implication: Suppliers must develop product specifications and logistics capabilities tailored to mining customers.
Future impact: Mining and infrastructure will become increasingly significant demand drivers alongside agriculture.
Import dependency is driving investment in domestic production capacity.
Import dependency and supply chain vulnerabilities significantly challenge market growth, as the country relies heavily on imported ammonia and feedstock materials due to limited domestic production capacity. This dependence exposes the market to global price volatility, geopolitical tensions, freight disruptions, and currency fluctuations. These vulnerabilities discourage long-term investment in downstream ammonia-based products. The market's competitive structure is characterised by dependence on international suppliers alongside emerging domestic distribution networks, with major multinational corporations maintaining significant presence through established distribution partnerships.
Why it matters: Import dependency creates strategic vulnerability that constrains market development.
Business implication: Domestic production investment represents a strategic opportunity to reduce vulnerability and capture value.
Future impact: Local production infrastructure will be essential for long-term market resilience and competitiveness.
What the Market Numbers Actually Tell Us
A market expanding from USD 1,733.75 million to USD 2,476.56 million over nine years suggests significantly greater commercial activity across fertilizer producers, chemical manufacturers, mining suppliers, and agricultural distributors. The 4.04 per cent compound annual growth rate signals steady, structural expansion driven by agricultural necessity and industrial diversification. Liquid ammonia dominates the physical form segment, reflecting its primary use in fertilizer production and industrial applications. MAP and DAP represent significant application segments, while urea and ammonium nitrate serve both agricultural and mining demand. Agrochemical represents the largest end-use industry, followed by industrial chemical and mining. Luzon leads regional demand, reflecting population concentration and agricultural activity in Central Luzon, followed by Visayas and Mindanao. For investors and industry participants, the trajectory indicates that ammonia remains essential to Philippine food security and industrial development, with growth driven by agricultural intensification and infrastructure investment.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of domestic production and green ammonia development. Government initiatives promoting precision farming techniques and balanced fertilization practices will intensify ammonia-based fertilizer consumption as the nation addresses food security imperatives. The Department of Energy's Hydrogen and Fusion Energy Roadmap positions ammonia as a pivotal energy carrier for power generation decarbonisation, creating new demand categories. AI-driven precision agriculture platforms are optimising fertilizer application strategies by analysing soil health metrics, weather patterns, and crop-specific nutrient requirements, improving efficiency and reducing waste. Companies that can navigate the complex regulatory landscape, invest in domestic production capacity, and develop green ammonia capabilities are well-positioned to capture value in this evolving market. Major multinational corporations maintain significant market presence through established distribution partnerships, leveraging extensive research and development capabilities and integrated supply chain infrastructure.