India Co-Working Office Space Market Size, Occupancy Trends and Forecast 2026-2034
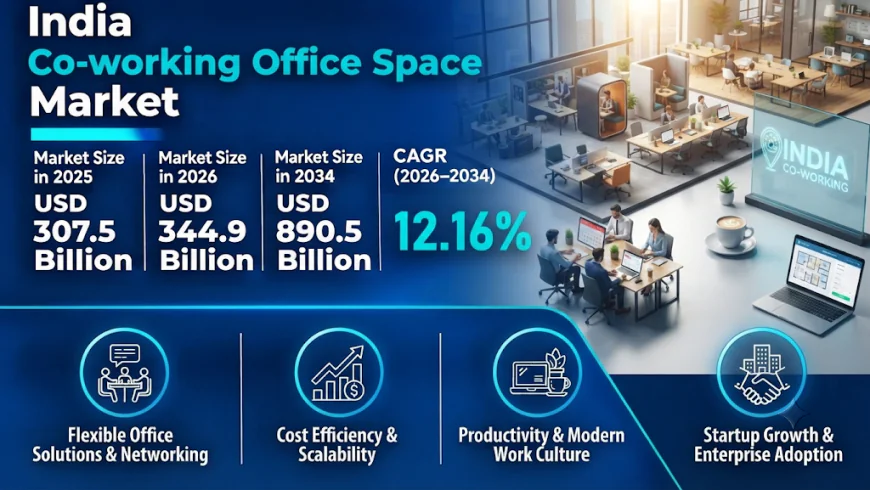
India co-working office space market size reached USD 307.5 Million in 2025, expected to reach USD 890.5 Million by 2034 at 12.16% CAGR.
 chetan kalyan
India Co-working Office Space Market Outlook
The India co-working office space market is expanding as enterprises, startups and freelancers shift toward flexible, ready-to-use workspaces. Hybrid work adoption, short-term lease preferences and cost efficiency for startups are the main forces behind this shift, alongside a growing focus on employee well-being. Flexible managed offices and serviced offices are gaining traction as corporations decentralize operations and reduce real estate overheads.
The market outlook is also shaped by geography. Tech hubs are spreading beyond the metros into Tier 2 cities, and operators are adding enterprise-grade formats, IoT-enabled services and green-certified buildings. According to IMARC Group, the coworking space market size in India stood at USD 307.5 Million in 2025, and strong enterprise demand is expected to sustain growth through 2034.
Market Snapshot
- Market Size (2025): USD 307.5 Million
- Forecast Market Size (2034): USD 890.5 Million
- CAGR (2026-2034): 12.16%
- Types: Flexible Managed Office, Serviced Office
- Largest Region (2025): West and Central India
- Key Applications: IT and ITES, Legal Services, BFSI, Consulting
- Key Drivers: Hybrid work, startup cost efficiency, enterprise adoption, Tier 2 city expansion
Key Market Drivers
- Hybrid Work and Demand for Flexible Workspaces:
Large corporations are using co-working spaces to support satellite teams, project-based work and employee mobility. Flexible lease terms, scalability and ready infrastructure offer clear advantages over traditional long-term leases.
- Startup and SME Growth:
A growing freelancer and SME base needs low-commitment, cost-efficient offices. Pay-per-use desks, dedicated desks and private cabins allow operators to serve a wide range of customers.
- Enterprise Adoption:
IT, consulting and financial services firms are setting up satellite offices through managed co-working centers with dedicated floors, branded designs, secure networks and access control. India’s co-working office space is projected to reach 125 million sq. ft by March 2027 from 80 million sq. ft in December 2024, according to the India Brand Equity Foundation (IBEF).
- Government and Policy Support:
Government incentives for regional business growth and state-backed initiatives are encouraging operators to open centers beyond metros. Programs such as Startup India, Digital India, Software Technology Parks of India (STPI) and the Smart Cities Mission strengthen the ecosystem that feeds flexible workspace demand.
Evaluate Market Opportunity with the Business Sample Report
Emerging Trends
- Growth in Tier 2 Cities:
Jaipur, Indore, Kochi, Lucknow and Coimbatore are gaining co-working centers thanks to improved infrastructure, lower real estate costs and rising talent pools. In May 2025, IWG announced plans to launch its Signature brand in India, targeting Tier II and III cities with 40-50 new centers by 2025.
- Premium Co-working in Metropolitan Areas:
Bengaluru commands a significant share of supply and demand, while NCR and Mumbai benefit from their corporate and financial roles. Premium formats are also rising in Pune, Hyderabad and Chennai.
- Technology and Sustainability Integration:
Operators are using IoT for real-time monitoring of occupancy, energy and maintenance, and AI for visitor management and predictive maintenance. IGBC or LEED-certified design and renewable energy use are becoming differentiators.
- Financial Performance and Revenue Diversification:
Occupancy in top centers has rebounded to pre-pandemic levels, and value-added services such as concierge, event hosting and business support are becoming key profitability drivers.
Market Challenges
Despite strong growth momentum, the market faces several structural and cultural headwinds:
- Permanent remote work policies and hybrid models, especially among IT and tech firms, have tempered long-term demand in certain urban pockets
- Legacy office cultures and traditional corporate hierarchies resist adoption in sectors that prioritize controlled environments
- Market saturation in core metros has intensified competition and pressured margins for smaller operators
- Demand uncertainty is pushing operators to invest in managed offices, enterprise centers and experience design to stay differentiated
Explore the Full Report with Charts, Table of Contents, and List of Figures
Segment Insights
By Type
- Flexible Managed Office (customized, enterprise-focused floors with branded design)
- Serviced Office (ready-to-use space with bundled services)
By Application
- Information Technology (IT and ITES)
- Legal Services
- BFSI
- Consulting
- Others
By End User
- Personal User
- Small Scale Company
- Large Scale Company
- Others
Regional Insights
- North India: NCR (Delhi, Gurgaon, Noida) as a corporate hub with strong enterprise demand
- South India: Bengaluru’s startup, IT and global capability center base, plus growth in Hyderabad, Chennai and Kochi
- West India: Mumbai’s financial hub and Pune’s growing premium centers; West and Central India is the largest region in 2025
- East India: emerging demand as flexible workspace formats spread to new cities
Competitive Landscape
The India co-working office space market includes national operators, global flexible workspace brands and real estate developers launching their own co-working brands. Players compete on location, enterprise-grade customization, technology integration and pricing flexibility.
The report offers an in-depth examination of the competitive landscape, including market structure, key player positioning, leading strategies for success, a competitive dashboard, and a company evaluation quadrant.
Recent Developments
- August 2025: The Kerala government launched “i by Infopark,” a neurodiversity-friendly coworking facility at Ernakulam South Metro Station, spanning 48,000 sq ft with 582 seats for gig workers, freelancers, multinationals and Global Capability Centres
- July 2025: Smartworks Coworking Spaces launched its IPO, raising approximately INR 582.56 crore in total with robust investor interest
- June 2025: 91Springboard opened six new centers across Mumbai, Delhi-NCR and Pune, adding about 3,600 desks and over 170,000 square feet, expanding the co-working office space market size in India
- May 2025: Sumadhura Group launched its co-working brand Workship with a 1.3 lakh sq ft center in Whitefield, Bengaluru
- January 2025: iSprout opened its first Gurugram facility, with over 900 seats, taking its network to 23 centers in India
Investment Opportunities
- High-Growth Formats: Flexible managed offices for large enterprises are a clear opportunity, as corporates seek dedicated floors, secure networks and branded workspaces without long leases.
- Geographic Priority Markets: Tier 2 cities such as Jaipur, Indore, Kochi, Lucknow and Coimbatore, plus premium centers in Pune, Hyderabad and Chennai, offer lower costs and growing talent pools.
- Technology and Sustainability Platforms: Operators that combine IoT, AI-based space management and green-certified buildings can win enterprise clients and improve margins.
Request Customized Data Tailored to Your Interest
Frequently Asked Questions (FAQ)
- What is the size of the India co-working office space market?
The market was valued at USD 307.5 Million in 2025.
- What is the projected CAGR?
The market is projected to grow at a CAGR of 12.16% during 2026-2034, reaching USD 890.5 Million by 2034.
- What are the key drivers?
Hybrid work, rapid urbanization, rising real estate costs, shorter lease commitments, startup and SME growth, and enterprise demand for managed offices.
- Which region is the largest?
West and Central India was the largest region in 2025.
- What challenges does the market face?
Permanent remote work policies, resistance from legacy office cultures and saturation in core metros that pressures smaller operators’ margins.
Conclusion
India’s co-working office space market is entering a sustained growth phase, supported by hybrid work, enterprise adoption and the spread of tech hubs into Tier 2 cities. Operators are responding with managed offices, technology integration and sustainable design.
Companies that invest in enterprise-grade formats, Tier 2 presence and digital workspace platforms will capture the largest share of growth as India’s market scales toward USD 890.5 Million by 2034.
Source: IMARC Group