Mexico Oncology Drugs Market Size, Share, Trends Analysis, Forecast 2026-2034
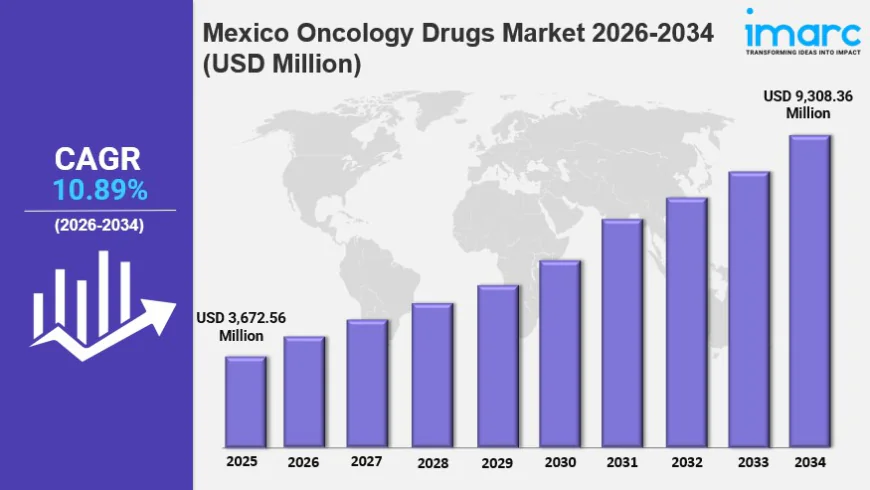
The Mexico oncology drugs market size reached USD 3,672.56 Million in 2025 and is projected to reach USD 9,308.36 Million by 2034, expanding at a CAGR of 10.89% during 2026-2034.
 marketinsights
IMARC Group has recently released a new research study titled "Mexico Oncology Drugs Market Size, Share, Trends and Forecast by Product, Therapy, Indication, Dosage Form, Distribution Channel, and Region, 2026-2034", offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.
Mexico Oncology Drugs Market Size & Share 2026-2034
The Mexico oncology drugs market size reached USD 3,672.56 Million in 2025 and is projected to reach USD 9,308.36 Million by 2034, expanding at a CAGR of 10.89% during 2026-2034. In 2026, the market continues to gain momentum, propelled by substantial government investment in cancer care infrastructure, the implementation of national cancer control programs that improve treatment accessibility, and regulatory modernization that is accelerating biosimilar approvals.
Growth in 2026 is further reinforced by falling drug costs and wider affordable treatment options, along with increased domestic pharmaceutical manufacturing capacity that is strengthening supply chains. These dynamics are expected to strengthen the Mexico oncology drugs market share throughout the forecast period.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020-2025
- Forecast Period: 2026-2034
- Market Size (2025): USD 3,672.56 Million
- Projected Market Size (2034): USD 9,308.36 Million
- Growth Rate: CAGR of 10.89% (2026-2034)
Explore Opportunities in the Mexico Oncology Drugs Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-oncology-drugs-market/requestsample
Key Growth Drivers and Trends in the Mexico Oncology Drugs Market
Growth in the Mexico oncology drugs market is being driven by government investment in national cancer infrastructure. The federal government is expanding diagnostic capabilities, building specialized treatment facilities, and working to ensure equitable access to cancer services across regions. In October 2025, it announced the Universal Breast Cancer Care Model, backed by 8 billion pesos funded by IMSS and the federal government through ISSSTE and IMSS Bienestar. The program includes purchasing 1,000 mammography units and 1,000 ultrasound devices and building a dedicated Oncology Care Center in each of Mexico's 32 states, with the aim of reducing breast cancer mortality by 2027. A planned consolidated purchasing model is also intended to secure a steady supply of oncology medicines across the public system.
One of the leading Mexico oncology drugs market trends is regulatory modernization that is speeding biosimilar approvals and increasing competition. In February 2024, the Ministry of Health and COFEPRIS introduced the Regulatory Certainty Strategy for the Pharmaceutical Sector: Biosimilars for 2024-2026, creating the Biosimilars Specialized Unit (UEBio) and the CODEBio committee and revising NOM-177-SSA1-2013 to align with World Health Organization standards. In July 2024, Zydus Lifesciences received COFEPRIS approval for its bevacizumab biosimilar, and in August 2025 COFEPRIS introduced an abbreviated pathway recognizing evaluations from IMDRF members and MDSAP participants. These changes are drawing domestic firms such as Probiomed and Landsteiner alongside international manufacturers such as Biocon and Celltrion.
Another key factor supporting Mexico oncology drugs market growth is strategic investment in domestic pharmaceutical manufacturing. In July 2025, four major Mexican pharmaceutical companies announced investment plans totaling over 13 billion pesos under President Claudia Sheinbaum's Plan Mexico. Laboratorios Kener committed 5.18 billion pesos to expand its Toluca plant, with plans to triple installed capacity by the first quarter of 2027, focusing heavily on in-hospital injectable oncology medicines. A presidential decree also requires companies seeking public procurement contracts to invest locally in manufacturing or infrastructure, channeling over 300 billion pesos of public spending into a national biopharmaceutical ecosystem.
Rising cancer incidence and expanding healthcare coverage under IMSS-Bienestar are sustaining demand, while artificial intelligence is supporting precision medicine, improving early cancer detection, helping optimize chemotherapy regimens, and streamlining clinical trial design and drug discovery.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=43807&flag=C
Mexico Oncology Drugs Industry Segmentation Insights
Breakup by Product:
- Cytotoxic Drugs: Conventional chemotherapy agents that kill rapidly dividing cells, including alkylating agents and antimetabolites, which remain foundational across many cancer types.
- Targeted Drugs: Medicines designed to act on specific molecular targets in cancer cells, supporting precision medicine approaches and including biologic and biosimilar products.
- Hormonal Drugs: Medicines that block or lower hormones that fuel certain cancers, commonly used in breast and prostate cancer.
Breakup by Therapy:
- Chemotherapy: Systemic drug treatment using cytotoxic agents, a long-established mainstay of cancer care across the public healthcare system.
- Targeted Therapy: Treatment directed at specific cancer-related molecules, expanding as biosimilar approvals lower costs and widen access.
- Immunotherapy: Treatment that helps the immune system recognize and attack cancer, an area of innovation led by multinational companies.
Breakup by Indication:
- Lung Cancer: One of the major cancer types treated with chemotherapy, targeted therapy, and immunotherapy.
- Stomach Cancer: A significant indication in Mexico treated primarily with chemotherapy and increasingly with targeted agents.
- Colorectal Cancer: A major indication supported by screening and early detection efforts and a range of chemotherapy and targeted options.
- Breast Cancer: A national priority, supported by the Universal Breast Cancer Care Model and expanded screening and treatment infrastructure.
- Prostate Cancer: A national priority indication in which hormonal drugs play a key role.
Breakup by Dosage Form:
- Solid: Includes tablets and capsules, suited to oral oncology medicines that patients can take outside the hospital.
- Liquid: Oral and other liquid formulations used where dose flexibility or ease of administration is needed.
- Injectable: Administered in hospital settings and central to chemotherapy and biologic treatments, and a core focus for domestic manufacturers such as Laboratorios Kener.
Breakup by Distribution Channel:
- Hospital Pharmacies: Supply the in-hospital injectable and specialty medicines used in cancer centers, with public healthcare institutions representing the largest purchasing segment.
- Retail Pharmacies: Dispense oral and outpatient oncology medicines to patients, particularly in the private sector.
- Online Pharmacies: An emerging channel offering convenient ordering and home delivery of eligible medicines.
Breakup by Region:
- Northern Mexico: Typically achieves better cancer outcomes thanks to a greater concentration of specialized facilities, experienced oncologists, and advanced diagnostic equipment.
- Central Mexico: A major demand center that includes Mexico City, home to specialized institutes and expanded IMSS screening and early diagnosis clinics.
- Southern Mexico: Hosts a higher proportion of marginalized communities with limited healthcare infrastructure, which restricts timely diagnosis and treatment access.
- Others: Covers the remaining regions of Mexico not included in the three main regional groupings.
Key Challenges and Growth Opportunities in the Mexico Oncology Drugs Market
The Mexico oncology drugs market faces significant challenges. Healthcare budget constraints are limiting access: the 2025 health sector budget was 918.4 billion pesos, an 11% decrease from 2024, with health spending projected at 2.5% of GDP, well below the 6% minimum recommended by the World Health Organization. Persistent medication shortages also disrupt treatment, including a severe shortage of essential cancer drugs documented in March 2025 that affected foundational chemotherapy agents, although a 2025-2026 consolidated purchasing allocation of 123 billion pesos for cancer treatments aims to address supply problems. In addition, a fragmented healthcare system spanning IMSS, ISSSTE, IMSS-Bienestar, and private providers creates regional disparities in access, with Northern states generally achieving better outcomes than Southern states.
Despite this, the market offers considerable growth opportunities driven by expanding cancer infrastructure, faster biosimilar approvals that lower treatment costs, growing domestic manufacturing capacity, and rising healthcare coverage. Innovation in targeted therapies and immunotherapies, together with AI-enabled diagnostics and clinical research, is expected to create substantial opportunities for long-term growth in the Mexico oncology drugs market.
Competitive Landscape
The Mexico oncology drugs market is competitive, with multinational pharmaceutical corporations and emerging domestic manufacturers competing across branded and biosimilar segments. International leaders including Roche, Pfizer, Sanofi, Bayer, and Novartis maintain strong positions through established oncology portfolios, global research capabilities, and extensive distribution networks, and focus on innovative targeted therapies and immunotherapies while retaining leadership in traditional chemotherapy. Domestic players such as Pisa, Grupo Neolpharma, and Laboratorios Kener are increasingly competitive in generic oncology medicines and biosimilars, offering cost advantages and local manufacturing.
The biosimilar regulatory framework is attracting established biosimilar makers such as Biocon and Celltrion as well as domestic firms such as Probiomed and Landsteiner, intensifying price competition, particularly in monoclonal antibodies. Competition centers on product quality, regulatory compliance, pricing, distribution efficiency, and partnerships with public healthcare institutions, which represent the largest purchasing segment.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: [email protected]
United States: +1-201-971-6302