Life Insurance UK: A Complete Guide to Quotes, Cover Types and Choosing the Right Policy
Discover how life insurance works in the UK, what affects monthly premiums, and how to compare policies for your mortgage and family's needs.
 assuredlifeuk
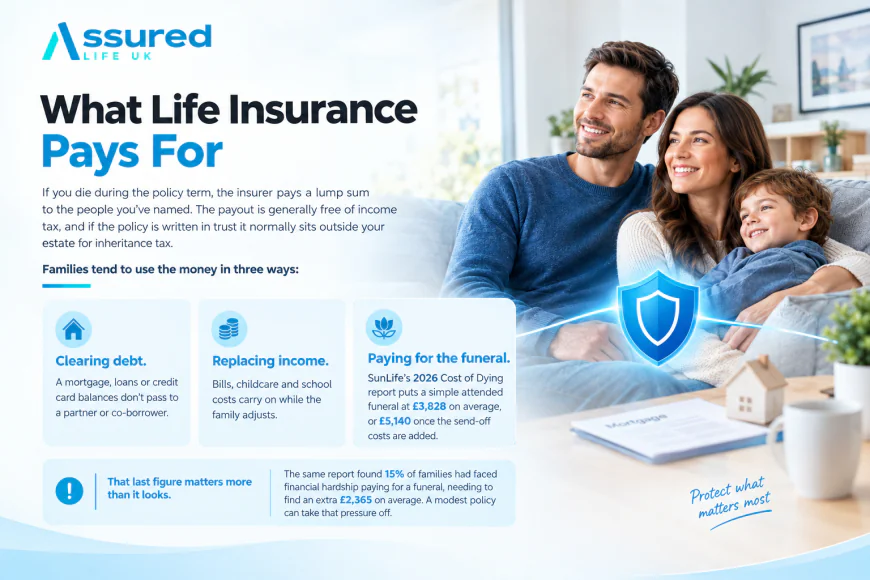
Choosing life insurance UK cover is an important step towards protecting the people who depend on you financially. Whether you are a parent with young children, a homeowner with a mortgage, a couple planning for the future or someone approaching retirement, the right policy can help your loved ones manage financially if you die.
However, with different insurers, premiums, policy terms and levels of protection available, knowing where to start can feel overwhelming. Should you choose term life insurance, whole life insurance, or over 50s life insurance? Is it worth adding life insurance and critical illness cover? And how can you find suitable life insurance quotes without paying for protection you do not need?
This guide explains how life insurance works in the UK, what affects the price, how to compare policies and what to consider before choosing cover. It is designed to help you make an informed decision based on your circumstances, financial responsibilities and long-term goals.
What Is Life Insurance and How Does It Work in the UK?
What is life insurance uk? It is a financial protection product that pays an agreed benefit if the person insured dies while the policy meets its terms and conditions. Depending on the policy, the benefit may be paid as a lump sum or, in some cases, through regular payments. Your chosen beneficiaries can use the money to help manage household bills, mortgage commitments, childcare costs, funeral expenses or other financial responsibilities.
Think of life insurance uk as a financial safety net. You cannot replace the emotional support a family member provides, but you can take steps to reduce the financial difficulties your family might face without your income. For a household that relies on one or two earners, that protection can make a meaningful difference during an already difficult period.
How Does a Life Insurance Policy Work?
When you apply for a life insurance policy, you choose the amount of cover, the length of protection and the people or arrangements intended to receive the payout. The insurer assesses your application and provides a premium based on factors such as your age, health, lifestyle and the policy benefits requested. If you accept the terms and keep up with payments, your cover continues according to the contract.
If you die during the insured period, your beneficiaries or the appropriate legal representative can submit a claim. The insurer reviews the claim against the policy conditions before paying any benefit due. Some policies also include terminal illness benefits, subject to their definitions and eligibility requirements. It is important to understand exclusions, disclosure requirements and claim conditions before buying.
Who Should Consider Life Insurance?
Life insurance may be particularly relevant if other people depend on your income or if you have substantial financial commitments. Parents may want to provide for children, homeowners may want to help a partner maintain the family home, and couples may want to cover shared debts. Self-employed people might also consider how their family's finances would change if their income disappeared.
Not everyone needs the same level of protection. If you have no financial dependants, little debt and enough savings to meet your obligations, you may have less need for life insurance. The important question is not simply whether you should buy cover, but what financial problem you want the policy to solve.
Why Life Insurance Matters for You and Your Family
Your income often supports far more than everyday spending. It may pay the mortgage, household utilities, school expenses, transport, childcare and contributions to savings. If that income suddenly disappears, your family may need to make difficult financial decisions at a time when they are coping with bereavement. Life insurance for family protection can provide money to help cover those costs and give surviving family members more time to adjust.
For example, imagine a household where one parent earns most of the income while the other manages childcare. If the main earner dies, the surviving parent might need to pay for childcare, reduce working hours or make alternative living arrangements. A suitable payout could help cover these expenses while the family considers its next steps.
Life insurance can also help protect longer-term goals. Parents may want to contribute towards university costs, maintain a child's standard of living or leave money for future needs. Couples may want to clear a mortgage or other outstanding debts. Older policyholders may wish to provide a contribution towards funeral costs or leave a financial gift to loved ones.
The appropriate amount depends on your circumstances. Review existing savings, workplace death-in-service benefits, pensions, debts and other financial resources before deciding how much additional cover you need. Remember that workplace benefits may end when you leave your employer, so they should not automatically be treated as permanent protection.
Understanding the Different Types of Life Insurance Policies
There is no single policy that suits every household. Different types of cover serve different purposes, and understanding those differences can help you avoid paying for benefits that do not match your needs.
Term Life Insurance
Term life insurance provides protection for a specified period, such as 10, 20 or 25 years. If the insured person dies during that term and the claim meets the policy conditions, the insurer pays the agreed benefit. If the policyholder survives until the end of the term, a standard term policy usually expires without a payout.
There are several common variations:
-
Level term insurance: The amount of cover remains the same throughout the policy term. It may suit families who want a consistent lump sum to help replace income or cover future expenses.
-
Decreasing term insurance: The amount of cover reduces over time. It is often used alongside a repayment mortgage because the outstanding mortgage balance generally falls as repayments are made.
-
Increasing term insurance: The level of cover rises according to the policy's agreed method, which may help offset the effects of inflation. Premiums and increases depend on the contract.
Term cover can be useful when your financial responsibilities have an expected end date. For example, you might choose protection that lasts until your children become financially independent or your mortgage is due to be repaid.
Whole Life Insurance
Whole life insurance is designed to provide cover for your lifetime, provided you meet the policy's payment requirements and conditions. Unlike term cover, it is not normally limited to a fixed number of years. This makes it an option for people who want to leave a guaranteed death benefit under the terms of the policy, rather than cover only a particular period.
Whole life policies may be considered for estate planning, funeral costs or leaving money to beneficiaries. However, premiums can be higher than those for comparable term policies because the insurer expects a claim to be made eventually. Some policies also have specific premium structures or review conditions, so check whether payments are fixed and how long they must continue.
Over 50s Life Insurance
Over 50s life insurance is generally aimed at people aged 50 and above, with eligible ages depending on the insurer. Many plans offer guaranteed acceptance without medical questions, subject to their terms, and pay a fixed lump sum when the policyholder dies. People often consider this type of cover to help with funeral expenses or leave money for family members.
Before buying life insurance over 50, compare the payout with the total premiums you could pay over time. A policy with a low monthly premium may offer only a modest benefit, and you could pay more into it than your family eventually receives. Some plans also have an initial waiting period or limited benefits for certain causes of death, so read the policy details carefully.
Do not assume that a specialist over-50s plan is automatically your best option. Depending on your health and circumstances, standard term or whole life cover may be worth comparing as well.
Life Insurance and Critical Illness Cover
Life insurance uk and critical illness cover can provide different types of financial protection. Life insurance normally pays a benefit when the insured person dies, subject to the contract. Critical illness insurance may pay a lump sum if the insured person is diagnosed with a specified condition that meets the policy's definition.
A combined life and critical illness cover policy can be useful for someone who wants to protect their family in the event of death while also considering the financial impact of certain serious illnesses. A qualifying critical illness payout could help with household bills, adjustments to the home or time away from work.
However, critical illness cover does not pay for every illness or every diagnosis. Conditions, severity requirements, exclusions and survival periods can vary between policies. Check whether a critical illness claim reduces or ends the life cover, and whether separate policies would provide more appropriate protection.
How to Get Life Insurance Quotes in the UK
Getting life insurance quotes is a practical starting point when you want to understand your options and budget. A quotation estimates how much an insurer may charge for a particular level of cover based on the information you provide. It is not always a final offer, because the price or terms may change after underwriting, medical questions or further checks.
The most useful approach is to compare policies with similar benefits. A £200,000 policy lasting 25 years is not directly comparable with a £100,000 policy lasting 10 years. Differences in exclusions, premium guarantees and additional benefits can also affect the value of a quotation.
Step-by-Step Guide to Getting a Life Insurance Quotation
Step 1: Decide what you want to protect. Start by identifying the financial commitments your family would struggle to manage without your income. These could include a mortgage, personal debts, childcare, everyday living costs or future education expenses.
Step 2: Estimate the amount of cover you need. Consider your outstanding debts, the income your household would need to replace, your dependants' likely needs and any existing savings or workplace benefits. This gives you a useful starting point before requesting quotations.
Step 3: Choose the policy term. Think about how long your family will depend on your income or how long your mortgage is expected to last. The policy term should reflect your actual responsibilities rather than simply choosing the shortest option available.
Step 4: Compare multiple insurers. Request a life insurance quotation from several providers or use a comparison service. Check the coverage amount, monthly premium, policy term and important exclusions rather than choosing solely on price.
Step 5: Answer application questions accurately. Insurers may ask about your health, smoking status, occupation, lifestyle and medical history. Provide complete and truthful information because inaccurate or incomplete answers could affect a future claim.
Step 6: Read the policy documents before accepting. Check when cover starts, whether premiums are guaranteed, what the policy excludes and how claims work. Confirm that the policy meets your needs before committing to ongoing payments.
A well-chosen quotation should help you understand both affordability and protection. The cheapest offer is not necessarily the most suitable if it provides too little cover or excludes a benefit you need.
How Much Is Life Insurance in the UK?
One of the most common questions people ask is, how much is life insurance? There is no single price because premiums depend on personal circumstances, the amount of cover and the policy's terms. Two people seeking the same payout can receive different quotations because their ages, health histories and lifestyles may differ.
For example, a healthy 30-year-old looking for a straightforward term policy may receive a different quotation from a 50-year-old applying for the same amount of protection. Smoking status, certain health conditions, occupation and the length of the policy can also affect the price. A larger payout generally costs more than a smaller one when other factors are comparable.
The best way to understand your likely cost is to request personalised quotations rather than rely on a headline price advertised online.
What Factors Affect Life Insurance Premiums?
-
Age: Premiums generally increase as you get older because the likelihood of a claim during the insured period changes.
-
Health: Medical conditions and medical history may influence the insurer's assessment and the terms offered.
-
Smoking status: Smokers often pay more than comparable non-smokers.
-
Cover amount: A higher sum assured usually costs more.
-
Policy duration: Longer terms generally mean the insurer covers you for more years.
-
Policy type: Whole life insurance and policies with additional benefits can cost more than basic term cover.
-
Lifestyle and occupation: Some activities or occupations may affect the underwriting assessment.
How Can You Make Cover More Affordable?
Start with a realistic assessment of your needs instead of choosing the largest amount available. If your main concern is a repayment mortgage, decreasing term cover may be worth considering. If you want to provide a consistent amount for your family, level term cover may be more appropriate.
Compare equivalent policies, check whether your employer already provides death-in-service benefits and review any existing cover before buying additional protection. However, do not reduce your cover to an amount that leaves your family exposed simply to obtain a lower premium. Affordable protection should still address the financial risks you want to manage.
How to Compare Life Insurance and Find Suitable Cover
A life insurance comparison helps you assess the differences between providers and policies. Comparison websites can be a useful starting point, but they may not include every insurer or policy available. A broker may help you explore suitable options, explain policy conditions and understand how underwriting affects your application.
When you compare life insurance, make sure you are comparing like for like. A low premium might relate to a shorter policy term, a lower payout or a different set of benefits. Looking beyond the headline price gives you a better understanding of what you are buying.
Use this checklist when reviewing quotations:
|
What to compare |
Why it matters |
|---|---|
|
Sum assured |
Determines the benefit available if a valid claim is paid. |
|
Policy term |
Shows how long the protection lasts. |
|
Monthly premium |
Helps you assess ongoing affordability. |
|
Premium structure |
Clarifies whether payments are guaranteed or may change. |
|
Exclusions and restrictions |
Explains circumstances in which benefits may not be payable. |
|
Terminal illness benefit |
Shows whether an early payout may be available under specified conditions. |
|
Critical illness options |
Helps you understand additional protection for qualifying diagnoses. |
|
Claims process |
Explains how beneficiaries or representatives can request payment. |
What Makes the Best Life Insurance?
The best life insurance is the policy that provides appropriate protection at a sustainable price for your particular needs. A family with young children may prioritise income replacement, while a homeowner may focus on mortgage protection. Someone nearing retirement may have different objectives, such as contributing towards funeral expenses or leaving money to relatives.
The phrase best life insurance UK should therefore be treated as a personal decision rather than a universal ranking. Consider whether the provider is authorised to offer the relevant service, read the policy documents and check how the insurer handles claims and customer support. The Financial Conduct Authority provides resources to help consumers understand protections and check firms.
You should also consider the financial stability and reputation of the insurer, the clarity of its terms and whether the policy can be maintained for the full term. Choosing carefully at the outset can help you avoid gaps in protection later.
Mortgage Life Insurance and Protecting Your Home
Buying a home is often one of the largest financial commitments a person makes. If you have a mortgage and die before it is repaid, your family may need to continue making repayments while dealing with a loss of income. Mortgage life insurance can provide a payout intended to help cover the outstanding loan or support the household's wider financial needs.
It is important to distinguish life insurance from buildings insurance and other types of mortgage insurance. Buildings insurance protects against specified damage to the property, while mortgage life insurance is designed to provide a death benefit. Mortgage payment protection products may cover certain repayments following events such as illness or unemployment, depending on their terms, but they are not the same as life insurance.
Do You Need Life Insurance for a Mortgage?
Do you need life insurance for a mortgage? In the UK, life insurance is not generally a legal requirement for taking out a residential mortgage. However, your lender may require other forms of protection, such as buildings insurance, under the mortgage agreement.
Although life insurance is usually optional, it may be worth considering if someone else relies on you to maintain the home. Without a suitable payout, a surviving partner might struggle with mortgage payments, especially if they also need to cover childcare and other household costs.
Choosing the Right Mortgage Life Insurance
Decreasing term insurance is often used with a repayment mortgage because the insured amount reduces over time. However, the rate at which the cover decreases may not match your mortgage balance exactly, so check the policy assumptions and repayment schedule.
Level term insurance may suit people who want a consistent payout that could cover the mortgage and leave additional funds for their family. The right choice depends on whether your priority is repaying the loan, replacing income or meeting several financial needs at once.
Before buying cover, consider:
-
The outstanding mortgage balance and remaining term.
-
Whether you have a repayment or interest-only mortgage.
-
Whether a joint policy or separate individual policies better matches your circumstances.
-
Whether your partner could afford the repayments without your income.
-
Whether the payout would be sufficient for other household expenses.
For example, a family may want to cover a £180,000 mortgage while also providing money for living costs. A policy designed only around the mortgage balance may not meet both objectives, so it is important to calculate the overall protection required.
How to Choose the Best Life Insurance UK Providers
Finding the best life insurance UK option involves more than comparing prices. You need a provider whose policy fits your requirements, whose application process you understand and whose terms you can maintain over time. A low monthly premium has limited value if the policy does not provide the protection your family expects.
Start by deciding whether you prefer to buy directly from an insurer, use an online comparison service or speak with an insurance adviser. Direct applications can be convenient, while comparison services help you review several quotations. A suitable broker or adviser may provide additional support in understanding your needs and the differences between policies.
When Should You Use a Life Insurance Broker?
A life insurance broker can help you explore policies from insurers they work with and explain how the available options compare. This may be especially helpful if you have complex financial responsibilities, need to combine different types of cover or have health circumstances that make the application process less straightforward.
Before using a broker, ask which insurers they consider, whether their service is independent or limited to a panel, and how they are paid. If advice is provided, check the firm's regulatory status and the scope of its permissions. You should understand any fees and what service you will receive before proceeding.
For customers considering cover through Assured Life UK, the aim should be to understand your protection needs first, then explore appropriate policy options and compare their terms. Avoid assuming that any one insurer or product will be suitable for every applicant.
Questions to Ask Before Buying
-
Is the premium guaranteed for the full policy term?
-
What happens if I miss a payment?
-
Are there exclusions that affect my circumstances?
-
Can the policy be placed in trust, and what are the implications?
-
How do I update beneficiary or personal details?
-
What documents will my family need to make a claim?
-
Does the insurer offer the level and type of cover I require?
Taking time to ask these questions can make the policy easier to understand and maintain. Keep a record of the policy documents and let your intended beneficiaries know where the information can be found.
What Is a Life Insurance Calculator and How Can It Help?
A life insurance calculator is a planning tool that helps estimate how much cover you may need. It can provide a useful starting point before you request quotations, although its result should not be treated as a guaranteed recommendation or a substitute for reviewing your personal circumstances.
A calculator may ask about your annual income, mortgage, outstanding debts, dependants, savings and the number of years your family may need financial support. Some tools also consider future costs, such as childcare or education, to help build a broader picture of your family's financial requirements.
How to Estimate Your Life Insurance Needs
Follow these steps to create a basic estimate.
Step 1: Calculate outstanding debts. Include your mortgage, personal loans and other liabilities that your family may need to repay.
Step 2: Estimate future living expenses. Work out how much financial support your dependants might need each year and how long they may need it. Consider childcare, food, utilities, transport and other essential costs.
Step 3: Add specific future goals. You might want to provide money for education, university costs or other planned family expenses.
Step 4: Deduct available resources. Consider savings, existing life insurance, suitable workplace benefits and other assets that could realistically help meet those needs.
Step 5: Review the result. Consider inflation, changes in household income and whether your family would need a lump sum or longer-term financial support.
For example, suppose you estimate that your family needs £150,000 to help meet future living costs and £200,000 to repay a mortgage, with £50,000 available from existing resources. A simple starting estimate would be £300,000 in additional protection. This is only an illustration: actual needs depend on timing, income replacement, interest costs, existing benefits and other circumstances.
Review the estimate regularly, especially after buying a home, having a child, changing jobs or taking on significant debt. Your protection needs may change as your financial responsibilities evolve.
Vitality Life Insurance and Other Policy Options
Vitality life insurance is one of the branded options people may encounter when comparing protection policies in the UK. As with other insurers, the details of available cover, premiums, eligibility requirements and optional benefits should be checked against the current policy documents.
When comparing Vitality with other providers, focus on the features that matter to you. These might include the cost of the policy, the amount and duration of cover, the treatment of health disclosures, the availability of critical illness protection and any additional services or rewards attached to a product.
Some products may offer benefits connected with health or activity programmes. However, do not assume that these features are included in every policy or that rewards automatically reduce your insurance premium. Check the current terms, any participation requirements and whether benefits can change over time.
It is also worth comparing the overall cost of a policy with and without optional benefits. A feature that sounds attractive may have little practical value if you do not expect to use it. Conversely, an additional benefit could be relevant if it addresses a genuine need.
The same principle applies when comparing other insurers: judge each policy by its contractual protection, affordability, eligibility requirements and suitability rather than by brand recognition alone.
Life Insurance, Tax and How Much You Can Gift Tax-Free
Life insurance can form part of wider estate planning, particularly if you want to leave money to your family. However, the tax treatment of a payout depends on the circumstances, and a life insurance benefit should not automatically be assumed to fall outside your estate for inheritance tax purposes.
A policy written in trust may allow the benefit to be paid to chosen beneficiaries outside the policyholder's estate, depending on the trust arrangement and circumstances. Trusts have legal and practical implications, so it is sensible to obtain appropriate advice before setting one up.
How Much Can You Gift Tax-Free in the UK?
The question how much can you gift tax free is particularly relevant for people who want to help children or other relatives financially. Under current UK inheritance tax guidance, individuals can generally give away a total of £3,000 each tax year under the annual exemption. Any unused amount can normally be carried forward by one tax year only. The tax year runs from 6 April to 5 April.
Other exemptions may apply, including certain small gifts of up to £250 per recipient per tax year, qualifying wedding or civil partnership gifts, and regular gifts from surplus income that meet the relevant conditions. The rules differ according to the type of gift and the circumstances.
Larger gifts may be treated as potentially exempt transfers. If you die within seven years of making a gift, it may be considered when calculating inheritance tax, subject to applicable thresholds and exemptions. The outcome depends on the value and timing of gifts, the estate and the relevant rules.
Life insurance may sometimes be considered to help manage a potential inheritance tax liability, but it should not be treated as a replacement for sound estate planning. If you are considering substantial gifts, trust arrangements or cover linked to inheritance tax, speak with a qualified tax adviser or solicitor.
Common Life Insurance Mistakes to Avoid
Even a well-intentioned policy can fall short if you overlook important details. Understanding common mistakes can help you choose cover that meets your needs and remains suitable as your circumstances change.
1. Choosing Cover Based Only on Price
The cheapest premium may not provide the right level of protection. Compare the sum assured, policy term, exclusions and included benefits before making a decision. A slightly higher premium may offer more appropriate protection, while an expensive policy may include features you do not need.
2. Underestimating How Much Cover You Need
Your family's needs may extend beyond mortgage repayments. Childcare, everyday bills, outstanding debts and future education costs can all affect the amount required. Use a life insurance calculator as a starting point, then review your estimate against your actual financial commitments.
3. Selecting the Wrong Policy Term
A policy that expires before your children become financially independent may leave a protection gap. Likewise, choosing a term that extends well beyond your financial responsibilities may cost more than necessary. Match the duration to your mortgage, dependants and long-term objectives.
4. Providing Inaccurate Information
Always answer application questions honestly and carefully. Incorrect details about smoking, medical history, occupation or lifestyle could create problems when a claim is assessed. If you are uncertain how to answer a question, ask the insurer or adviser for clarification rather than guessing.
5. Forgetting to Review Your Cover
Major life events can change your protection needs. Marriage, divorce, having children, moving home and taking on new debts are all reasons to review your arrangements. Do not automatically cancel an existing policy before checking whether replacement cover is available and appropriate.
6. Overlooking Policy Exclusions and Conditions
Read the policy wording, including any waiting periods, limitations and conditions attached to additional benefits. Make sure you understand what the insurer will pay for, when it will pay and what circumstances may prevent a claim.
7. Assuming Every Policy Pays Out in Every Situation
A valid claim must meet the contract's requirements. Term insurance generally pays only when the insured person dies within the covered period, while whole life insurance is designed to cover the policyholder's lifetime subject to its terms. Keeping premiums up to date and understanding the policy conditions are essential.
Avoiding these mistakes will not eliminate every uncertainty, but it can help you make a more informed choice and give your family a clearer understanding of the protection in place.
Conclusion: Find the Right Life Insurance for Your Needs
Choosing life insurance UK cover is about protecting the people and commitments that matter most to you. Whether you need term life insurance to support young children, mortgage life insurance to help protect your home, whole life insurance for lifelong protection or over 50s life insurance to leave money to loved ones, the right choice depends on your individual circumstances.
Start by calculating your likely protection needs, reviewing existing benefits and deciding how long you want cover to last. Then obtain life insurance quotes, compare equivalent policies and examine premiums, exclusions and claim conditions carefully. Consider whether life insurance and critical illness cover would provide useful additional protection, and seek professional guidance if your requirements are complex.
For families exploring their options with Assured Life UK, a practical first step is to identify your financial priorities and compare suitable policies before committing to cover. A carefully chosen policy can help reduce financial uncertainty and give your loved ones greater support when they need it most.
Frequently Asked Questions About Life Insurance UK
1. What is life insurance and why do I need it?
Life insurance pays a benefit if the insured person dies and the claim meets the policy conditions. It can help dependants manage mortgage repayments, household expenses, debts and other financial commitments. Whether you need cover depends on your savings, existing benefits and the people who rely on you financially.
2. How much is life insurance in the UK per month?
The monthly cost depends on your age, health, smoking status, cover amount, policy term and chosen benefits. There is no single price that applies to everyone. Request personalised quotations from several insurers and compare the terms as well as the premiums to identify suitable cover within your budget.
3. What is the difference between term life insurance and whole life insurance?
Term life insurance covers you for a specified period and generally pays out if you die during that term. Whole life insurance is designed to pay a death benefit whenever you die, provided the policy remains valid and its conditions are met. Whole life cover usually costs more than comparable term cover.
4. Do you need life insurance for a mortgage in the UK?
Life insurance is not generally a legal requirement for a UK residential mortgage. However, it may help your family repay the outstanding loan or manage mortgage payments if you die. The most suitable option depends on your mortgage balance, household finances and whether other people depend on your income.
5. Is over 50s life insurance worth it?
Over 50s life insurance may suit people who want guaranteed acceptance where offered and a fixed payout for loved ones, subject to the policy terms. However, premiums can add up over time, and the payout may be relatively small. Compare it with standard life insurance, whole life cover and other ways to meet your financial goals before deciding.