Latin America E-Commerce Logistics Market: A Region on the Cusp of a Digital Supply Chain Revolution
The Latin America e-commerce logistics market size increased from USD 33.6 Billion in 2025 to USD 37.7 Billion in 2026 and is projected to reach USD 77.8 Billion by 2034, at a CAGR of 9.48% during 2026-2034.
 Yadwender Kumar
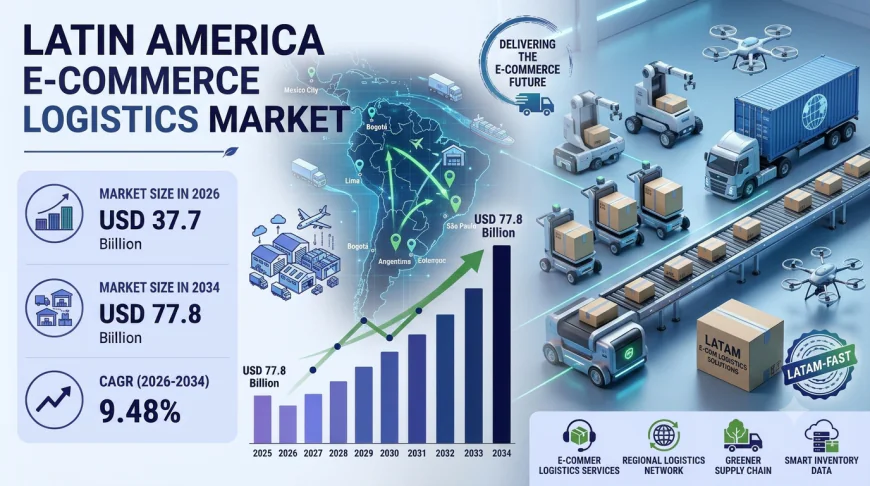
Latin American e-commerce logistics providers are navigating a landscape of remarkable transformation. For years, the region's logistics industry was characterised by fragmented delivery networks, underdeveloped warehousing infrastructure, and a heavy reliance on traditional distribution channels. But the digital revolution has arrived with force, reshaping how millions of consumers shop online and expect their purchases to be delivered. Online consumer spending is surging, logistics infrastructure investments are accelerating, and last-mile delivery networks are finally catching up with demand. The Latin America e-commerce logistics market is at the epicentre of this shift. Valued at USD 33.6 billion in 2025, the market is projected to reach USD 77.8 billion by 2034, growing at a compound annual rate of 9.48 per cent from 2026 to 2034. These figures reflect an industry entering a new era of logistical maturity.
What's Driving Growth of Latin America's E-Commerce Logistics Market?
Soaring online consumer activity is creating unprecedented demand for efficient logistics. The online environment in Latin America has seen an incredible shift, with online consumer behaviour growing at a considerable rate. This has been brought about by the common use of internet services and mobile phones, making online purchases more convenient for the masses. Online spending in Latin America stood at more than USD 71 billion in 2018, a 15 per cent growth compared to the preceding year. Chile was a case in point, with online business surpassing USD 5 billion, making it the country with the most per capita e-commerce transactions in the region. The COVID-19 pandemic further pushed this trend, with shoppers shifting to online platforms as a means of shopping because of lockdowns and social distancing. Latin America had a 37 per cent e-commerce growth in sales in 2020, reaching USD 85 billion. The growth of online consumers has thus put in place a critical need for effective and trusted e-commerce logistics solutions. Firms are now emphasising improving their supply chain capabilities in order to address customer demands for quicker and more reliable deliveries.
Heavy investments in logistics infrastructure are enabling the region to handle rising order volumes. Latin American countries have been working together to invest and enhance logistics infrastructure across the region in order to facilitate the growing e-commerce industry. Due to the understanding of the key role played by effective logistics in e-commerce, both governments and private companies have taken the lead in developing projects to improve transportation networks, warehouses, and delivery services. In Brazil, the e-commerce industry hit RUSD 196.1 billion in 2023, a 4.8 per cent growth from RUSD 187.89 billion in 2022. The increase is a sign of the significant role that strong logistics networks play in coping with the rising number of online orders. Firms such as MercadoLibre have gone a long way in enhancing their logistics. MercadoLibre posted a net revenue of USD 6.1 billion in the fourth quarter of 2024, with sales increasing by 8 per cent due to robust performance in Brazil. This success was partly due to growing logistics efficiency, particularly in Mexico. Additionally, the leading 20 logistics players in Latin America have posted a 25 per cent average revenue growth during the first quarter of 2024, demonstrating strong growth in the logistics industry.
Request Sample for PDF Report: https://www.imarcgroup.com/latin-america-e-commerce-logistics-market/requestsample
Rising digital payment adoption and smartphone penetration are democratising e-commerce access. The proliferation of affordable smartphones combined with expanding internet coverage across the region has enabled millions of first-time online shoppers to enter the digital marketplace. As digital payment methods become more trusted and widely accepted, consumers are increasingly comfortable making online purchases, which in turn drives demand for reliable logistics services. This shift is particularly pronounced among younger, mobile-native consumers who expect seamless end-to-end shopping experiences—from browsing to checkout to delivery.
Government initiatives to improve trade regulations are streamlining cross-border logistics. Recognising the economic potential of e-commerce, governments across Latin America have been implementing reforms to facilitate faster, cost-effective, and more efficient supply chain operations. These initiatives are reducing customs bottlenecks, improving cross-border trade flows, and creating a more favourable environment for logistics providers to operate across the region.
Brazil and Mexico are leading a regional e-commerce logistics boom. Together, these two nations concentrate the majority of logistics activity in Latin America. Brazil's e-commerce industry continues to expand at double-digit rates, while Mexico's gains have been driven by robust performance from major logistics players like MercadoLibre. The expansion of last-mile delivery networks and warehousing capacity in these two countries is setting the pace for the entire region.
Three Trends Reshaping the Industry
Online consumer spending is reaching new heights, reshaping logistics demand.
In 2018, online spending in Latin America exceeded USD 71 billion, growing 15 per cent over the previous year. By 2020, the pandemic had accelerated this trend dramatically, with e-commerce sales growing 37 per cent to reach USD 85 billion. Chile emerged as a standout market, surpassing USD 5 billion in online business and achieving the highest per capita e-commerce transactions in the region. Brazil's e-commerce industry reached RUSD 196.1 billion in 2023, a 4.8 per cent increase from the previous year. This sustained growth in online consumer activity is placing increasing pressure on logistics providers to scale their operations, improve delivery speed, and enhance reliability across the region.
Why it matters: The surge in online consumer activity fundamentally changes how logistics providers must structure their capacity planning and distribution networks.
Business implication: Logistics companies that fail to invest in scalable last-mile delivery networks and warehousing infrastructure risk losing market share to competitors who can meet rising demand.
Future impact: The trend toward digital-first shopping will accelerate as younger, mobile-native consumers become the dominant e-commerce demographic, driving even greater demand for efficient logistics solutions.
Logistics infrastructure investments are transforming the region's supply chain capabilities.
Latin American countries have been working together to invest and enhance logistics infrastructure across the region. Governments and private companies have taken the lead in developing projects to improve transportation networks, warehouses, and delivery services. In Brazil, the e-commerce industry's growth to RUSD 196.1 billion in 2023 reflects the significant role that strong logistics networks play in coping with the rising number of online orders. MercadoLibre has made substantial strides in enhancing its logistics operations, posting net revenue of USD 6.1 billion in the fourth quarter of 2024, with sales increasing by 8 per cent due to robust performance in Brazil. This success was partly driven by growing logistics efficiency, particularly in Mexico. The leading 20 logistics players in Latin America have posted a 25 per cent average revenue growth during the first quarter of 2024, demonstrating strong momentum across the industry.
Why it matters: Infrastructure investment is the backbone of e-commerce logistics growth, enabling faster deliveries and reducing operational bottlenecks.
Business implication: Logistics providers must continue to invest in warehousing, transportation networks, and technology to keep pace with rising order volumes and consumer expectations.
Future impact: The region's logistics infrastructure will become increasingly sophisticated, with greater integration of automation, data analytics, and real-time tracking capabilities.
Last-mile delivery and specialised logistics solutions are emerging as key differentiators.
As e-commerce volumes grow, the complexity of last-mile delivery in Latin America's diverse urban and rural landscapes is becoming a critical focus area. Companies like MercadoLibre have invested heavily in building out their own delivery networks to reduce dependency on third-party carriers and improve delivery times. The expansion of private air freight services—such as DHL Group's partnership with Brazilian startup Levu Air Cargo to launch a private air freight service—reflects the industry's push toward more reliable and specialised logistics solutions. This project aimed to provide a more reliable option than commercial passenger airlines and trucking, particularly for the domestic shipping of valuable goods in industries such as automotive and healthcare.
Why it matters: Last-mile delivery is often the most expensive and complex part of the logistics chain, and consumer expectations for speed and reliability are rising.
Business implication: Logistics providers must develop differentiated last-mile capabilities, including alternative delivery methods, route optimisation, and specialised handling for high-value goods.
Future impact: The last-mile delivery landscape will become increasingly fragmented, with specialised platforms and services catering to diverse product categories and delivery preferences.
What the Market Numbers Actually Tell Us
A market expanding from USD 33.6 billion to USD 77.8 billion over nine years suggests significantly greater commercial activity across transportation services, warehousing operations, last-mile delivery networks, and logistics technology providers. The 9.48 per cent compound annual growth rate signals robust, sustained expansion driven by structural shifts in consumer behaviour and ongoing investments in logistics infrastructure. The region's e-commerce logistics market is being propelled by the confluence of rising online consumer demand, enhanced digital payment adoption, and government initiatives to improve trade regulations. The dual reality of persistent infrastructure gaps alongside e-commerce's emergence as one of the region's most dynamic growth engines creates a complex but opportunity-rich environment for logistics providers.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of technology and underpenetrated markets. The integration of artificial intelligence and machine learning is enhancing supply chain efficiency by enabling predictive analytics, route optimisation, and demand forecasting based on consumer behaviour. Colombia has posted strong double-digit growth in e-commerce activity, driven by low-cost carrier expansion and new routes, while Chile has benefited from steady recovery in hospitality and air travel—both of which are driving logistics demand. Argentina, despite currency challenges and persistent inflation, represents the region's third-largest total addressable market at USD 8.9 billion. Countries such as Panama, Costa Rica, Colombia and Peru offer significant medium-term potential for logistics providers. The launch of innovative platforms—such as Yango Tech in Mexico, which provides patented technologies to e-commerce companies and physical stores in the food industry—demonstrates how technology is enabling traditional retailers to transition to online platforms while improving operational efficiency. For companies that can navigate the region's diverse regulatory environments, invest in mobile-first logistics solutions, and capture the growing demand for faster, more reliable deliveries, the pathway to sustained growth in Latin America's e-commerce logistics market is increasingly clear.