Germany Cyber Insurance Market Size, Share, Trends and Growth Report 2034
The Germany cyber insurance market size reached USD 759.6 Million in 2025. The market is projected to reach USD 3,706.7 Million by 2034, exhibiting a growth rate (CAGR) of 18.68% during 2026-2034.
 Yadwender Kumar
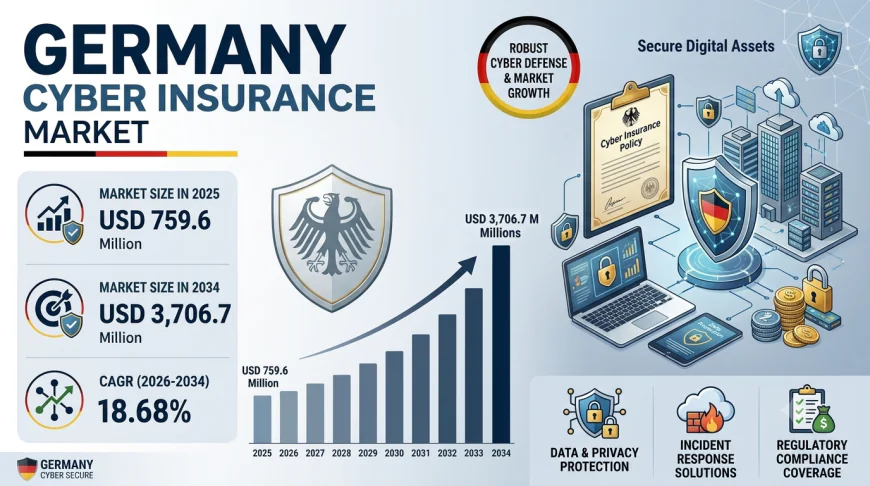
The Germany cyber insurance market is witnessing robust growth driven by the accelerating pace of digital transformation across industries, rising frequency and sophistication of cyber threats, and increasing regulatory pressure around data protection. The market size reached USD 759.6 Million in 2025 and is projected to reach USD 3,706.7 Million by 2034, exhibiting a compound annual growth rate (CAGR) of 18.68% during 2026-2034. Germany's heightened awareness of data protection, stringent regulations such as the GDPR, and the growing financial burden of cyberattacks—including recovery expenses, legal charges, regulatory fines, and loss of customer confidence—are creating strong demand for tailored cyber insurance solutions among both SMEs and large enterprises. This market is strategically important to Germany's economy as it directly supports business continuity, digital resilience, and risk management across sectors such as BFSI, healthcare, IT and telecom, retail, and manufacturing.
The Germany cyber insurance market is poised for sustained expansion, driven by the increasing frequency and sophistication of cyberthreats and the growing adoption of digital operations across sectors. With a projected CAGR of 18.68% through 2034, the market presents significant opportunities for established insurers and new entrants focused on innovative, industry-specific, and value-added cyber insurance solutions.
GERMANY CYBER INSURANCE MARKET SUMMARY
-
The Germany cyber insurance market encompasses a wide range of insurance products designed to protect businesses against financial losses arising from cyber incidents, including ransomware, phishing, data breaches, business interruption, social engineering attacks, cyber extortion, and reputational damage. The ecosystem includes insurance providers, reinsurers, cybersecurity firms, brokers, and end-use consumers.
-
Major segments identified in the market include component (solution and services), insurance type (packaged and stand-alone), organization size (small and medium enterprises and large enterprises), and end-use industry (BFSI, healthcare, IT and telecom, retail, and others).
-
The market is expanding as businesses adopt digital operations and face rising cyber risks across sectors. Heightened awareness of data protection and regulatory pressure are boosting demand for tailored insurance solutions, strengthening the Germany cyber insurance market share among both SMEs and large enterprises.
-
Insurers are increasingly offering value-added services such as cybersecurity risk assessments, breach response services, and regulatory compliance assistance, alongside traditional coverage.
PORTER'S FIVE FORCES ANALYSIS – GERMANY CYBER INSURANCE MARKET
The competitive dynamics of the Germany cyber insurance market can be analyzed using Porter's Five Forces framework.
Porter's Five Forces Analysis – Germany Cyber Insurance Market
-
Competitive Rivalry: High, with intense competition between global insurers, domestic providers, and specialized cyber insurance firms. Rivalry is driven by product innovation, pricing strategies, coverage breadth, and value-added services. Business implication: Insurers must differentiate through tailored industry-specific policies, advanced risk assessment capabilities, and strong customer relationships to capture market share.
-
Supplier Power (Reinsurers and Cybersecurity Firms): Moderate. Reinsurers and cybersecurity service providers have moderate bargaining power due to the specialized nature of cyber risk assessment and reinsurance capacity. However, the growing number of cybersecurity firms and alternative reinsurance options limits their power. Business implication: Insurers should develop strong partnerships with reinsurers and cybersecurity firms to ensure competitive pricing and comprehensive coverage offerings.
-
Buyer Power (Businesses and Enterprises): Increasing. Businesses have growing bargaining power due to the wide variety of cyber insurance options available, increasing awareness of cyber risks, and willingness to switch providers. Business implication: Insurers must focus on building brand loyalty, offering customized solutions, and providing value-added services such as risk assessments and breach response support to retain customers.
-
Threat of Substitutes: Moderate. Alternative risk management strategies such as self-insurance, captive insurance, and investments in cybersecurity infrastructure pose substitution threats. Business implication: Insurers must articulate clear return advantages and demonstrate the financial and operational benefits of cyber insurance relative to alternative risk mitigation strategies.
-
Threat of New Entrants: Moderate. High barriers to entry exist for large-scale insurers due to capital requirements, regulatory compliance, and track record, but lower barriers exist for niche and specialist cyber insurance providers. Germany's growing market attracts new domestic and international entrants. Business implication: Established players should build defensible positions through sector expertise, proprietary risk models, and strong broker relationships.
Competitive Rivalry – Moderate to High (Healthy)
-
Multi-tier competition spans global insurance leaders (Allianz, Munich Re, AXA), specialized cyber insurance providers (Coalition, Resilience), and regional German insurers – driving differentiation through product innovation, value-added services, and industry-specific coverage rather than destructive price competition.
-
Strategic developments such as Coalition's launch of Active Cyber Insurance in Denmark and Sweden (backed by Allianz) in May 2025, and Resilience's expansion into Germany and Austria with cyber insurance solutions up to €10M in May 2024, reflect active strategic repositioning that is strengthening the overall market ecosystem.
Request for Sample Report: https://www.imarcgroup.com/germany-cyber-insurance-market/requestsample
MARKET GROWTH DRIVERS
Several key factors are propelling the expansion of the Germany cyber insurance market. The increasing frequency and sophistication of cyberthreats serve as a powerful demand driver for cyber insurance. Businesses across Germany, from startups to international conglomerates, are increasingly recognizing the importance of insuring their digital infrastructures against ransomware, phishing, and data breaches. The growing financial burden of cyberattacks—encompassing recovery expenses, legal charges, regulatory fines, and loss of customer confidence—has made cyber insurance a vital component of risk management strategies. Moreover, the accelerating pace of digitization across industries like healthcare, finance, and manufacturing has resulted in heightened exposure to cyber threats, prompting numerous German businesses to arrange cyber insurance coverage to remain compliant with stringent data security legislation such as the GDPR and escape hefty fines.
The Germany cyber insurance market is also benefiting from expanding coverage options and innovation in cyber insurance products. German insurers are constantly improving their policy products to adapt to the increasing sophistication of cyber threats. Cyber insurance policies have expanded beyond data breach coverage to encompass business interruption expenses, social engineering attacks, cyber extortion, and reputational loss. Insurers are increasingly providing value-added services such as cybersecurity risk assessments, breach response services, and regulatory compliance assistance. Another trend is the development of policies tailored to various industry segments, with specialized coverage for healthcare, financial services, and retail. Insurers are also offering premium discounts to companies demonstrating high commitment to cybersecurity. Furthermore, the rising awareness of digital security's importance in protecting business continuity is creating a new segment, with organizations increasingly relying on interconnected networks and expanding their digital footprint.
GERMANY CYBER INSURANCE MARKET SEGMENTATION
Segmentation analysis provides a detailed view of the Germany cyber insurance market by category:
-
Component Insights: Solution, Services.
-
Insurance Type Insights: Packaged, Stand-alone.
-
Organization Size Insights: Small and Medium Enterprises, Large Enterprises.
-
End-Use Industry Insights: BFSI, Healthcare, IT and Telecom, Retail, Others.
-
Regional Insights: Western Germany, Southern Germany, Eastern Germany, Northern Germany.
COMPETITIVE LANDSCAPE
The Germany cyber insurance market features a moderately consolidated competitive landscape, with multi-tier competition spanning global insurance leaders, specialized cyber insurance providers, and regional German insurers. Key companies operating in the market include:
-
Allianz
-
Munich Re
-
AXA
-
Coalition
-
Resilience
-
Chubb
-
Zurich Insurance Group
-
Hiscox
Strategic developments are shaping the competitive arena, notably Coalition's launch of Active Cyber Insurance in Denmark and Sweden (backed by Allianz) in May 2025, combining insurance coverage with cybersecurity tools, and Resilience's expansion into Germany and Austria in May 2024, offering cyber insurance solutions with limits up to €10M.
REGIONAL ANALYSIS
Regional dynamics within the Germany cyber insurance market are shaped by varying levels of industrial concentration, digital adoption, and regulatory activity.
-
Western Germany emerges as a critical demand center, driven by a high concentration of industrial enterprises, financial services, and technology companies requiring specialized cyber insurance solutions.
-
Southern Germany benefits from a strong manufacturing base, automotive industry, and growing technology sector, contributing to significant cyber insurance consumption.
-
Eastern Germany, though smaller in market share, is seeing growth from increasing digitalization and the expansion of IT and telecom sectors.
-
Northern Germany has strong logistics, healthcare, and retail sectors, contributing to both SME and large enterprise cyber insurance demand.
RECENT INDUSTRY DEVELOPMENTS
May 2025: Coalition launched Active Cyber Insurance in Denmark and Sweden, backed by Allianz. This innovative offering combined insurance coverage with cybersecurity tools, helping businesses mitigate digital risks. The move significantly impacted the Nordic cyber insurance market by enhancing risk management capabilities for companies.
May 2024: Resilience expanded its operations to Germany and Austria, offering cyber insurance solutions with limits up to €10M. The move strengthened its presence in Europe, addressing growing cyber risks. This expansion provided businesses with enhanced risk management and loss prevention capabilities.
2026: The Germany cyber insurance market continues to expand, with increasing adoption of tailored cyber insurance solutions among SMEs and large enterprises.
2025: German insurers accelerated the development of industry-specific cyber insurance policies, with specialized coverage for healthcare, financial services, and retail sectors.
2024: The implementation of stringent data security legislation such as the GDPR prompted numerous German businesses to arrange cyber insurance coverage to remain compliant and escape hefty fines.
KEY ASPECTS REQUIRED FOR THE GERMANY CYBER INSURANCE MARKET
-
Market Performance: USD 759.6 Million in 2025, with a projected trajectory to USD 3,706.7 Million by 2034.
-
Market Outlook: An 18.68% CAGR through 2034 indicates robust growth across solution, services, packaged, and stand-alone insurance segments, driven by digital transformation and rising cyber risks.
-
Growth Drivers: Increasing frequency and sophistication of cyberthreats; accelerating pace of digitization across industries; stringent data protection regulations such as GDPR; growing financial burden of cyberattacks; expanding coverage options and innovation in cyber insurance products; rising awareness of digital security's importance in protecting business continuity.
-
Competitive Landscape: A distinctive multi-tier structure with global insurance leaders, specialized cyber insurance providers, and regional German insurers, with moderate concentration at the national level.
-
Value Chain Analysis: From risk assessment and underwriting through policy issuance, premium collection, claims processing, and value-added services to end consumers.
-
Industry Trends: Development of industry-specific cyber insurance policies; integration of cybersecurity tools with insurance coverage; premium discounts for high cybersecurity commitment; expansion of value-added services such as risk assessments and breach response; growth of packaged and stand-alone insurance options.
-
Strategic Recommendations: Focus on industry-specific product innovation; develop advanced risk assessment capabilities; build strong relationships with reinsurers and cybersecurity firms; offer value-added services to differentiate; expand distribution networks and broker partnerships; invest in digital marketing and customer engagement.
Note: If you need any specific information that is not covered currently within the scope of the report, we will provide the same as a part of customization.
Request Customization: https://www.imarcgroup.com/request?type=report&id=41114&flag=E
Write this before about us –
-
Report Format, Delivery, and Customization Details
-
Report Format Mode: PPT, PDF, and Excel
-
Report Delivery Mode: Online Delivery, Physical Delivery
-
Report Delivery Time: Report Delivered Over Email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
-
Report Confirmation Mode: Yes via Email
-
Report Customization Mode: Yes via Email / Call
-
Report Table of Content: Yes
-
Report List of Figures: Yes
-
Report Methodology Mode: Yes
-
Request For Sample Report: Yes