Europe's Welding Consumables Market: Quiet Backbone of Industrial Resilience
Europe's welding consumables market is set to grow from USD 3.2B to USD 4.0B by 2034. Explore automation, sustainability, and emerging opportunities.
 Ranjeet Sharma
Introduction
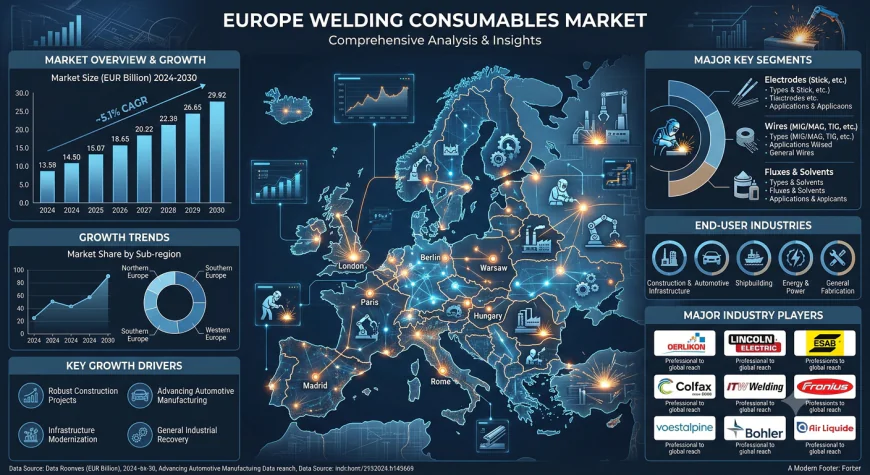
European manufacturing executives are navigating a paradox of resilience and reinvention. The continent's automotive, construction, and energy sectors continue to demand vast quantities of welded steel and aluminium, yet a critical shortage of certified welders threatens to constrain output at the very moment infrastructure spending is accelerating. The welding consumables market—encompassing electrodes, wires, fluxes, and filler materials—forms the essential, if unglamorous, backbone of this industrial ecosystem. The Europe welding consumables market reflects this steady, indispensable role. Valued at USD 3.2 billion in 2025, the market is projected to reach USD 4.0 billion by 2034, growing at a compound annual growth rate of 2.43 per cent from 2026 to 2034. These figures signal a mature market where value growth comes from specialisation, automation compatibility, and regulatory-driven product innovation rather than explosive volume expansion.
What's Driving Growth of Europe's Welding Consumables Market?
Construction and infrastructure spending is anchoring baseline demand. The European construction industry, valued at over €1.5 trillion, relies heavily on welding consumables for bridges, pipelines, and structural steel fabrication . Stick electrodes remain particularly critical for small-scale fabricators and maintenance applications, costing 20-30 per cent less than advanced alternatives while offering reliability for critical joints . Government-backed renovation initiatives, including the EU's goal to retrofit 35 million buildings by 2030, sustain steady consumption of welding materials across the continent .
The automotive sector's lightweighting trend is reshaping product requirements. Manufacturers are increasingly specifying high-strength steels and aluminium alloys to reduce vehicle weight and improve fuel efficiency. This shift demands specialised welding wires and electrodes capable of joining dissimilar materials while maintaining structural integrity . Flux-cored wires, offering deposition rates up to 50 per cent higher than stick electrodes, are gaining traction in automated automotive welding systems where productivity and consistency are paramount .
Energy transition projects are creating new demand categories. Offshore wind farms, hydrogen infrastructure, and grid modernisation programmes require durable, high-quality welds capable of withstanding extreme conditions. The energy segment is projected to register the highest growth rate, driven by Europe's accelerating shift to renewable sources . Welding consumables for turbine foundations, transmission structures, and pipeline networks represent a premium, specification-driven market segment.
Labour scarcity is paradoxically driving value growth. Europe faces a projected shortage of 400,000 certified welders by 2030, with annual certifications covering barely 70 per cent of retirements . This workforce constraint is accelerating automation adoption, which in turn demands consumables specifically engineered for robotic and automated welding systems—products that command higher margins and more consistent demand than their manual counterparts .
Three Trends Reshaping the Industry
Flux-cored wires are capturing share from traditional stick electrodes.
Flux-cored wires are estimated to register a CAGR of 7.1 per cent, significantly outpacing the broader market . Their superior performance in high-deposition applications, particularly in shipbuilding and heavy industry, makes them indispensable for automated welding systems. According to the International Institute of Welding, flux-cored wires offer deposition rates up to 50 per cent higher than stick electrodes, enhancing productivity while minimising spatter and improving bead appearance .
Why it matters: Productivity gains directly address Europe's skilled labour shortage.
Business implication: Manufacturers must expand flux-cored wire production capacity and develop formulations compatible with robotic welding cells.
Future impact: As automation penetrates mid-tier fabricators, flux-cored wires will become the default consumable for high-volume applications.
Sustainability regulations are driving consumable reformulation.
The EU's REACH framework imposes stringent restrictions on hazardous substances in welding consumables, including fume emissions and hexavalent chromium compounds. Manufacturers are responding with low-fume electrodes, chromium-free alternatives, and recyclable packaging . Environmental compliance is becoming a competitive differentiator, with suppliers investing in green technologies to align with the European Green Deal's climate neutrality objectives .
Why it matters: Regulatory compliance is no longer optional but a prerequisite for market access.
Business implication: Producers must invest in R&D for low-emission formulations or risk exclusion from regulated procurement.
Future impact: Sustainability credentials will become a primary selection criterion alongside technical performance.
Ultrasonic and laser welding are opening new consumable categories.
Ultrasonic welding is predicted to exhibit a CAGR of 9.5 per cent, driven by applications in lightweight material joining, particularly for electric vehicle components . This technique requires specialised filler materials and surface preparation consumables distinct from traditional arc welding. Meanwhile, laser welding systems, while not consumable-intensive in the traditional sense, demand precision-engineered filler wires for applications requiring metallurgical integrity in narrow heat-affected zones .
Why it matters: New welding techniques create demand for specialised consumables that command premium pricing.
Business implication: Consumable manufacturers must develop products tailored to emerging welding processes rather than relying solely on arc welding formulations.
Future impact: The consumables market will fragment into process-specific product families, rewarding suppliers with broad technical portfolios.
What the Market Numbers Actually Tell Us
A market expanding from USD 3.2 billion to USD 4.0 billion over nine years suggests steady commercial activity across consumable manufacturers, distributors, and end-user industries. The 2.43 per cent compound annual growth rate signals a mature market where growth is driven by value-added products rather than volume expansion. Arc welding commands the dominant share of welding techniques at over 65 per cent, reflecting its versatility across automotive, construction, and heavy machinery applications . Germany leads the regional market, underpinned by its advanced manufacturing base, automotive sector, and strong supplier ecosystem . The construction segment accounts for the largest end-use share at 36.3 per cent, anchored by Europe's substantial infrastructure pipeline . For investors and industry participants, the opportunity lies in high-performance consumables for automated systems, specialised alloys for energy transition projects, and regulatory-compliant formulations that align with Europe's sustainability mandates.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of automation and material innovation. Flux-cored wires for robotic welding represent the fastest-growing product category, driven by labour scarcity and productivity imperatives. Consumables for aluminium and dissimilar-metal joining are expanding as electric vehicle production scales across European gigafactories . The energy segment, growing at 7.7 per cent CAGR, offers premium opportunities in offshore wind and hydrogen infrastructure . Germany's dominance in welding consumables is reinforced by its world-class R&D ecosystem and the presence of leading global suppliers including Lincoln Electric, ESAB, and voestalpine Böhler Welding . Companies that can deliver verified low-emission consumables, engineer products for automated processes, and support customers through technical service and training are well-positioned to capture value in this evolving market.