Can Europe's Paper Packaging Industry Win the War on Plastic?
Europe's paper packaging market is set to grow from USD 56.4B to USD 76.8B by 2034. Explore regulatory drivers, flexible packaging, and opportunities.
 Ranjeet Sharma
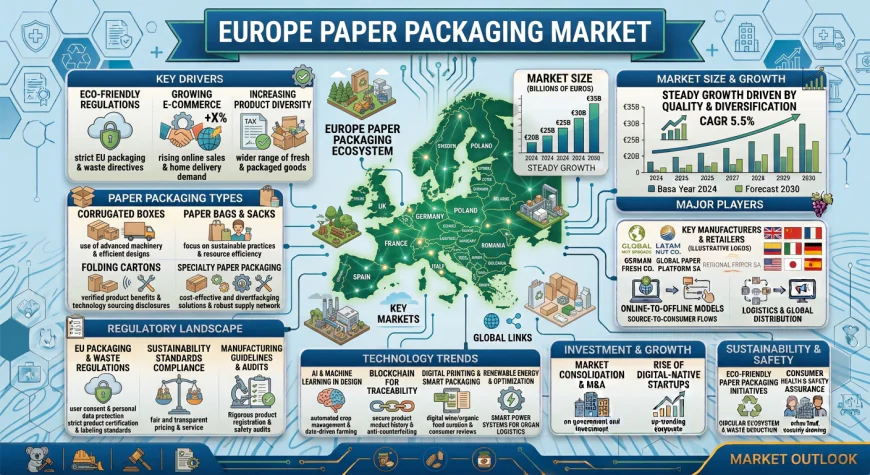
European brand owners are caught between two powerful forces. On one side, consumers are demanding an end to plastic waste, with younger demographics particularly willing to switch to brands that use sustainable packaging. On the other, the practical challenges of replacing plastic—maintaining barrier properties, extending shelf life, and managing costs—remain formidable. The regulatory environment has tipped decisively in favour of paper. The EU's Packaging and Packaging Waste Regulation now requires all packaging to be recyclable by 2030, and plastic taxes are making conventional materials increasingly unattractive. The Europe paper packaging market stands at the centre of this transformation. Valued at USD 56.4 billion in 2025, the market is projected to reach USD 76.8 billion by 2034, growing at a compound annual growth rate of 3.38 per cent from 2026 to 2034. These figures reflect an industry benefiting from regulatory tailwinds and shifting consumer preferences.
What's Driving Growth of Europe's Paper Packaging Market?
Consumer environmental consciousness is driving a decisive shift away from plastic. A growing consumer awareness of the environmental impact of plastic waste has created demand for products packaged in environmentally responsible materials. Paper packaging is biodegradable and recyclable, making it an ideal alternative. Younger demographics are leading this shift, showing the greatest willingness to choose brands that use sustainable packaging.
Stringent government regulations are mandating recyclability and penalising plastic. The European Union's Circular Economy Action Plan is focused on greater recyclability and reduced waste, while plastic taxes are making conventional packaging less attractive. Governments are also providing subsidies and grants to businesses that implement sustainable packaging solutions, creating financial incentives alongside regulatory requirements.
Advancements in packaging technology are expanding paper's application range. Innovations in material science and engineering have significantly enhanced the strength, durability, and versatility of paper packaging. Modern paper-based materials can now offer comparable protection to plastic, with improved barrier properties such as resistance to moisture and grease. This has expanded functionality, allowing paper to replace plastic in applications that previously required contamination protection.
E-commerce growth is generating demand for rugged, lightweight packaging. The continued expansion of online retail is driving demand for corrugated boxes and paper-based protective packaging. As more consumers shop online, the need for durable yet sustainable shipping materials grows correspondingly, reinforcing paper packaging's position as the preferred solution for fulfilment operations.
Three Trends Reshaping the Industry
Flexible paper packaging is gaining ground on traditional formats.
The gradual movement toward flexible paper packaging across Europe has increased demand for versatile, lightweight, and budget-friendly alternatives. A joint study by DHBW and Heidelberg found that paper-based packaging solutions will play an increasingly dominant role in Europe by 2030, driven by new legal requirements and changing consumer behaviour. The study describes this not as a short-term trend but as a profound change in how products are packaged and presented.
Why it matters: Flexible paper offers a viable substitute for plastic in applications where rigid packaging was previously the only option.
Business implication: Manufacturers must invest in flexible paper converting capabilities or risk losing market share to more agile competitors.
Future impact: The trend toward paperisation will accelerate as technology improves and costs decline across multiple product categories.
Customisation and brand experience are becoming key differentiators.
A growing number of brands are offering custom paper designs to create an overall brand experience for consumers. Packaging is no longer merely functional—it is a marketing tool that communicates sustainability credentials and brand values. This shift is particularly pronounced in premium food, beverage, and personal care segments, where distinctive packaging reinforces brand positioning and justifies premium pricing.
Why it matters: Customisation creates opportunities for higher-margin products and deeper customer relationships.
Business implication: Paper packaging producers must develop design capabilities and digital printing technologies to meet brand demands.
Future impact: The intersection of sustainability and premium design will drive innovation in printing, finishing, and structural packaging.
Recycling technology innovation is creating new material streams.
Innovation in recycling technologies to manufacture new and improved paper packaging solutions is providing significant opportunities. Advances in sorting, de-inking, and fibre recovery are improving the quality and performance of recycled paper, making it suitable for a broader range of applications. Uncoated recycled paper now holds the largest share of the market, driven by demand for environmentally friendly packaging and improvements in recycled material quality.
Why it matters: Recycled content is becoming a regulatory requirement and a consumer expectation.
Business implication: Manufacturers must secure access to high-quality recycled fibre streams and invest in processing capabilities.
Future impact: Closed-loop recycling systems will become standard, reducing dependence on virgin fibre and improving lifecycle economics.
What the Market Numbers Actually Tell Us
A market expanding from USD 56.4 billion to USD 76.8 billion over nine years suggests significantly greater commercial activity across paper manufacturers, converters, brand owners, and recycling infrastructure operators. The 3.38 per cent compound annual growth rate signals steady, sustainable expansion driven by regulatory mandates and consumer preferences. Folding boxes and cases represent the largest product segment, benefiting from e-commerce growth and demand for sustainable packaging. Uncoated recycled holds the largest grade share, reflecting the shift toward recycled content. Primary packaging accounts for the largest packaging level share, while food represents the dominant end-use industry. Germany leads the regional market, supported by its robust manufacturing base, stringent environmental regulations, and concentration of major packaging companies. For investors, the trajectory indicates that paper packaging is becoming the default choice for sustainable packaging across Europe, with growth driven by structural regulatory and consumer trends.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of innovation and sustainability. Smurfit Kappa announced a €54 million investment in 2024 to expand its Bag-in-Box plant in Ibi, Spain, enhancing production capacity for sustainable packaging with reduced plastic use. Mondi collaborated with Cemex to introduce water-soluble cement bags to the Balearic Islands, eliminating packaging waste by allowing the bags to dissolve during mixing. These examples illustrate how innovation is creating new applications for paper packaging in traditionally plastic-dominant categories. Companies that can navigate the regulatory landscape, invest in barrier technology, and develop customisation capabilities are well-positioned to capture value in this evolving market. Key players including Smurfit Westrock, DS Smith, Mondi Group, Metsa Board, and Stora Enso are leading the transition through strategic investments and product innovation.