Polyethylene Terephthalate Market Global Growth Outlook & Industry Forecast, 2026-2034
bis(2-hydroxyethyl) terephthalate (BHET)—are enabling the recovery of difficult-to-recycle PET waste from textiles and complex packaging, yielding virgin-quality, food-grade resins.
 Kapil Kazade
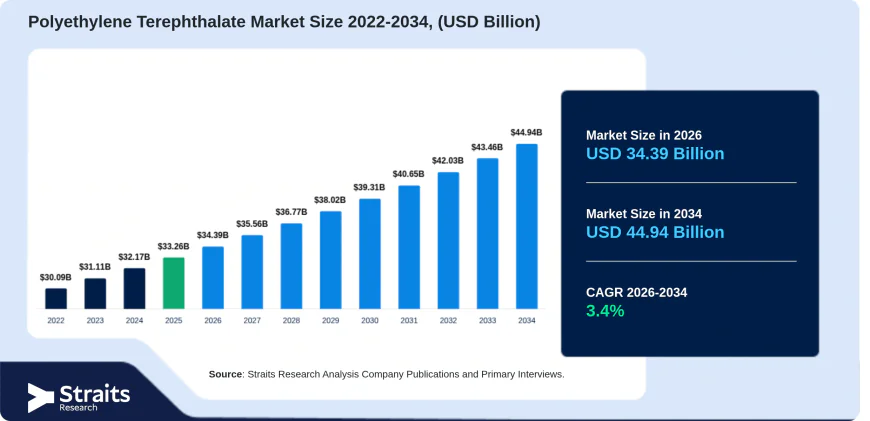
The global polyethylene terephthalate market was valued at USD 33.26 billion in 2025 and is projected to expand from USD 34.39 billion in 2026 to USD 44.94 billion by 2034, growing at a CAGR of 3.4%. Growth is driven by expanding beverage packaging demand, polyester fiber manufacturing, and breakthroughs in chemical recycling and bio-based feedstocks.
Global Polyethylene Terephthalate Market Overview & Strategic Growth Outlook (2026–2034)
The global polyethylene terephthalate (PET) market is positioned for steady expansion, driven by its indispensability across food and beverage packaging, synthetic textile manufacturing, and specialized industrial applications As a lightweight, highly durable, transparent, and 100% recyclable thermoplastic polymer, PET remains the preferred packaging resin worldwide Valued at USD 33.26 billion in 2025, the market expanded to USD 34.39 billion in 2026 and is projected to reach USD 44.94 billion by 2034, registering a compound annual growth rate (CAGR) of 3.4% during the forecast period.
Key Market Drivers Fueling Global Consumption
The primary vector propelling market growth is the surging global demand for packaged beverages, bottled drinking water, and convenience foods. PET offers exceptional barrier properties, clarity, and shatter resistance, making it uniquely suited for carbonated soft drinks, bottled water, juices, and thermoformed food trays. A critical driver is the expansion of global PET resin production capacity and polyester fiber manufacturing. Key industry producers, such as Indorama Ventures, continue to expand their annual production capacity for polyester staple fibers and filament yarns to satisfy booming downstream demand in textiles and rigid packaging formats. Furthermore, PET’s lightweight nature significantly optimizes logistics costs and carbon footprints for global beverage distributors compared to glass or metal alternatives.
Emerging Industry Trends: Chemical Recycling and Bio-Based Feedstocks
The PET industry is undergoing a structural transition toward circular economy models, driven by escalating environmental legislation and corporate sustainability commitments. Two prominent trends are reshaping the competitive landscape
- Expansion of Chemical Recycling: To overcome the quality degradation inherent in mechanical recycling, major industry participants are investing heavily in advanced chemical recycling technologies such as glycolysis and depolymerization. Initiatives led by organizations like PETCORE Europe—including dedicated task forces focusing on converting post-consumer PET into bis(2-hydroxyethyl) terephthalate (BHET)—are enabling the recovery of difficult-to-recycle PET waste from textiles and complex packaging, yielding virgin-quality, food-grade resins.
- Adoption of Bio-Based PET Feedstocks: In response to decarbonization mandates, manufacturers are increasing the integration of bio-based feedstocks derived from renewable agricultural resources. Bio-PET replaces traditional fossil-based raw materials, reducing cradle-to-gate carbon footprints while preserving identical thermal and mechanical performance.
Market Restraints & Structural Challenges
Despite strong underlying demand, the market faces significant headwinds from feedstock price volatility and regulatory pressures. The production of PET relies directly on purified terephthalic acid (PTA) and monoethylene glycol (MEG). Price fluctuations in crude oil and petrochemical feedstocks directly erode profit margins for resin synthesizers. Additionally, PET polymerization is an energy-intensive process; escalating energy costs globally pose cost-competitiveness challenges for processing facilities.
Furthermore, stringent regulatory frameworks—such as the EU Packaging and Packaging Waste Regulation (PPWR) and Extended Producer Responsibility (EPR) mandates in developing markets—impose strict compliance timelines. Achieving consistent, food-grade recycled content (rPET) remains technically complex due to recycling quality gaps and stringent European Food Safety Authority (EFSA) verification guidelines.
Segmentation Highlights: Packaging and Bottled Water Domination
From an application perspective, the Packaging segment dominated the global PET market, commanding a 72.4% revenue share in 2025, and is projected to grow at the fastest CAGR of 6.1% through 2034. Within packaging formats, Bottled Water leads with a 27.8% market share in 2025 and is anticipated to achieve the highest CAGR of 6.4% from 2026 to 2034, fueled by urbanization, rising health awareness, and expanding municipal beverage distribution challenges.
Regional Landscape: Asia-Pacific Leadership & North American Momentum
Asia-Pacific dominated the global market in 2025 with a 42.5% share, propelled by massive production hubs in China and India, alongside strong domestic consumption of packaged goods and textiles. Regulatory measures, such as India’s EPR framework setting an 80% recycling target for rigid plastic packaging from 2027–28, are reshaping regional operational models. Conversely, North America represents the fastest-growing regional market, expanding at an impressive CAGR of 6.6% between 2026 and 2034, driven by rapid advancements in high-barrier medical packaging and premium beverage applications.
Access the Detailed Report=https://straitsresearch.com/report/polyethylene-terephthalate-market