Europe Mental Health Market Size, Share, Trends and Outlook 2034
The Europe Mental Health Market size was valued at USD 115.51 Billion in 2025 to reach USD 141.79 Billion by 2034 at a CAGR of 2.3% during 2026-2034
 Yadwender Kumar
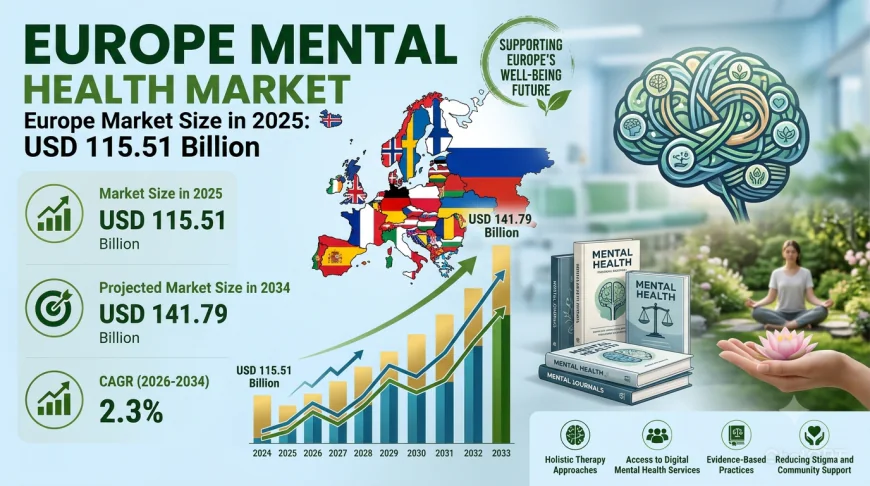
European healthcare leaders are navigating one of the most meaningful shifts in the continent’s recent history. For years, psychological care sat at the margins of health policy, treated as a secondary concern to physical medicine. That perception has changed decisively. Governments are funding mental health as a core priority, employers are building wellbeing into their workforce strategies, and citizens are seeking professional support with far greater confidence than before. The Europe Mental Health Market is at the centre of this transformation. Valued at USD 115.51 billion in 2025, the market is projected to reach USD 141.79 billion by 2034, growing at a compound annual rate of 2.3 per cent from 2026 to 2034. These figures reflect a mature, deeply institutionalised sector that continues to expand steadily and to modernise its care models.
What’s Driving Growth of Europe’s Mental Health Market?
Substantial government investment is modernising the care landscape. The European Commission has allocated EUR 1.23 billion to support mental health initiatives across member states, funding research, workforce training, digital solutions and the sharing of best practice. National budgets are reinforcing this momentum. The United Kingdom, for instance, has earmarked approximately £15.6 billion for mental health spending in the 2025–26 fiscal year. Together, these commitments are enabling the upgrading of psychiatric facilities and the expansion of community-based services.
Rising awareness and destigmatisation are widening the patient pool. According to the Eurobarometer survey, 89 per cent of Europeans believe that mental health deserves the same attention as physical health. National campaigns, open media discussion and anti-stigma programmes backed by the European Commission are encouraging more people to come forward. Primary care physicians are also becoming more proficient at identifying mood disorders, creating earlier and more effective entry points into treatment.
Digital innovation is extending the reach of therapy. Digital therapeutics, telepsychiatry platforms and AI-driven diagnostic tools are taking evidence-based care beyond the clinic. Investor confidence is strong: HelloBetter has secured EUR 31 million in total funding to expand its digital therapy offerings, while Unmind raised EUR 30.6 million in July 2025 to scale its workplace mental health platform. Germany’s Digital Health Applications framework, which allows approved apps to be prescribed and reimbursed through statutory health insurance, has given the whole region a model to follow.
Employers are making psychological wellbeing a business priority. European organisations are rolling out employee assistance programmes, stress management workshops and virtual counselling as part of their wellness strategies. They increasingly recognise that psychological health directly influences productivity, absenteeism and organisational performance. Health insurers and employers are also collaborating on preventive digital tools aimed at reducing burnout and depression among working-age populations.
Request Sample For PDF Report: https://www.imarcgroup.com/europe-mental-health-market/requestsample
Three Trends Reshaping the Industry
Digital therapeutics are becoming part of mainstream treatment.
Germany has emerged as a pioneer, with mental health-focused applications making up a substantial portion of all approved digital therapeutics under its regulatory framework. These platforms draw on cognitive behavioural therapy protocols, mood tracking and AI-driven behavioural analytics to deliver personalised interventions. Healthcare providers are increasingly prescribing them alongside traditional treatments, which improves patient engagement and extends therapeutic reach beyond clinical settings. In February 2025, German digital mental health company Neurocare received EUR 19.3 million from Impact Expansion and TVM Capital Healthcare to support the growth of its remote therapy services.
Why it matters: Reimbursable digital tools are turning pilot projects into scalable, commercially viable care pathways.
Business implication: Providers, insurers and technology developers that build clinically validated digital offerings can secure a place within national reimbursement systems and prescribing habits.
Future impact: Digital and conventional care will increasingly operate as one integrated model, with app-based support complementing therapy sessions and medication management.
Workplace mental health programmes are scaling across corporate Europe.
Employee assistance programmes, virtual counselling and preventive digital tools are now standard components of many corporate wellness strategies. Adults aged 18 to 64 account for 53.56 per cent of the market, reflecting how strongly workplace stress, burnout and mood conditions drive demand among working-age populations. Expanded insurance coverage and employer-sponsored support are making professional help easier to reach for this group.
Why it matters: Working adults are the largest user group, and employers are now a major channel for reaching them.
Business implication: Service providers and digital platforms can build B2B partnerships with employers and insurers, moving beyond direct-to-consumer models into recurring, contract-based revenue.
Future impact: Mental health benefits are likely to become a core element of employer value propositions, competing alongside pay and flexibility in attracting talent.
Telepsychiatry and virtual care are widening access.
Telemedicine has become an integral part of mental health delivery across the continent. The National Health Service in the United Kingdom has embedded telehealth capabilities into its mental health services, accelerating the use of virtual wards for chronic condition management. Real-time consultations and continuous monitoring are proving particularly effective for follow-up appointments and medication management, improving continuity of treatment for patients in remote and underserved areas.
Why it matters: Virtual delivery lets health systems serve more patients without proportionate increases in physical capacity.
Business implication: Providers can extend their geographic reach, optimise clinician time and offer flexible care formats that fit patients’ schedules.
Future impact: Hybrid models that combine inpatient, day-clinic, outpatient and virtual services under unified frameworks will shape the next phase of service design.
What the Market Numbers Actually Tell Us
A market growing from USD 115.51 billion to USD 141.79 billion adds roughly USD 26.3 billion in annual value over the forecast horizon, an increase of around 23 per cent from the 2025 base. The 2.3 per cent compound annual growth rate points to a large, established sector expanding on stable, institutional foundations rather than on short-term momentum. The segmentation reinforces this picture. Depression and anxiety account for 52.33 per cent of the market, inpatient hospital treatment services hold 43.52 per cent, and adults represent 53.56 per cent. Germany, with a 25 per cent share, is the largest national market. Such concentration shows where demand is deepest today, and where well-targeted innovation in earlier intervention, digital delivery and integrated care can generate the most value.
Where New Opportunities Are Emerging
The most compelling opportunities lie where proven demand meets expanding access. Approximately 54 per cent of Europeans with mental health problems have not yet received professional assistance, which signals a substantial pool of untapped demand for providers that can reach people early and conveniently. Digital therapy platforms, telepsychiatry services and workplace programmes are well placed to serve this population, supported by regulatory frameworks such as Germany’s reimbursement pathway for digital health applications. Germany, France, the United Kingdom, Italy and Spain each offer distinct entry points, from statutory insurance-funded care to a national health service embedding virtual capabilities. Meanwhile, flexible models that link inpatient, day-clinic and community care are opening room for new partnerships between hospitals, technology developers and insurers. For organisations that can combine clinical credibility with digital convenience, the pathway to sustained growth in the Europe Mental Health Market is increasingly clear.