Europe Dairy Market: Trends Reshaping the Industry
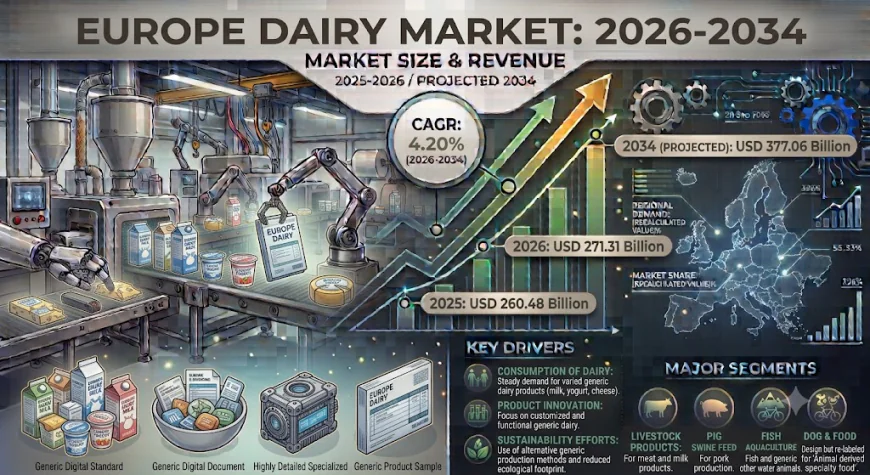
Europe dairy market increased from USD 260.48 Billion in 2025 to USD 271.31 Billion in 2026 and is projected to reach USD 377.06 Billion by 2034, growing at a CAGR of 4.20% during the forecast period.
 Team Imarc
There is a telling moment in the April 2025 announcement of the proposed merger between Arla Foods and DMK Group, two of Europe's largest dairy cooperatives, collectively representing tens of thousands of farmer-owners across Denmark, Sweden, Germany, and the United Kingdom. That a merger of this scale, combining Arla's pan-European consumer brand reach with DMK's commanding position in German liquid milk and butter processing, is being framed not primarily as a cost-reduction exercise but as a platform for joint investment in functional dairy innovation, sustainability transformation, and international ingredient export capacity reveals something important about where the competitive logic of European dairy is heading. Scale is no longer sufficient as a strategy. What matters increasingly is what scale enables, in R&D investment, in sustainability certification, and in the market access required to serve a global demand for European dairy ingredients that is growing faster than domestic consumption.
The market context for that ambition is substantial. The Europe dairy market increased from USD 260.48 Billion in 2025 to USD 271.31 Billion in 2026 and is projected to reach USD 377.06 Billion by 2034, growing at a CAGR of 4.20% during the forecast period. Adding USD 116.58 Billion in annual market value over nine years, across one of the world's most established, most competitive, and most culturally embedded food categories, reflects a market that is simultaneously defending its domestic consumption base through functional innovation, expanding its international ingredient export revenue through whey protein and milk powder shipments to Asia Pacific, and transforming its environmental credentials through sustainability investment that is as commercially motivated as it is ethically driven.
What's Driving Growth in the Europe Dairy Market?
Liquid milk's commanding 26.0% product type dominance reflects the category's foundational role in European household nutrition, anchored by Germany and France's well-established distribution networks delivering both fresh and UHT varieties through supermarkets, convenience stores, and direct delivery infrastructure that has been built and refined over decades. Germany's production of over 33 million tonnes of raw milk annually, within a total EU output estimated at approximately 155 million tonnes per year, provides the physical supply base that sustains the entire continental liquid milk category at a cost and quality structure that imported alternatives cannot approach.
Whey protein's exceptional 6.2% CAGR as the fastest-growing sub-segment reflects the commercialisation of a material that was historically treated as a processing by-product into one of the most commercially valuable dairy ingredients in global trade. European whey protein is flowing in expanding volumes to Asia Pacific infant formula manufacturers, Middle Eastern sports nutrition markets, and global food fortification applications, each of which is growing independently and compounding whey's demand trajectory in ways that make it the single most attractive investment frontier within the European dairy ingredient complex.
Germany's 18.0% country share anchoring continental market depth is reinforced by advanced dairy processing infrastructure that enables value extraction at every stage of the milk processing chain, from fresh consumer dairy through UHT production, speciality cheese manufacture, and high-specification ingredient production for pharmaceutical, infant nutrition, and sports nutrition applications. The country's multiple large dairy cooperatives, including DMK Group as Germany's largest, create a competitive but cooperative industry structure that sustains investment in technology and product development at a scale that fragmented producer structures cannot replicate.
Modern retail commanding over 78% of European dairy distribution in 2025 provides the channel infrastructure that converts European dairy's processing sophistication into consumer market value, with e-commerce dairy sales growing at approximately 9.4% CAGR through subscription fresh dairy delivery and online grocery platforms that are progressively displacing traditional store-based purchasing across the United Kingdom, Germany, and the Nordics.
Per-capita dairy consumption averaging 67 kilograms across European consumers, among the highest globally, provides the demand foundation that no market entry investment could create from scratch, and that the combination of culinary tradition, nutritional awareness, and affordable retail availability sustains with a consistency that discretionary food categories cannot approach at comparable scale.
Three Trends Reshaping the Industry
Cooperative consolidation building the institutional scale for next-decade innovation and export investment
The Arla Foods and DMK Group merger announcement in April 2025, which would create Europe's largest dairy cooperative by farmer-owner count and by combined processing volume, is the most commercially significant expression of a consolidation logic that is reshaping the entire competitive architecture of European dairy. The strategic rationale extends well beyond cost synergies: the combined entity would possess the R&D budget, the ingredient processing capability, the international distribution relationships, and the sustainability certification infrastructure to compete credibly against US and New Zealand dairy multinationals in the premium ingredient export markets that are growing fastest globally. Lactalis's concurrent acquisition of Bayerische Milchindustrie eG's fresh dairy operations in Bavaria, including production in Würzburg and regional brands Frankenland and Thüringer Land, illustrates that consolidation is occurring simultaneously at the multinational level and the cooperative level, progressively concentrating processing volume in operators whose scale enables investments that smaller regional dairies cannot sustain independently. For investors and industry observers, the consolidation trajectory points toward a future European dairy landscape where a smaller number of significantly larger processing entities serve a more diverse and globally distributed customer base, with the economies of scale and the R&D depth that the functional dairy and premium ingredient categories the market's growth is concentrated in genuinely require.
Functional and fortified dairy innovation capturing the highest-value consumer segments
The structural migration of European consumer dairy spending from commodity liquid milk toward functional, fortified, and health-positioned products is the defining commercial trend separating the market's volume base from its value growth frontier. Arla Foods Ingredients' November 2025 announcement of plans to showcase innovation capabilities in milk and whey proteins through a range of new high-protein food and beverage concepts at Fi Europe 2025 in Paris, alongside Danone's 2026 acquisition of Huel, the UK-based plant-based meal replacement and protein brand, in a deal valued at EUR 1 Billion, illustrates how both cooperative ingredient specialists and branded consumer dairy companies are investing at scale in the functional nutrition category that is growing fastest within the broader dairy ecosystem. Yoghurt is advancing at an estimated 5.1% CAGR, well above the overall market's 4.20%, driven by probiotic-enriched variants, Greek-style formats, low-sugar formulations, and high-protein positioning that align with the preventive nutrition and active lifestyle motivations of European consumers whose dairy purchasing decisions are progressively driven by health functionality rather than pure convenience or price. Latvia's Food Union expanding its Lakto brand with seven new lactose-free yoghurts in 2024, at precisely the moment when lactose-free dairy is transitioning from niche medical category to mainstream retail staple, illustrates how functional innovation is occurring simultaneously at the product development, retail allocation, and consumer awareness levels, compounding the commercial opportunity that each of these individually would create.
Carbon certification and regenerative farming transforming sustainability from cost to competitive asset
The progression of sustainability from a regulatory compliance burden into a commercial differentiator commanding measurable price premiums across Western European dairy retail is one of the most commercially significant structural shifts in the industry's current decade, and the speed at which it is happening is being driven by a combination of forces that would individually be insufficient but collectively are proving to be decisive. Swiss dairy producer Emmi's validation of its science-based CO2e reduction targets in 2025 as part of its net-zero strategy, and FrieslandCampina's ongoing progress in reducing emissions intensity per kilogram of dairy product through renewable energy integration and manure management investment, illustrate how the industry's sustainability investment is being structured around verified, third-party-validated targets rather than aspirational brand commitments, a distinction that institutional retail buyers and sustainability-oriented consumers are increasingly equipped to make and act upon. Carbon-neutral certified dairy products are commanding notable price premiums across premium retail channels in Germany, the United Kingdom, and the Nordics, creating the revenue case that converts sustainability from an ESG reporting exercise into a P&L-positive commercial strategy. As the EU Farm to Fork Strategy's sustainability requirements progressively tighten and consumers develop the literacy to distinguish credible carbon-neutral certification from unsubstantiated green claims, the dairy producers who have made early and verifiable sustainability investments are building a commercial advantage that compounds with each regulatory tightening cycle.
What the Market Numbers Actually Tell Us
The single-year growth from USD 260.48 Billion in 2025 to USD 271.31 Billion in 2026, adding USD 10.83 Billion in annual market value in twelve months, reflects a market operating simultaneously across multiple value creation mechanisms. Volume growth in Eastern European markets where rising middle-class incomes are driving dairy consumption diversification beyond liquid milk into cheese, yoghurt, and functional products contributes incrementally but consistently. Value growth in Western European markets through premiumisation, functional positioning, and lactose-free expansion contributes the per-unit revenue improvement that sustains the market's growth rate despite the structural constraints on per-capita consumption growth in already high-consumption mature markets. Export revenue growth from whey protein, skimmed milk powder, and whole milk powder shipments to Asia Pacific and the Middle East contributes the international dimension that converts European dairy's processing sophistication into global ingredient trade value. The projected milestone of USD 319.97 Billion by 2030, representing the midpoint of the forecast trajectory toward USD 377.06 Billion by 2034, confirms that the market's growth is steady and compounding rather than front-loaded, providing the demand visibility that justifies the long-cycle capital investment decisions that cooperative mergers, processing facility expansions, and sustainable farming infrastructure require.
Where New Opportunities Are Emerging
The most commercially significant emerging opportunity in the Europe dairy market sits at the precise intersection of whey protein ingredient export growth and the Asia Pacific infant formula supply chain's accelerating demand for certified, high-specification European dairy ingredients. As Chinese, South Korean, and Southeast Asian infant formula manufacturers navigate ongoing supply chain diversification strategies following recent food safety concerns with non-European origins, European whey protein and milk powder from verified sustainable sources with full traceability documentation are commanding a quality premium that cooperative ingredient processors, particularly those with the scale and certification infrastructure that Arla-DMK consolidation would provide, are uniquely positioned to capture. Simultaneously, Poland's emerging role as both the fastest-growing national consumption market at 5.6% of European dairy revenue in 2025 and as a cost-competitive processing base serving Western European private-label supply chains represents a strategically unusual dual opportunity that operators willing to commit processing investment in the country can exploit across both the domestic demand and the export processing dimensions simultaneously, building the kind of geographic diversification within the European footprint that provides commercial resilience against the country-specific agricultural policy and weather-related production risks that concentrated national market exposure inevitably creates.
Explore Market Forecasts, Growth Potential : https://www.imarcgroup.com/europe-dairy-market