Europe Decorative Laminates Market: New Opportunities Are Emerging
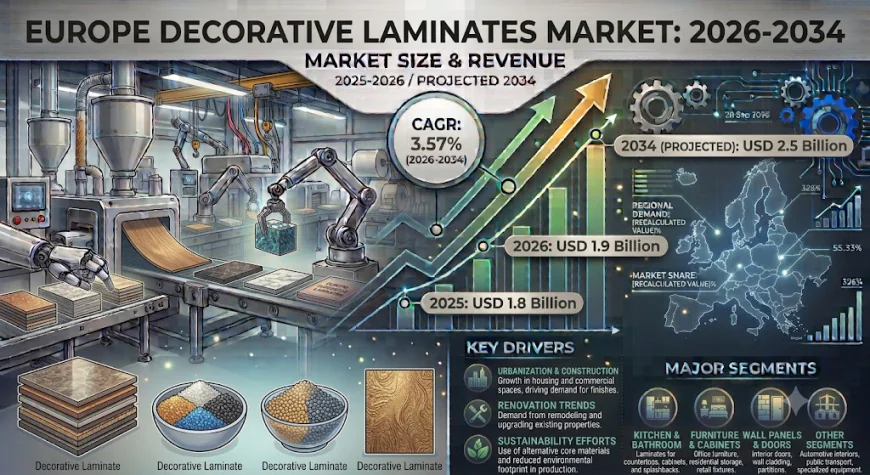
Europe decorative laminates market increased from USD 1.8 Billion in 2025 to USD 1.9 Billion in 2026 and is estimated to reach USD 2.5 Billion by 2034, growing at a CAGR of 3.57% during the forecast period.
 Team Imarc
There is a surface covering so ubiquitous in European interiors that most people interact with it multiple times every day without consciously registering its presence, on kitchen worktops, office desks, wardrobe doors, retail display fixtures, and hospital corridor wall panels. Decorative laminates have earned that invisibility through decades of reliable performance, competitive pricing, and the ability to convincingly replicate premium materials at a fraction of their cost. What is changing now is the ambition of the category itself, moving from background functionality into a design material capable of carrying photorealistic imagery, intelligent thermal properties, anti-bacterial surface chemistry, and certified circular credentials that align with European construction's most demanding environmental standards.
The market data reflects this evolution across a consistent and commercially grounded growth trajectory. The Europe decorative laminates market increased from USD 1.8 Billion in 2025 to USD 1.9 Billion in 2026 and is estimated to reach USD 2.5 Billion by 2034, growing at a CAGR of 3.57% during the forecast period. Adding USD 700 Million in annual market value over nine years, in a building materials category defined by conservative specification cycles and price-sensitive procurement, reflects a market whose growth is being sustained simultaneously by renovation activity across ageing European building stock, urbanisation driving compact living solutions, and technology investment that is progressively expanding what decorative laminates can do and where they can credibly compete.
What's Driving Growth in the Europe Decorative Laminates Market?
High-pressure laminates' commanding dominance as the largest product type reflects the category's unmatched combination of durability, design versatility, and application breadth that no competing surface material in the same price range can replicate. HPL's resistance to impact, heat, moisture, and sustained wear makes it the default specification for commercial environments requiring heavy-duty surface performance, hospitality, healthcare, retail, and office applications where surface replacement costs and operational disruption from maintenance failures are commercially significant. The development of anti-bacterial HPL variants, fire-resistant grades, and self-healing formulations has further expanded the application scope into sectors with the most stringent hygiene and safety requirements, broadening HPL's addressable market beyond its foundational furniture and cabinetry base.
Furniture and cabinets commanding the largest application segment reflects the category's foundational role in the European interior fit-out economy, a market sustained simultaneously by new residential construction, commercial fit-out cycles in hospitality and retail, and the substantial renovation activity driven by European consumers' preference for periodically refreshing kitchen and bathroom environments where laminated surfaces concentrate. The growing demand for modular, flat-pack, and ready-to-assemble furniture formats, where laminates' lightweight, consistent thickness, and easy machining properties are engineering prerequisites rather than aesthetic preferences, is sustaining demand volumes that bespoke joinery and solid surface alternatives cannot approach at comparable price points.
Residential end use anchoring the market's largest demand segment through a combination of new housing construction, where laminates are specified at both premium and mass market tiers across virtually every surface category, and the renovation of older European housing stock that represents the single largest source of laminate replacement demand. The EU Renovation Wave strategy's mandate to improve the energy performance of European buildings is generating construction activity that flows directly into decorative laminate demand for the surfaces that refurbished interiors require, kitchen fronts, bathroom panels, flooring overlays, and wall coverings that transform thermally improved envelopes into liveable, contemporary spaces.
Matte and suede finishes holding the largest texture segment share reflects the dominant direction of European interior design aesthetics, away from the high-gloss surfaces that defined earlier decades toward the sophisticated, fingerprint-resistant, and tactilely refined surfaces that contemporary minimalism and Scandinavian-influenced design cultures across Germany, the Netherlands, and the Nordic markets have made the default preference across both residential and commercial specification. The practical advantages of matte finishes, their resistance to showing fingerprints, minor surface scratches, and everyday wear marks, align precisely with the maintenance-conscious specification priorities of both residential consumers and commercial facility managers who are responsible for sustaining surface appearance across high-contact environments.
Germany's market leadership anchored by its concentration of quality-oriented construction activity, the renovation demands of an ageing housing stock that predates modern laminate standards, and the presence of major manufacturers and advanced production facilities that serve both domestic and continental export demand, creates a national market whose purchasing sophistication and specification standards set the commercial benchmark that competitors across the European market aspire to reach.
Three Trends Reshaping the Industry
Digital printing technology enabling the design capabilities that are redefining the category's competitive positioning
The integration of advanced digital and 3D printing technologies into European decorative laminate manufacturing has produced a design revolution whose commercial consequences are progressively visible in specification decisions across residential renovation, commercial fit-out, and transportation interior markets. Manufacturers are now capable of producing laminates with photorealistic reproductions of natural materials, wood grains, marble veining, concrete textures, fabric weaves, and metallic surfaces, at resolutions and dimensional accuracy that make the distinction from the original material genuinely difficult to detect at normal viewing distances and under varied lighting conditions. This capability is commercially transformative because it enables specifiers and consumers to access the aesthetic appeal of premium natural materials at the cost, hygiene, and durability profile of laminate, and the design flexibility to create entirely novel surface aesthetics that have no natural material precedent. DuPont's European partner Lampre's September 2024 launch of Fortilam Decor, a laminate solution incorporating Tedlar PVF film for transportation interior applications demonstrated at InnoTrans in Berlin, illustrates how digital printing and advanced polymer integration are extending decorative laminates into technically demanding applications including rail interior wall panels and contact-intensive surface areas where both design precision and chemical resistance are non-negotiable specifications. The Finnish company Warming Surfaces Ltd.'s May 2023 collaboration with laminate producer Surforma to reveal an intelligent warming wall incorporating ultra-thin Halia warming technology, delivering energy-efficient radiant heating incorporated directly into building materials, with the surface appearance of a premium decorative laminate, demonstrates how digital production integration is enabling entirely new functional capabilities within the decorative laminate format, aligning with EU energy efficiency objectives in ways that purely aesthetic surface materials cannot claim.
Circular economy innovation transforming laminate's sustainability credentials from constraint to commercial asset
The EU's Packaging and Packaging Waste Regulation, the Construction Products Regulation revision, and the broader Green Deal framework are collectively creating a regulatory environment in which the sustainability credentials of building materials are transitioning from a voluntary competitive differentiator into a commercial prerequisite for specification in public sector, institutional, and environmentally certified private sector projects. The June 2024 joint announcement by EPF and Unilin of circular flooring solutions as part of the EU-backed CISUFLO project, specifically highlighting Unilin's breakthrough steam explosion technology that recovers wood fibres from MDF and HDF-based laminate flooring, enabling their reuse in new products at a pilot line in France that has been demonstrated as both economically viable and energy efficient at pre-commercial scale, signals that the circular economy agenda for decorative laminates has moved from aspirational policy objective to technically validated commercial pathway. Guardian Glass's October 2024 launch of six new Environmental Product Declarations for its flat, coated, and laminated glass products in Europe, including the lower-carbon Guardian NEXA 6 and NEXA 9 formulations with reduced embodied carbon of over 40% and 20% respectively, illustrates how adjacent laminated surface product manufacturers are investing in the certified environmental performance documentation that LEED, BREEAM, and EU whole-life carbon calculation frameworks require for specification in premium construction projects. For decorative laminate manufacturers, the commercial logic is increasingly clear: certified recycled content, low-emission formulations, and end-of-life recovery programmes are progressively becoming procurement prerequisites rather than optional sustainability add-ons, creating commercial incentive that aligns investment in circular production with the mainstream market opportunity rather than confining it to a niche green segment.
Transportation and speciality interior applications expanding the addressable market beyond the residential and furniture core
The expansion of decorative laminates from their foundational residential and commercial furniture applications into technically demanding transportation interior, healthcare, and high-specification commercial environments represents the most commercially significant market boundary extension underway in the European industry. Worthington Steel's December 2024 acquisition of a 52% stake in Italy-based Sitem Group, a major electric motor lamination producer for automotive and industrial sectors in Europe, reflects the growing strategic importance of the transportation lamination category that is being driven simultaneously by EV interior specification requirements and the broader modernisation of rail, bus, and aviation interior environments that European public transport investment programmes are funding. The transportation application segment's requirements, surfaces that combine design appeal with chemical resistance, ease of cleaning, anti-graffiti properties, fire retardancy, and the dimensional stability to withstand the vibration and temperature cycling of operational transport environments, are precisely the performance envelope that HPL's advanced formulations are designed to address, creating a natural expansion pathway that sustains volume growth beyond the residential renovation cycles that have historically been the market's most important demand variable.
What the Market Numbers Actually Tell Us
The single-year growth from USD 1.8 Billion in 2025 to USD 1.9 Billion in 2026, and the steady trajectory to USD 2.5 Billion by 2034, reflects a market whose consistent, compounding growth is sustained by the breadth of its application base rather than concentration in any single sector or design trend. The premium pricing segment's dominance over the mass tier reflects a European consumer and commercial specification culture that consistently prioritises quality, longevity, and design authenticity over lowest initial cost, a purchasing philosophy that sustains the margin environment within which manufacturers can justify investment in digital printing capability, functional laminate innovation, and certified sustainable production without the pressure to compete purely on commodity pricing. The organised sector's dominance over unorganised supply reflects European buyers' consistent preference for certified products, reliable supply chains, and the technical service that complex specification requirements demand, a market structure that creates durable advantages for established manufacturers with the quality management systems, distribution networks, and brand recognition that public sector procurement and premium commercial specification increasingly require as prerequisites rather than advantages.
Where New Opportunities Are Emerging
The most commercially significant emerging opportunity in the Europe decorative laminates market lies at the precise intersection of intelligent surface technology and the EU's accelerating building energy renovation mandate. A decorative laminate that simultaneously delivers the design aesthetics that residential and commercial specifiers require and the energy-efficient heating or cooling performance that deep renovation programmes are trying to achieve, demonstrated at commercial readiness by Warming Surfaces Ltd.'s intelligent warming wall concept, represents a product category that converts decorative laminates from a surface finish decision into an energy systems decision, dramatically expanding the procurement budget pool from which it can be specified and the decision-making stakeholders who must be persuaded. Manufacturers who invest in developing and certifying functional laminate systems that contribute measurably to building energy performance assessments under EU regulatory frameworks, earning LEED, BREEAM, or national energy certification credits, are positioning themselves at the highest-value frontier of the renovation market's growth, serving a client base whose investment decisions are driven by regulatory compliance and long-term operational cost reduction rather than purely aesthetic preference. Simultaneously, Soyang Europe's January 2025 expansion into Ireland with self-adhesive vinyl laminates offering an in-house slitting service for custom sizes illustrates how distribution network expansion and product customisation accessibility are progressively making the decorative laminates market commercially viable in smaller national markets that the established continental distribution infrastructure had previously served inadequately, opening geographic growth opportunities that systematic distribution investment can unlock without requiring the capital intensity of new manufacturing capacity.
Explore Market Forecasts, Growth Potential : https://www.imarcgroup.com/europe-decorative-laminates-market/requestsample