Does Home Insurance Cover Water Leak Detection Services?
Discover when home insurance covers leak detection services, how hidden water damage claims work, and how to protect your property from costly repairs.
 john smit
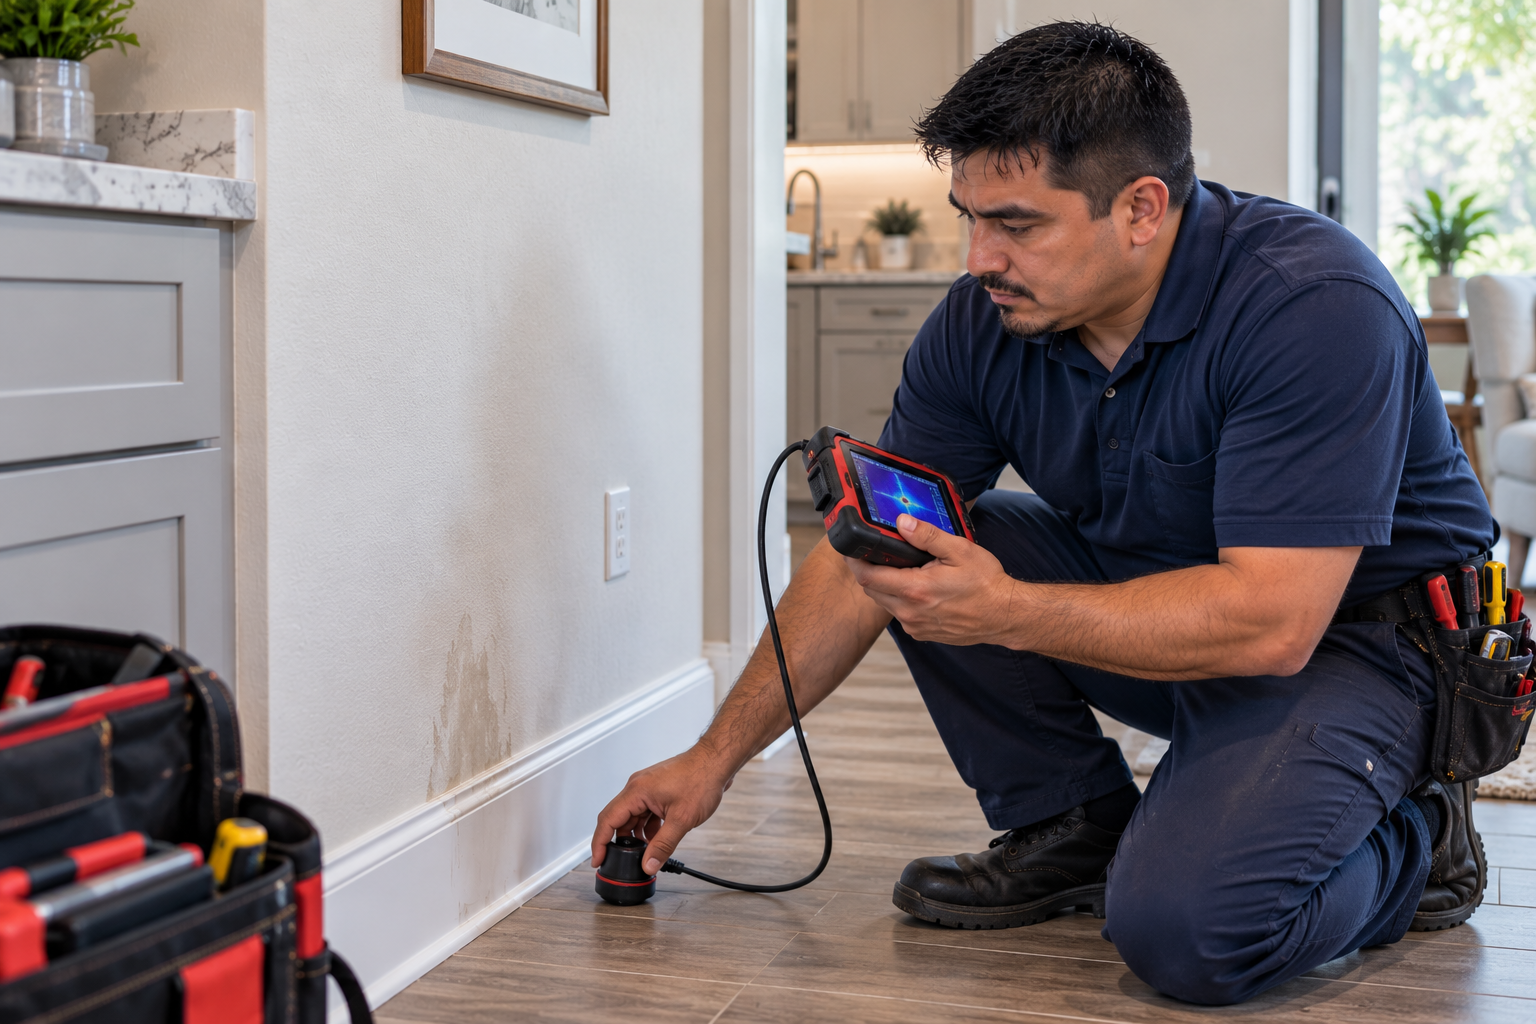
A sudden spike in your monthly utility bill or the faint sound of running water behind a drywall partition often points to a hidden plumbing issue. Catching subterranean or concealed pipe failures early requires specialized equipment, but hiring professionals offering expert leak detection services can cost several hundred to over a thousand dollars out of pocket. Many homeowners assume their standard policy automatically reimburses these initial diagnostic fees. Understanding how homeowners insurance treats diagnostic detection versus physical repair work helps you navigate claims smoothly and prevent unexpected expenses.
Understanding How Home Insurance Treats Water Leaks
Homeowners insurance policies do not treat every type of water issue the same way. Insurance coverage depends heavily on the root cause of the leak and how quickly the damage occurred. Standard home insurance policies (such as an HO-3 policy in the United States) focus on protection against sudden, accidental perils rather than long-term deterioration.
Sudden and Accidental Discharge vs. Gradual Damage
Insurance policies draw a clear line between sudden mishaps and gradual neglect:
-
Sudden and Accidental Events: A ruptured supply line under your kitchen sink, a burst freeze-damaged pipe inside a wall, or a failing water heater valve usually qualify as sudden events. Insurance generally covers the resulting water damage and the access work required to locate the issue.
-
Gradual Wear and Tear: Slow drips that trickle for months, undetected pinhole leaks caused by aging copper pipes, or deteriorating seam seals around a shower pan are considered maintenance issues. Insurance companies expect homeowners to maintain their plumbing systems, so damage caused by neglected leaks is typically excluded.
The Concept of "Tear-Out" and Access Coverage
One of the most confusing parts of water damage insurance claims is the distinction between locating the leak and replacing the broken pipe. Most standard property policies include a clause known as "tear-out" coverage.
If a covered water event occurs inside a wall, ceiling, or beneath a concrete slab foundation, your policy will usually pay to demolish and restore the structural elements needed to reach the pipe. However, the physical pipe component itself (which may only cost $20 in materials) is rarely covered, as property insurance covers consequential damage rather than basic plumbing hardware repairs.
When Does Home Insurance Cover Leak Detection Services?
Reimbursement for diagnostic work depends on whether the leak leads to a covered property claim. Insurance companies view diagnostic investigations as part of the overall claim investigation, provided the underlying issue falls under covered perils.
+-------------------------------------------------------------------------------------------------------+
|                                    LEAK DETECTION COVERAGE FLOW                                       |
|                                                                                                       |
|  [ Water Leak Suspected ]                                                                            |
|            │                                                                                          |
|            ▼                                                                                          |
|  Was the leak sudden & accidental? ───► NO ───► Claim Denied (Maintenance Issue / Neglect)            |
|            │                                                                                          |
|           YES                                                                                         |
|            ▼                                                                                          |
|  Did it cause covered property damage? ───► NO ───► Detection Fees Paid Out-of-Pocket                |
|            │                                                                                          |
|           YES                                                                                         |
|            ▼                                                                                          |
|  [ Detection & Tear-Out Covered ] (Subject to Policy Deductible & Limits)                             |
+-------------------------------------------------------------------------------------------------------+
Diagnostic Detection as Part of a Covered Claim
If an active supply pipe bursts under your subfloor and ruins your hardwood flooring, your insurer will process a water damage claim. In this scenario, the cost of bringing in professional leak detection services to pinpoint the break using acoustic sensors or infrared cameras is usually covered under the claim's investigation and access provisions.
Because the leak caused immediate structural damage through a covered peril, finding the exact point of origin is considered a necessary step in stopping further loss.
Preventive Detection and Uncovered Claims
If you notice your water meter spinning while no faucets are on and hire a technician to inspect your lines purely as a preventive measure, your insurance company will not reimburse the bill if no covered physical loss has occurred. Insurance policies require actual, tangible property loss before triggering coverage.
Similarly, if diagnostic technicians trace a leak to a worn-out faucet washer, aging caulk around a bathtub, or continuous ground seepage through a basement foundation wall, the insurer will deny the overall claim along with any associated diagnostic costs.
Slab Leaks: A Common Diagnostic Challenge
Slab leaks—plumbing failures occurring beneath a building's concrete foundation—represent one of the most common scenarios requiring specialized acoustic or tracer gas detection methods. Ground movement, soil corrosion, or friction against concrete can cause subsurface copper pipes to crack over time.
How Slab Leak Claims Work
When a slab leak occurs, water pushes up through the concrete, damaging subflooring, carpet, or baseboards.
-
Detection Phase: Electronic leak locators mark the exact spot on the concrete slab to minimize structural demolition. If the resulting water damage is covered, the insurer pays for this diagnostic scanning.
-
Access Phase (Tear-Out): Jackhammering through the concrete foundation to reach the pipe is generally covered under tear-out provisions.
-
Pipe Repair Phase: Replacing or patching the section of pipe is the homeowner's out-of-pocket responsibility.
-
Restoration Phase: Pouring fresh concrete, replacing subflooring, and restoring damaged finishes are typically covered by your policy.
Alternate Repair Options: Spot Repair vs. Rerouting
Insurance adjusters usually calculate tear-out coverage based on direct access (breaking through the slab at the leak location). However, licensed plumbers often recommend bypassing the slab entirely by routing a new PEX line through the attic or ceiling.
If rerouting is cheaper than jackhammering through structural concrete, insurers may approve the rerouting cost under their loss mitigation requirements. Always consult your adjuster before agreeing to a full pipe reroute.
Coverage Breakdown for Water Leak Scenarios
Understanding how insurance applies to different plumbing scenarios helps set realistic expectations before filing a claim.
| Leak Scenario | Primary Root Cause | Are Detection Services Covered? | Are Structural Repairs Covered? | Is Pipe Hardware Covered? |
|---|---|---|---|---|
| Burst Copper Supply Line in Wall | Sudden freezing or high pressure | Yes (Covered under claim) | Yes (Wallboard & flooring) | No |
| Slab Leak Under Foundation | Soil friction or pipe corrosion | Yes (If water damages interior) | Yes (Concrete tear-out & floor) | No |
| Slow Drip Behind Shower Wall | Worn seal / Long-term seam leak | No (Excluded as wear & tear) | No | No |
| Sewer Line Backup into Home | Tree root intrusion / Main block | Only with Endorsement Rider | Only with Endorsement Rider | No |
| Appliance Hose Rupture | Sudden washing machine hose split | Yes (Covered under claim) | Yes (Cabinetry & subflooring) | No |
Key Policy Exclusions and Optional Endorsements
Standard homeowners policies contain specific exclusions regarding water movement and plumbing upkeep. Adding optional riders can protect against gaps in coverage.
Common Exclusions to Watch For
-
Sewer and Drain Backup Exclusion: Standard policies exclude damage caused by water backing up through main sewer lines or sump pumps unless you add a specific endorsement.
-
Continuous or Repeated Leak Exclusion: Many policy contracts state that leaks running unnoticed for more than 14 days are completely excluded from coverage, regardless of whether you knew about them.
-
Earth Movement and Ground Water: Damage caused by rising surface water, mudslides, or hydrostatic pressure against basement walls falls under flood insurance rather than standard home insurance.
Recommended Policy Riders
Homeowners looking to avoid high out-of-pocket expenses during a plumbing emergency should consider adding two common endorsements:
-
Water Backup and Sump Overflow Rider: Pays for cleanup, structural repair, and diagnostic costs when drains or main sewer lines back up into the dwelling.
-
Service Line Coverage: Covers repairs, excavation, and detection fees for exterior utility pipes (fresh water supply lines and main sewer laterals) running between your house and the street connection.
How to File a Water Leak Claim Step-by-Step
Filing a claim correctly speeds up processing and lowers the risk of denial.
-
Mitigate the Damage Immediately: Shut off your main water supply line as soon as you suspect a leak. Insurance contracts require property owners to take reasonable steps to prevent further damage.
-
Document the Evidence: Take clear photographs and video footage of standing water, damaged personal belongings, wet drywall, and any visible plumbing defects before starting cleanup.
-
Hire a Licensed Plumber: Contact a qualified professional to perform an initial assessment. Request a detailed, itemized invoice that clearly separates diagnostic detection fees, tear-out labor, and pipe repair materials.
-
Notify Your Insurance Carrier: Contact your insurance agent or claims department to open a file. Provide your photos, the plumber's initial findings, and a clear timeline of when you first noticed the issue.
-
Work with the Claims Adjuster: Allow the insurer's assigned adjuster to inspect the property before making permanent structural repairs. Keep all replaced pipe fittings or damaged materials so the adjuster can verify the failure mode.
Conclusion
Navigating home insurance coverage for hidden water leaks comes down to identifying the root cause and acting quickly. While standard policies do not cover basic plumbing maintenance or worn-out hardware, they typically reimburse diagnostic leak detection fees and structural tear-out costs when a leak stems from a sudden, covered event. Reviewing your policy details, maintaining your home's plumbing systems, and adding service line riders can protect you from unexpected out-of-pocket costs. If you suspect an active leak in your home, contact a licensed professional immediately to locate the source and prevent further property damage.
Frequently Asked Questions
Will home insurance pay for leak detection if no damage is found?If a plumber uses diagnostic equipment but finds no leak or physical water damage, your insurance company will usually not cover the inspection invoice. Property insurance policies require a covered physical loss to trigger financial coverage. How much do professional leak detection services usually cost?
In the United States, professional leak detection services typically range from $250 to $800, depending on the home's size, region, and detection technology used (such as thermal imaging or acoustic ground microphones). Complex slab leak detection can cost more. Does insurance cover slab leak detection?
Insurance covers slab leak detection if the water escaping from the foundation pipe causes covered water damage to subflooring, walls, or living spaces. If the leak is discovered before any property damage occurs, the detection fees are generally not covered. What should I do if my insurance claim for leak detection is denied?
Review the written denial letter alongside your policy's declaration page and water damage clauses. If the insurer cited gradual damage but the leak was sudden, obtain a detailed technical report from your licensed plumber and submit a formal claim appeal. Is water damage from a burst pipe covered by home insurance?
Yes, water damage caused by a burst supply pipe is standardly covered under most home insurance policies, provided the pipe burst suddenly and was not caused by leaving a building unheated during cold weather.