Australia Green Building Market Size, Share, Trends, Growth and Forecast Report 2026-2034
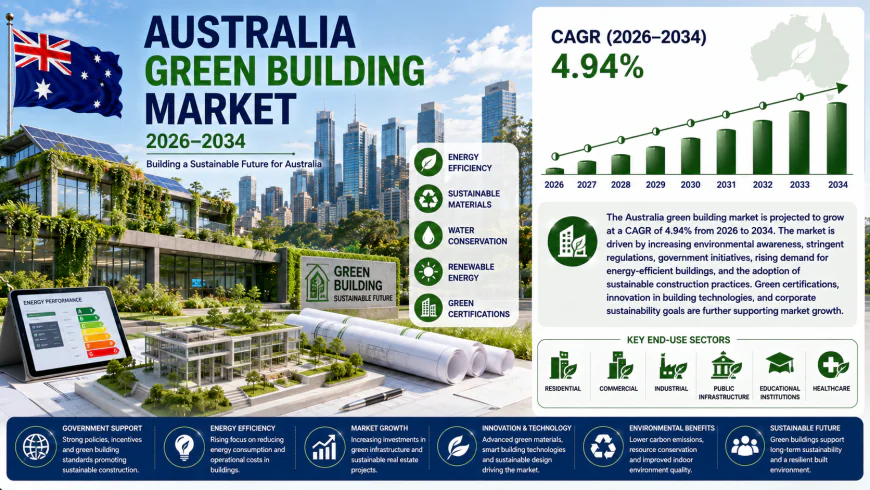
The Australia green building market size increased from USD 3.5 Billion in 2025 to USD 3.7 Billion in 2026 and is expected to reach USD 5.5 Billion by 2034, at a CAGR of 4.94%.
 Arlo Bennett
Market Overview
The Australia green building market size reached USD 3.5 Billion in 2025 and is projected to reach USD 5.5 Billion by 2034, growing at a compound annual growth rate (CAGR) of 4.94% from 2026 to 2034, from USD 3.7 Billion in 2026. The market is driven by stricter energy standards and building rules, Green Star certification, government rebates and grants, federal net-zero targets, and corporate sustainability and ESG investment.
Australia Green Building Market Summary
- The Australia green building market covers materials, systems, and products used to design and construct energy-efficient, sustainable buildings, across residential, commercial, and industrial uses.
- Green buildings are valued for lower operating costs, reduced emissions, better occupant health and comfort, and stronger asset value.
- The ecosystem includes building product manufacturers, developers and builders, architects and engineers, certification bodies such as the Green Building Council of Australia (GBCA), investors and owners, governments and regulators, and occupants.
- Major segments identified in the market include product type (exterior products, interior products, building systems, solar products, others), end user (residential, commercial, industrial, others), and region.
- The market is benefiting from the National Construction Code, state schemes such as NSW’s BASIX, Green Star and NABERS ratings, and investor demand for low-carbon assets.
- The GBCA’s 2026 policy snapshot (February 2026) calls for timely implementation of NCC 2025 and notes that Building Ministers agreed to pause residential energy efficiency changes until 2029.
PORTER’S FIVE FORCES ANALYSIS
- Competitive Rivalry: Moderate. Product makers, builders, and consultants compete on performance, certification credentials, and cost. Business implication: Firms should differentiate through verified performance and certification support.
- Supplier Power (Materials and Systems): Moderate. Specialized insulation, glazing, solar, and building systems come from a limited set of suppliers, and imports expose projects to cost swings. Business implication: Developers should secure supply early and diversify sourcing.
- Buyer Power (Developers and Owners): Moderate to High. Large developers and institutional owners set specifications and weigh green premiums against cost. Business implication: Suppliers should show lifecycle savings and certification benefits.
- Threat of Substitutes: Low to Moderate. Conventional materials and minimum-code construction substitute for green options where cost dominates. Business implication: Emphasize operating-cost savings and tightening regulation.
- Threat of New Entrants: Moderate. Product and consulting barriers are modest, while certification credibility and track record favor incumbents. Business implication: Established firms should strengthen proven performance and partnerships.
Request a Sample Report for In-Depth Market Insights: https://www.imarcgroup.com/australia-green-building-market/requestsample
MARKET GROWTH DRIVERS
Stricter Energy Standards and Building Rules
The National Construction Code and state schemes such as BASIX set rising minimum performance requirements, pushing demand for efficient envelopes, systems, and solar products.
Green Star Certification and Government Support
Green Star serves as a benchmark for sustainable design, and government rebates, grants, and net-zero targets encourage certified projects and retrofits.
Corporate Sustainability and Investor Demand
Corporate sustainability goals and ESG investment favor green-certified buildings, which are seen as holding value better and having lower operating costs.
AUSTRALIA GREEN BUILDING MARKET SEGMENTATION
Product Type Insights:
- Exterior Products
- Interior Products
- Building Systems
- Solar Products
- Others
End User Insights:
- Residential
- Commercial
- Industrial
- Others
Regional Insights:
- Australian Capital Territory & New South Wales
- Victoria & Tasmania
- Queensland
- Northern Territory & Southern Australia
- Western Australia
COMPETITIVE LANDSCAPE
The Australia green building market includes building product manufacturers, solar and building systems suppliers, developers, and certification and advisory bodies. Competition centers on verified performance, certification credentials, cost, and ability to meet tightening code requirements. Market dynamics include evolving national energy rules, growing attention to embodied carbon, and investor demand for low-carbon assets.
REGIONAL ANALYSIS
- ACT & New South Wales: A leading market, with BASIX, large commercial development in Sydney, and strong sustainability policy in Canberra.
- Victoria & Tasmania: A strong market with active commercial and residential development in Melbourne and state energy efficiency programs.
- Queensland: A growing market with population growth, new construction, and climate-driven design needs.
- Western Australia: A market with expanding commercial and residential building and strong solar adoption.
- Northern Territory & Southern Australia: Smaller markets where climate-appropriate design and solar products shape demand.
RECENT INDUSTRY DEVELOPMENTS
September 2026: The Green Building Council of Australia welcomed proposed national standards for sustainable data centres, addressing energy consumption, water use and environmental performance. The initiative reflects growing demand for energy-efficient buildings and sustainable infrastructure as Australia expands its digital economy and AI computing capacity.
September 2026: The Green Building Council of Australia launched the Green Star Performance Industrial Pathway, extending sustainability assessment to industrial facilities. The initiative supports developers and property owners seeking to improve energy efficiency, reduce emissions and strengthen environmental performance across warehouses, logistics facilities and industrial estates.
August 2026: Victoria proposed new requirements for future data centres to secure renewable electricity and energy storage, fund their own grid connections and use recycled or non-potable water for cooling. The measures respond to projected digital infrastructure investment of A$150 billion by 2030, strengthening opportunities for green building technologies and sustainable construction.
August 2026: The Australian Government expanded support for commercial, industrial and agricultural rooftop solar systems of up to 1 megawatt, reducing installation costs by approximately 20%. The initiative helps building owners reduce electricity expenses and operational emissions while encouraging renewable energy integration into commercial properties.
May 2026: NABERS approved an update to its Energy rating framework, scheduled to take effect in July 2030. The revised approach will assess energy efficiency alongside renewable energy use, encouraging buildings to reduce overall energy demand while transitioning to cleaner power sources.
Key Aspects Required for the Australia Green Building Market
- Market Performance: USD 3.5 Billion in 2025, USD 3.7 Billion in 2026, with a projected trajectory to USD 5.5 Billion by 2034.
- Market Outlook: A 4.94% CAGR through 2034 indicates steady growth driven by regulation and sustainability demand.
- Growth Drivers: Stricter energy standards; Green Star certification and government support; and corporate sustainability and investor demand.
- Competitive Landscape: Product makers, systems suppliers, developers, and advisors competing on performance and certification.
- Value Chain Analysis: From material and system suppliers, through designers, builders, and certifiers, to owners, investors, and occupants.
- Industry Trends: Efficient electrification; embodied carbon and low-carbon materials; solar integration; and performance-based ratings such as NABERS and Green Star.
- Strategic Recommendations: Align products with NCC requirements; pursue certification credentials; offer lifecycle cost evidence; invest in low-carbon materials; and engage with policy developments.
Note: If you need any specific information that is not currently covered within the scope of the report, we will provide the same as a part of customization.
Speak to an analyst: https://www.imarcgroup.com/request?type=report&id=24681&flag=C
Report Format, Delivery, and Customization Details
- Report Format Mode: PDF and Excel (Editable version in PPT/Word format available on special request)
- Report Delivery Mode: Online Delivery, Physical Delivery
- Report Delivery Time: report delivered over email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
- Report Confirmation Mode: Yes, via email
- Report Customization Mode: Yes, via Email / Call
- Report Table of Content: Yes
- Report List of Figures: Yes
- Report Methodology Mode: Yes
- Request For Sample Report: Yes