Financing a 125 cc Scooter Without the Guesswork
What to Have Ready Before You Apply Approval moves much faster when the paperwork is in order, and most delays come from a missing document rather than a credit issue.
 Advaith singh
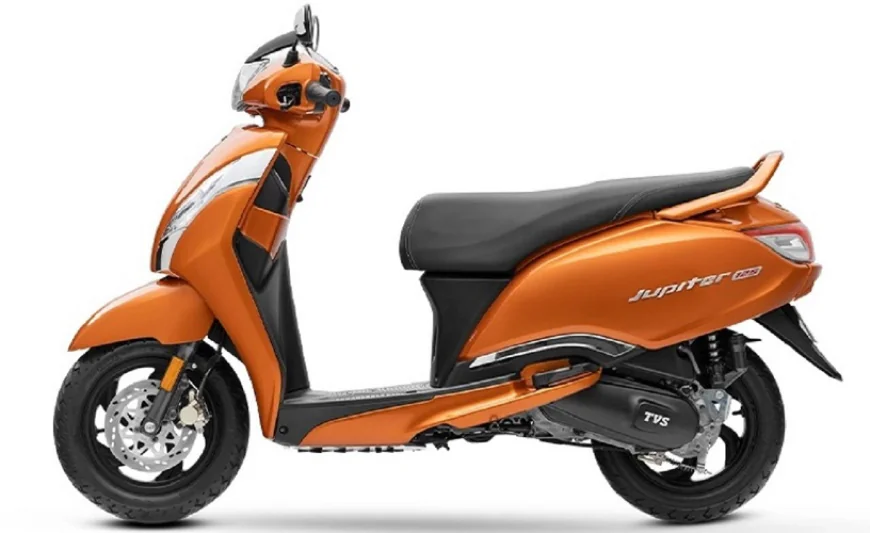
Buying a scooter on finance is normal in India, but the process still catches people out. A buyer walks in focused on colour and variant, and walks out having agreed to a tenure and an insurance package they had not thought about. The way to avoid that is to arrive with your own numbers already worked out. A TVS Jupiter 125 EMI calculator takes a few minutes to run and turns a confusing conversation into a simple comparison.
Start With the Variant, Not the Instalment
The Jupiter 125 is sold across several trims, and the gap between the entry variant and the disc-brake connected version is real money. Deciding the specification first matters, because every later calculation depends on it. A rider who commutes across unfamiliar parts of the city will use the connected cluster and navigation prompts regularly. A rider on a short, fixed route may never open the app. Settling this question honestly usually removes one variant from the shortlist immediately.
The Inputs That Move the Monthly Figure
Three things do most of the work. The down payment sets how much is actually borrowed. A larger upfront amount lowers both the instalment and the total interest. The tenure spreads the balance across months, so a longer term reduces the monthly figure while increasing what is repaid in total. The interest rate depends on the lender and on the buyer's credit history, and it can vary between two dealers quoting the same scooter in the same week.
Why the Total Matters as Much as the Monthly
It is easy to optimise for the smallest instalment and lose sight of the full picture. A loan stretched over the longest available tenure will always look comfortable month to month, but the extra years of interest add up quietly. The useful habit is to write down two figures for each option: the monthly instalment and the total amount repaid across the term. Seen side by side, the sensible middle option usually becomes obvious without any argument.
What to Have Ready Before You Apply
Approval moves much faster when the paperwork is in order, and most delays come from a missing document rather than a credit issue.
-
Proof of identity and current address
-
Recent income proof or salary slips
-
Bank statements covering the last few months
-
Passport-sized photographs
-
A cancelled cheque for the repayment mandate
-
Details of any existing loan commitments
The Charges That Sit Outside the Instalment
A quote is rarely just the loan. Processing fees, documentation charges and the insurance premium are usually folded into the on-road figure before the loan is calculated, which means they quietly increase the amount financed. It is worth asking for the breakdown rather than the headline number. Comprehensive cover costs more than the minimum requirement and often makes sense for a new scooter, but it should be a decision rather than a default.
Prepayment Is Worth Asking About
Many buyers pay off a two-wheeler loan early when a bonus or a good month allows it. Whether that saves money depends on the lender's terms. Some allow part-prepayment without penalty, some apply a foreclosure charge, and some have a lock-in period before any prepayment is permitted. Asking this question at the start costs nothing and occasionally saves a meaningful amount later.
The Trade-In Question
Many buyers are replacing an older scooter, and the exchange value directly reduces the amount that needs financing. It is worth getting a valuation before fixing the down payment, because a reasonable trade-in can shorten the tenure by several months without changing the monthly outgo at all. Condition, service history and paperwork all affect what is offered, so having the documents in order is worth the small effort it takes.
Arriving Prepared Changes the Conversation
Running a Jupiter 125 EMI calculator before the showroom visit does more than produce a number. It gives a buyer a range they are comfortable with and makes it easy to notice when a quote has been built on assumptions they did not agree to. The scooter is the same either way. The difference is in how confidently the buyer signs for it.