Tokenized Deposits vs. Stablecoins for Enterprise Asset Tokenization: Which Settlement Model Fits Your Business?
Compare tokenized deposits and stablecoins for enterprise asset tokenization, including settlement, liquidity, compliance, and integration.
 imdanielsmith
Enterprise asset tokenization is changing how businesses issue, transfer, and settle ownership of bonds, private credit, and money market funds. However, representing an asset on a blockchain does not automatically solve the payment problem. Businesses must also decide how money will move when an asset changes hands.
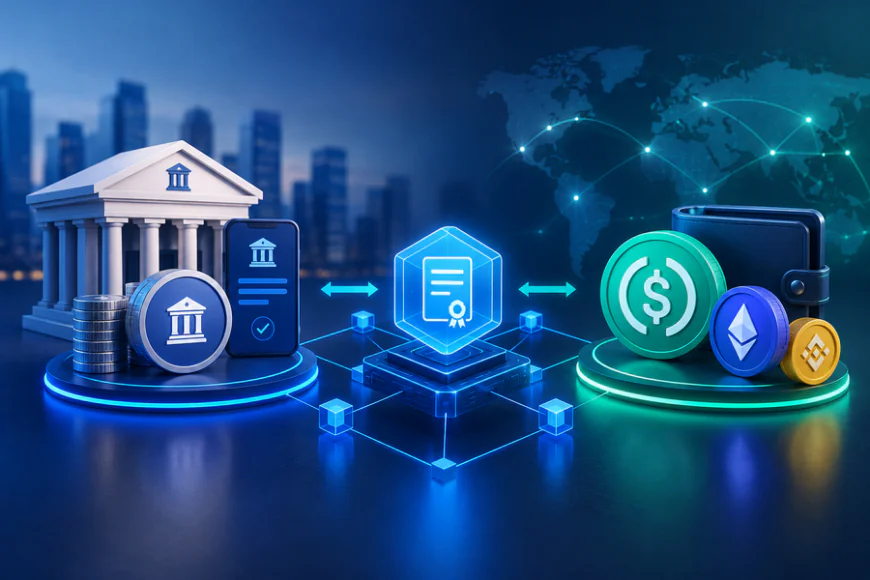
Two options are gaining attention: tokenized bank deposits and stablecoins. Both can support programmable transactions, but they differ in issuer risk, settlement access, liquidity, and integration requirements. For companies evaluating Enterprise Asset Tokenization Solutions, the right choice depends on who needs to receive the funds, where transactions occur, and how settlement must be controlled.
How Tokenized Deposits and Stablecoins Differ
Tokenized deposits are digital representations of commercial bank deposits recorded on a blockchain. The issuing bank remains responsible for the deposit, while tokenization enables programmable transfers and potentially faster settlement.
Stablecoins are digital tokens designed to maintain a relatively stable value, commonly against the US dollar. They are issued under specific legal and operational arrangements and are typically supported by reserves. Unlike bank deposits, they do not automatically qualify for deposit insurance.
According to Blockdaemon’s comparison, the distinction affects institutional risk management, transaction controls, and the infrastructure needed to move funds.
For businesses selecting Enterprise Asset Tokenization Solutions, the decision should therefore start with the underlying financial claim, not simply the blockchain network.
1. Choose the Settlement Model Based on the Transaction
Consider a company issuing tokenized corporate bonds to eligible institutional investors. When an investor purchases a bond, the issuer needs to receive payment while ownership of the bond transfers according to the transaction rules.
This is a delivery-versus-payment (DvP) requirement: the asset and payment should settle together, reducing the risk that one party delivers without receiving the other side.
Tokenized deposits may be suitable when:
-
The issuer, investors, and settlement participants already have relationships with participating banks.
-
The transaction requires bank-issued money and controlled participant access.
-
Treasury teams need programmable transfers linked to existing banking operations.
Stablecoins may be suitable when:
-
Investors use compatible digital wallets across different institutions or jurisdictions.
-
The transaction depends on public blockchain liquidity or integration with digital asset marketplaces.
-
Participants need to move funds outside a single bank's network, subject to applicable legal and compliance requirements.
Neither model guarantees atomic settlement by itself. The payment infrastructure, asset smart contract, custody arrangements, and transaction coordination must all support the intended settlement process.
2. Evaluate Cross-Bank Reach Before Choosing Tokenized Deposits
A common implementation mistake is assuming that tokenized deposits can move freely between any two banks simply because they use blockchain technology.
In practice, a tokenized deposit represents a liability of its issuing bank. Moving value to a customer at another institution may require interoperability arrangements and settlement of the resulting interbank obligation. Stablecoins can circulate between compatible wallets without requiring the recipient to hold an account with the original issuer, although redemption and transfer restrictions still apply.
Oracle's September 2026 analysis highlights this payment-orchestration challenge: banks must coordinate customer payments, liquidity, and settlement when transactions cross institutional boundaries.
When evaluating Enterprise Asset Tokenization Solutions, businesses should verify supported banks, blockchain networks, wallet types, redemption routes, and settlement finality before committing to an architecture.
3. Compare Liquidity, Redemption, and Operating Costs
A transaction that settles on-chain in seconds may still require additional time or cost to convert the payment instrument into usable business cash.
For example, a private credit marketplace might accept stablecoins for investment subscriptions but require the fund administrator to reconcile receipts and redeem the tokens before paying expenses in fiat currency. Network fees, conversion spreads, liquidity availability, and banking cut-off times can affect the actual settlement cost.
Tokenized deposits may simplify reconciliation with participating banks, but integration with core banking systems and limited network reach can increase implementation complexity.
Before selecting a model, assess:
-
Liquidity: Is sufficient money available on the required network at the settlement deadline?
-
Redemption: How quickly can funds be converted into usable fiat currency?
-
Counterparty exposure: Which bank or issuer owes the holder, and what protections apply?
-
Operational costs: What are the fees for transactions, custody, compliance, reconciliation, and integration?
-
Availability: Can transfers and redemptions operate outside conventional banking hours?
A sound Enterprise Asset Tokenization Solutions business case should compare the total cost of completing a transaction, not just the blockchain transaction fee.
4. Design Compliance and Integration Into the Platform
Settlement architecture must accommodate investor eligibility, sanctions screening, transaction monitoring, and jurisdiction-specific transfer restrictions. Tokenized securities may also require controls that prevent transfers to unauthorized wallets.
Tokenized deposits can align with participating banks' existing compliance processes, while stablecoin transactions may require additional controls around wallet screening, issuer exposure, blockchain analytics, and redemption.
Businesses should also establish how the tokenization platform communicates with custody providers, investor management systems, accounting software, and payment infrastructure. Reconciliation must account for failed transfers, duplicate instructions, pending transactions, and differences between on-chain records and internal books.
A provider such as Debut Infotech can be evaluated for the blockchain engineering and system integration required to implement these workflows. Organizations should assess its technical capabilities against their specific security, compliance, and operational requirements rather than assuming that any platform automatically delivers regulatory compliance.
Where a business also needs trading infrastructure, a crypto exchange development company may help address related marketplace, wallet, and trading-system requirements. The scope should be defined separately from the settlement and asset-issuance architecture.
5. Should Enterprises Use Both Models?
For many businesses, a hybrid architecture may be more practical than selecting one instrument exclusively.
A tokenized bond platform could use tokenized deposits for settlement among participating banking clients while supporting regulated stablecoins for eligible investors transacting through compatible external wallets. This approach can expand payment options, provided the platform manages conversion, liquidity, compliance, and reconciliation across both systems.
The New York Fed's February 2026 research also examines the broader economic trade-offs between bank deposits and stablecoins, reinforcing that the choice involves more than transaction speed alone.
Final Recommendation
The best settlement model depends on the transaction's participants, financial obligations, and operating environment. Tokenized deposits are worth evaluating when bank relationships and deposit-based settlement are central to the workflow. Stablecoins may be more suitable when external wallet access, public blockchain liquidity, and cross-border reach are priorities.
Before implementing Enterprise Asset Tokenization Solutions, test both models against a real transaction: issue or transfer an asset, execute payment, handle a failed settlement, reconcile records, and redeem the proceeds. That practical assessment will reveal whether a single settlement model or a hybrid approach best fits the business.