Steel Pipes and Tubes Market Advances with Growing Pipeline Infrastructure
Steel manufacturers must focus on product durability, performance improvements, and cost efficiency to maintain their competitive positions.
 Aditi Jdv
Steel Pipes and Tubes Market
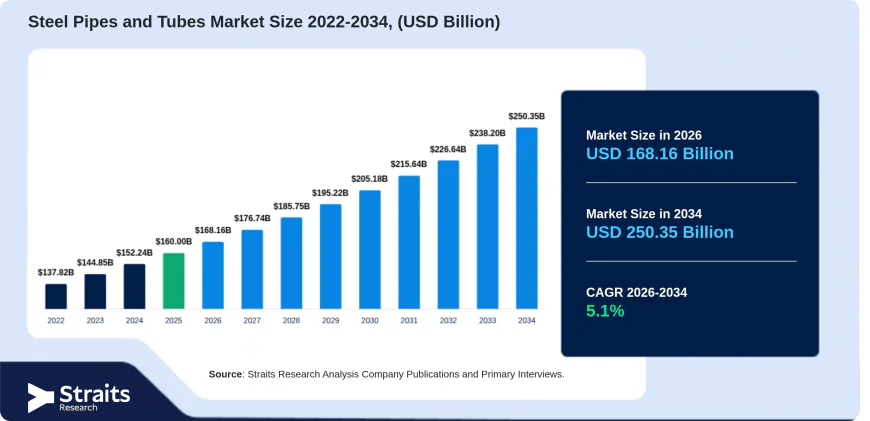
The global steel pipes and tubes market size was valued at USD 160 billion in 2025 and is projected to grow from USD 168.16 billion in 2026 to USD 250.35 billion by 2034, registering a CAGR of 5.1% during the forecast period (2026–2034). The market is supported by increasing investments in oil and gas infrastructure, expanding construction activities, industrial development, and the modernization of transportation networks. Steel pipes and tubes are essential components across several industries because of their strength, durability, pressure resistance, and ability to withstand demanding operating conditions.
Steel pipes and tubes are widely used in oil and gas transportation, construction, automotive manufacturing, water distribution, power generation, and industrial processing. Their versatility makes them suitable for transporting liquids and gases, supporting structural frameworks, and manufacturing mechanical components. Increasing infrastructure investments, urbanization, and industrial activities are expected to create favorable opportunities for manufacturers throughout the forecast period.
For detailed market insights, growth forecasts, and competitive analysis, visit: https://straitsresearch.com/report/steel-pipes-and-tubes-market
Steel Pipes and Tubes Market Drivers
Increasing Investments in Oil and Gas Infrastructure Drive Market Growth
The expansion of oil and gas exploration, production, and transportation infrastructure is a major factor driving the steel pipes and tubes market. Pipelines are essential for transporting crude oil, natural gas, and refined petroleum products between production sites, processing facilities, storage terminals, and distribution networks. Steel pipes are preferred for these applications because of their mechanical strength, pressure-bearing capacity, and suitability for challenging environmental conditions.
Investments in pipeline construction, offshore exploration, and natural gas distribution are creating opportunities for manufacturers. Energy companies require specialized pipes that can withstand high pressure, temperature variations, and corrosive environments. These requirements are encouraging manufacturers to improve steel grades and develop products with enhanced durability. The construction and modernization of cross-border energy transportation networks are further supporting industry demand.
Growing Construction and Infrastructure Development Drive Market Growth
Rapid urbanization and infrastructure development are increasing the consumption of steel pipes and tubes across residential, commercial, and industrial construction projects. These products are used in structural frameworks, water supply systems, drainage networks, heating installations, and building support structures. Their strength and load-bearing capabilities make them suitable for projects that require long-term structural reliability.
Government investments in transportation infrastructure, smart cities, water distribution, and public utilities are creating additional opportunities. Bridges, industrial facilities, commercial buildings, and urban infrastructure projects require different types of steel pipes and tubes. Increasing construction activities across developing economies are expected to support product consumption.
Industrial Manufacturing and Automotive Production Drive Market Growth
Steel pipes and tubes are important components in manufacturing equipment, machinery, automotive systems, and industrial processing facilities. Their applications include hydraulic systems, exhaust systems, chassis components, heat exchangers, and mechanical structures. Increasing manufacturing activities and industrial automation are supporting the need for precision-engineered steel tubing.
The automotive industry also uses steel tubes in vehicle structures, fuel systems, and mechanical components. Manufacturers are focusing on lightweight and durable materials to improve vehicle efficiency, safety, and performance. These requirements are encouraging the use of specialized steel tubing products.
Steel Pipes and Tubes Market Challenges
Raw Material Price Volatility Creates Cost Pressures
Fluctuations in iron ore, steel scrap, coking coal, and energy prices can significantly affect steel pipe and tube manufacturing costs. Production processes such as steelmaking, rolling, welding, and finishing require substantial raw material and energy inputs. Sudden changes in input prices can reduce profit margins and create difficulties in maintaining competitive product pricing.
Smaller manufacturers may experience greater pressure because of their limited ability to absorb unexpected cost increases. Efficient procurement strategies, improved production processes, and better resource utilization are important for managing these challenges.
Environmental Regulations and Manufacturing Costs Restrain Market Expansion
Steel production and pipe manufacturing involve energy-intensive processes that contribute to industrial emissions. Governments and environmental authorities are implementing stricter regulations concerning carbon emissions, energy consumption, waste management, and industrial pollution. Compliance with these requirements can involve investments in cleaner technologies, equipment upgrades, and improved production facilities.
Manufacturers are also facing pressure to reduce their environmental footprint while maintaining production efficiency. Although sustainable manufacturing practices can improve long-term operational performance, the initial investment requirements may increase production costs.
Competition from Alternative Materials
Steel pipes and tubes face competition from alternative materials such as plastic, copper, and composite products in selected applications. PVC and HDPE pipes are commonly used in water distribution, drainage, and certain chemical transportation systems because of their corrosion resistance and relatively low installation costs.
The availability of alternative materials can influence purchasing decisions, particularly in applications where high pressure and mechanical strength are not essential. Steel manufacturers must focus on product durability, performance improvements, and cost efficiency to maintain their competitive positions.
Steel Pipes and Tubes Market Segmentation
The steel pipes and tubes market is segmented based on technology and application.
By Technology
Based on technology, the market is segmented into seamless, electric resistance welded (ERW), and submerged arc welded (SAW) pipes and tubes.
The electric resistance welded (ERW) segment holds the leading market position and is projected to grow at a CAGR of 5.6% during the forecast period. ERW pipes are widely used because of their cost efficiency, manufacturing flexibility, and suitability for low- and medium-pressure applications. Their use across construction, water transportation, and industrial infrastructure supports segment growth.
Seamless pipes are manufactured without welded joints and are preferred for applications requiring high strength, pressure resistance, and reliability. They are commonly used in oil and gas exploration, power generation, and industrial processing. Submerged arc welded pipes are primarily used in large-diameter pipeline projects and applications requiring strong welded joints and structural durability.
By Application
Based on application, the market includes oil and gas, chemicals and petrochemicals, automotive and transportation, mechanical engineering, power plants, construction, and others.
The oil and gas segment holds the largest market share and is expected to grow at a CAGR of 6% during the forecast period. The extensive use of steel pipes in oil country tubular goods (OCTG), drilling operations, energy transportation, and refinery processing supports its leading position. Increasing investments in pipeline infrastructure and exploration activities are further contributing to segment growth.
The chemicals and petrochemicals industry uses steel pipes for transporting industrial fluids, chemicals, and processing materials. Automotive and transportation applications include vehicle structures, exhaust systems, and mechanical components. In construction, steel pipes and tubes are used in structural frameworks, utility networks, and infrastructure projects. Power plants and mechanical engineering facilities also rely on these products for fluid transportation and equipment manufacturing.
Steel Pipes and Tubes Market Regional Insights
North America benefits from established oil and gas infrastructure, pipeline modernization projects, and industrial manufacturing activities. The United States plays an important role in regional consumption because of its extensive energy transportation networks and demand for specialized steel products. Investments in natural gas infrastructure, pipeline maintenance, and industrial facilities are supporting market opportunities.
Europe maintains a strong industrial base supported by automotive manufacturing, construction, energy infrastructure, and engineering activities. Germany, the United Kingdom, France, and Italy contribute to regional demand. Infrastructure modernization, industrial equipment manufacturing, and investments in cleaner energy systems are creating opportunities for advanced steel pipes and tubes.
Asia-Pacific dominated the global steel pipes and tubes market with a 59% share in 2025 and is projected to register a CAGR of 6.7% during the forecast period. China, India, Japan, and South Korea are important contributors because of their established steel manufacturing industries and expanding infrastructure activities. Rapid urbanization, industrialization, construction projects, and investments in energy transportation and water distribution networks are supporting regional growth.
Latin America, the Middle East, and Africa offer opportunities through energy infrastructure development, construction activities, and investments in water transportation systems. Brazil and Mexico contribute to Latin American demand through industrial and infrastructure projects. In the Middle East, oil and gas production and pipeline construction support the consumption of specialized steel products. African countries are also investing in urban infrastructure, water distribution, and industrial facilities, creating additional opportunities for manufacturers.
Steel Pipes and Tubes Market Key Players Analysis
The steel pipes and tubes market includes established steel manufacturers and specialized tubular product companies competing across global markets. Leading companies focus on manufacturing efficiency, product innovation, advanced steel grades, and corrosion-resistant technologies to strengthen their market positions. Strategic investments in production facilities and the development of specialized products for energy transportation, construction, and industrial applications are important competitive strategies.
The major players operating in the steel pipes and tubes market include:
-
Tenaris S.A.
-
Vallourec S.A.
-
Nippon Steel Corporation
-
Tata Steel Limited
-
JFE Steel Corporation
-
ArcelorMittal S.A.
-
United States Steel Corporation
-
Hyundai Steel Company
-
Baowu Steel Group Corporation Limited
-
SeAH Steel Corporation
Conclusion
The global steel pipes and tubes market is expected to experience steady growth through 2034, supported by investments in oil and gas infrastructure, construction, industrial manufacturing, and water transportation networks. Increasing requirements for high-strength steel products and advanced pipeline technologies are creating opportunities for manufacturers across different applications. However, raw material price fluctuations, environmental regulations, and competition from alternative materials remain important challenges. Companies focusing on product quality, manufacturing efficiency, technological improvements, and specialized steel solutions are expected to strengthen their competitive positions during the forecast period.
About Us
Straits Research is a leading market research and intelligence organization specializing in research, analytics, and advisory services. The company provides comprehensive market reports, industry insights, and strategic business intelligence across multiple industries, helping organizations identify growth opportunities and make informed business decisions.
Contact Us
Email: [email protected]
Tel: +1 646 905 0080 (U.S.)
Tel: +44 203 695 0070 (U.K.)