Practical Financial Strategies for Growing Small Businesses
Preparing for Seasonal Changes and Business Growth Revenue and expenses may change throughout the year. Some businesses experience seasonal demand, while others face fluctuations in project schedules, customer purchasing patterns, staffing requirements, or supply costs.
 lore
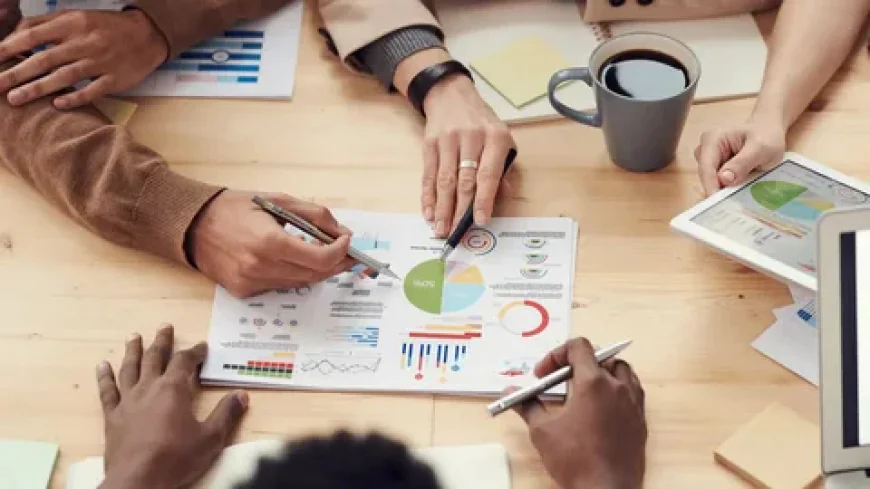
Small businesses depend on effective financial management to maintain stable operations, meet their obligations, and prepare for future growth. While attracting customers and delivering quality products or services are important priorities, maintaining organized financial records is equally essential. Business owners need reliable information about revenue, expenses, outstanding payments, and available cash to understand how their companies are performing and make informed decisions.
For entrepreneurs in The Woodlands, Texas, developing a consistent financial recordkeeping process can make daily business management more predictable. From independent consultants and professional service providers to retailers, contractors, and growing family-owned companies, every business benefits from understanding where its money comes from and how it is spent. Small business bookkeeping provides the foundation for tracking these activities, identifying financial trends, and maintaining records that support long-term stability.
Understanding the Role of Bookkeeping in Small Business Operations
Bookkeeping involves recording, organizing, and classifying financial transactions so that a business can maintain an accurate picture of its financial activities. These records include customer payments, supplier invoices, payroll transactions, equipment purchases, bank fees, and recurring operating expenses. When transactions are recorded consistently, business owners can review financial information without relying on incomplete estimates or scattered paperwork.
Creating a Reliable Financial Recordkeeping System
A reliable bookkeeping system begins with a clear process for documenting every business transaction. Each payment received should be connected to the appropriate customer or source of income, while each expense should be assigned to a suitable category. Supporting documents, such as receipts and invoices, help verify transaction details and explain why money was received or spent.
For example, a small consulting firm may receive payments from several clients while paying for software subscriptions, office expenses, professional insurance, and contractor assistance. Recording these activities separately helps the owner understand which costs are necessary for operations and how much income remains after expenses.
Businesses should also maintain a consistent method for organizing digital and paper documents. A dedicated folder structure, accounting platform, or document management system can make financial information easier to retrieve. When records follow the same process every month, reviewing transactions and preparing reports becomes less complicated.
Separating Business and Personal Finances
Mixing personal and business transactions can create confusion when reviewing financial records. A business owner might use the same card for groceries, office supplies, fuel, and client-related purchases, making it difficult to determine which transactions belong to the company.
Maintaining separate business bank accounts and payment methods helps reduce this problem. It also makes bank reconciliation easier and improves the clarity of financial reports. When an owner contributes personal funds to the business or withdraws money for personal use, the transaction should be recorded appropriately rather than incorrectly classified as ordinary revenue or an operating expense.
Clear separation is particularly helpful when a company begins hiring employees, applying for financing, or preparing financial information for a tax professional. Good records establish a more dependable foundation for understanding the business's financial position.
How Small Business Bookkeeping Services Support Financial Clarity
Managing financial records independently may be practical when a business has relatively few transactions. However, as the company grows, bookkeeping can require more time and attention than the owner can comfortably provide alongside daily responsibilities.
Maintaining Accurate Income and Expense Records
Accurate transaction records help business owners understand the difference between money received and money earned, as well as the difference between expenses incurred and cash paid. These distinctions become important when customers pay invoices later or suppliers allow a business to pay bills after receiving goods or services.
For instance, a contractor may complete a project in one month but receive payment the following month. Meanwhile, the contractor may need to pay workers, purchase materials, and cover transportation costs before the customer pays. Recording income and expenses consistently helps explain these timing differences and provides a more accurate view of the company's activity.
Businesses researching Small Business Bookkeeping Services in The Woodlands, TX should consider how organized transaction records can improve visibility into everyday operations. Proper categorization, supporting documentation, and regular reconciliation help reduce uncertainty and make financial information more useful.
Reducing the Administrative Burden on Owners
Small business owners frequently manage several responsibilities at once, including customer communication, scheduling, purchasing, employee supervision, and business development. Bookkeeping can become difficult to maintain when these tasks compete for the same limited time.
A defined financial routine helps prevent records from accumulating until the end of the quarter or tax season. Owners can establish regular procedures for collecting receipts, reviewing invoices, recording transactions, and checking account balances.
When bookkeeping responsibilities are shared with a qualified professional, the owner should still review reports and provide accurate documentation. Delegating routine recordkeeping can reduce administrative pressure, but informed business decisions still require the owner to understand the financial information being presented.
Managing Cash Flow and Business Expenses
Cash flow is one of the most important considerations for a small business. A company may report healthy sales but still struggle to pay its bills when customer payments arrive later than expected. Monitoring the movement of money helps owners prepare for upcoming obligations and avoid relying solely on revenue figures when making spending decisions.
Monitoring Customer Payments and Outstanding Invoices
Businesses that invoice customers after completing work must track outstanding balances carefully. Without an accounts receivable process, overdue invoices may go unnoticed, creating cash shortages that affect payroll, supplier payments, and other expenses.
An organized invoice record should identify the customer, invoice date, amount due, payment deadline, and current payment status. Reviewing this information regularly helps owners recognize delayed payments and maintain a realistic expectation of when funds may become available.
For example, a local service business that completes multiple projects each month may have a significant amount of money tied up in unpaid invoices. Tracking these balances helps the owner distinguish completed work from cash actually received and plan expenses around expected payment dates.
Planning for Recurring Costs and Unexpected Expenses
Every business has recurring financial commitments. These may include rent, utilities, insurance, software subscriptions, payroll, loan payments, and supplier invoices. Other costs, such as equipment repairs or replacement purchases, may occur less frequently but still require financial preparation.
Expense tracking helps owners identify how much they typically spend and which categories have increased over time. Comparing monthly costs can reveal opportunities to adjust purchasing habits, renegotiate agreements, or eliminate subscriptions that no longer serve a useful purpose.
A cash flow forecast can further improve planning by estimating future income and expenses. Business owners can use this information to determine whether sufficient funds are likely to be available for upcoming commitments and whether major purchases should be postponed until cash reserves improve.
Financial Reporting for Better Business Decisions
Financial reports turn bookkeeping records into practical information. Rather than examining individual transactions, owners can review summaries that explain profitability, financial position, and cash movement. These reports can support decisions about pricing, hiring, inventory, expansion, and operating budgets.
Understanding Profit and Loss Statements
A profit and loss statement summarizes revenue and expenses over a defined period. It helps business owners determine whether the company generated a profit or loss and understand which categories had the greatest effect on performance.
Monthly comparisons are particularly useful. If sales increase but profit declines, rising labor costs, supplier prices, or other operating expenses may be reducing margins. If revenue remains stable while expenses decrease, the business may be benefiting from more efficient operations.
Owners can also compare actual results with their budgets. A business that consistently spends more than expected on transportation or materials can investigate the reasons and adjust its plans. Regular reviews help turn financial reports into a practical management tool instead of documents that are examined only during tax preparation.
Using Balance Sheets to Understand Financial Position
A balance sheet summarizes a company's assets, liabilities, and equity at a particular point in time. Assets may include cash, equipment, inventory, and amounts customers owe. Liabilities may include outstanding supplier bills, loans, and other financial obligations.
Understanding these figures helps owners evaluate the relationship between what the business owns and what it owes. A company with substantial equipment or inventory may appear financially strong in some respects while still having limited cash available to cover immediate bills.
Balance sheets can also help business owners prepare for financing discussions and assess whether expansion plans are financially realistic. Their usefulness depends on accurate underlying records, which makes regular reconciliation and appropriate transaction classification essential.
Local Business Considerations in The Woodlands, Texas
The Woodlands is part of the greater Houston region and supports a diverse range of businesses, including professional services, healthcare-related practices, retail operations, contractors, property-related companies, and independent consultants. Each business type has different financial activities, documentation needs, and reporting priorities.
Adapting Bookkeeping to Different Industries
A retail business may need to monitor inventory purchases, sales receipts, refunds, payment processing fees, and product costs. A consultant may focus more heavily on client invoices, professional expenses, contractor payments, and recurring subscriptions. A construction-related company may need to track materials, project costs, subcontractor payments, equipment, and customer deposits.
These differences affect how financial records should be organized. A chart of accounts should provide enough detail to help owners understand their operations without creating an excessive number of categories that make routine bookkeeping difficult.
Business owners should consider which reports they need most frequently and what information will help them evaluate performance. A system designed around the company's actual activities is more useful than one that records transactions without providing meaningful insight.
Preparing for Seasonal Changes and Business Growth
Revenue and expenses may change throughout the year. Some businesses experience seasonal demand, while others face fluctuations in project schedules, customer purchasing patterns, staffing requirements, or supply costs.
Historical bookkeeping records help owners identify these patterns and plan accordingly. For example, a company that earns a large portion of its annual revenue during certain months may need to maintain cash reserves to cover expenses during slower periods.
Growth can introduce additional complexity. Hiring employees, adding locations, purchasing equipment, or expanding into new markets increases the number and type of transactions a company must track. Reviewing financial reports consistently helps owners understand whether the business can support these changes without creating unnecessary financial pressure.
Using Accounting Software to Improve Efficiency
Modern accounting software can simplify many bookkeeping tasks. Depending on the platform, businesses may be able to import bank transactions, create invoices, track expenses, reconcile accounts, store receipts, and generate financial reports. These features can reduce repetitive data entry and make information easier to access.
Choosing the Right Accounting Platform
The most appropriate software depends on transaction volume, industry requirements, budget, reporting needs, and the owner's familiarity with accounting systems. A small company with simple operations may need only basic transaction tracking and financial reports, while a growing business may require more advanced inventory, project costing, or payroll integrations.
Before choosing a platform, owners should consider ease of use, compatibility with their bank accounts, reporting options, user permissions, data export capabilities, and available support. They should also consider whether the system can accommodate future growth.
Software should simplify the bookkeeping process rather than make it more complicated. Employees and outside professionals who work with the system should follow consistent procedures so transactions are categorized correctly and reports remain understandable.
Protecting Digital Financial Records
Financial records contain sensitive information that should be protected against unauthorized access, accidental deletion, and other security risks. Appropriate safeguards include strong passwords, multifactor authentication, restricted access permissions, secure document sharing, and reliable backups.
Businesses should provide access only to people who need it for their responsibilities. Access should also be reviewed when employees or contractors change roles or stop working with the company.
Automation does not remove the need for human review. Bank feeds may import duplicate transactions, payment transfers may be categorized incorrectly, and expenses may be assigned to unsuitable accounts. Regular reconciliation helps identify these issues and improves the reliability of financial reports.
Preparing Financial Records for Taxes and Compliance
Organized bookkeeping can make tax preparation more manageable by keeping income, expenses, supporting documents, and account balances accessible throughout the year. It also helps business owners identify missing information before deadlines approach.
Maintaining Documentation Throughout the Year
Useful financial documents may include customer invoices, sales receipts, supplier bills, bank statements, credit card statements, payroll records, loan documents, equipment purchases, and records of business-related travel or vehicle expenses.
The appropriate documentation depends on the nature of the transaction and applicable requirements. Business owners should maintain a consistent filing process so that supporting information can be matched to the corresponding entries in their accounting records.
Keeping records current also makes it easier to answer questions from lenders, tax professionals, or other authorized parties. When documents are organized as transactions occur, the business is less likely to face a last-minute search for missing receipts or explanations.
Understanding the Difference Between Bookkeeping and Tax Preparation
Bookkeeping and tax preparation serve related but distinct purposes. Bookkeeping focuses on maintaining accurate financial records and preparing reports about business activity. Tax preparation involves applying relevant tax rules to financial information and completing the required tax returns.
Texas does not impose an individual state income tax, but businesses may still have federal income tax responsibilities, payroll obligations, sales and use tax requirements, Texas franchise tax considerations where applicable, and other reporting duties depending on their circumstances.
Business owners should not assume that organized books automatically guarantee compliance with every requirement. Working with an appropriately qualified tax professional can help determine which obligations apply and whether additional documentation or adjustments are needed.
Recognizing When a Business Needs Additional Bookkeeping Support
Some owners can manage their own financial records successfully, especially when transaction volumes are modest and their systems are well organized. As a company grows, however, the time required to maintain the books may begin to interfere with other responsibilities.
Identifying Common Recordkeeping Problems
Unreconciled bank accounts, missing receipts, overdue invoices, unexplained balances, and inconsistent expense classifications are common signs that a bookkeeping process needs attention. Financial reports that are months behind may also prevent owners from recognizing problems while there is still time to respond.
Another warning sign is repeatedly postponing financial tasks because other business activities seem more urgent. When bookkeeping falls behind, transaction details may become harder to remember, making it more difficult to identify errors or determine the purpose of particular payments.
Addressing these problems early can prevent a small backlog from becoming a more complicated cleanup project. A consistent schedule and clear responsibility for each task can help restore order.
Evaluating Bookkeeping Arrangements
Business owners may choose to manage their records internally, hire an employee, or work with an external bookkeeping professional. The appropriate arrangement depends on transaction volume, business complexity, budget, internal expertise, and the level of reporting required.
When evaluating Small Business Bookkeeping Services in The Woodlands, TX, owners should consider the work included in the arrangement, the frequency of financial reporting, experience with similar businesses, software compatibility, document security, and communication practices.
It is also important to establish clear expectations about who handles invoicing, bill tracking, bank reconciliation, payroll records, and communication with tax professionals. A well-defined arrangement reduces confusion and helps ensure that important financial tasks are not overlooked.
Establishing a Consistent Financial Management Routine
A successful bookkeeping process depends on regular habits rather than occasional efforts to catch up. Businesses can improve financial visibility by assigning responsibility for recordkeeping, maintaining supporting documents, and reviewing reports according to a predictable schedule.
Creating Weekly and Monthly Financial Checklists
Weekly tasks may include recording transactions, reviewing incoming invoices, organizing receipts, monitoring outstanding customer payments, and checking upcoming bills. Completing these activities regularly reduces the risk of missing important details.
Monthly tasks should generally include reconciling bank and credit card accounts, reviewing expense classifications, checking accounts receivable and payable, and preparing financial statements. Owners should also compare current results with previous periods and investigate unusual changes.
The process should be practical for the size of the business. A straightforward checklist that is followed consistently is often more effective than an elaborate system that is difficult to maintain.
Using Financial Information to Guide Future Decisions
Bookkeeping becomes especially valuable when owners use financial information to guide their next steps. Reports can help identify rising expenses, evaluate service pricing, assess the affordability of new hires, and determine whether cash reserves are sufficient for planned investments.
For example, a business that notices increasing supply costs can review purchasing records to determine whether prices have changed or waste has increased. A company experiencing delayed customer payments can examine its invoicing procedures and improve the way outstanding balances are monitored.
Reviewing several months of information also helps distinguish temporary fluctuations from longer-term trends. Rather than making major decisions based on one unusually strong or weak month, owners can consider a broader view of financial performance.
Conclusion
Strong financial recordkeeping helps small businesses understand their performance, manage expenses, monitor cash flow, and prepare for future obligations. By maintaining accurate transaction records, organizing supporting documents, and reviewing financial statements regularly, business owners can make more informed decisions and respond to changing conditions with greater confidence.
For entrepreneurs considering Small Business Bookkeeping Services in The Woodlands, TX, the goal should be to establish a reliable financial process that fits the company's size, industry, and operational needs. Whether bookkeeping is handled internally or with professional assistance, consistency, accurate documentation, secure recordkeeping, and regular financial reviews can provide a solid foundation for sustainable business growth.
Frequently Asked Questions
1. What Do Small Business Bookkeeping Services Usually Include?
Bookkeeping arrangements may include recording income and expenses, reconciling bank and credit card accounts, organizing receipts, monitoring customer invoices and supplier bills, and preparing monthly financial reports. The exact scope depends on the business's needs and the agreed-upon responsibilities.
2. Why Is Bookkeeping Important for a Small Business?
Bookkeeping helps owners understand revenue, expenses, profitability, outstanding obligations, and cash flow. Accurate records also support budgeting, tax preparation, financial planning, and decisions about hiring or expansion.
3. How Often Should Small Businesses Update Their Books?
Transactions should generally be recorded regularly throughout the month, with bank and credit card accounts reconciled at least monthly. Businesses with frequent transactions may benefit from reviewing their records more often.
4. Can Bookkeeping Help Improve Cash Flow?
Yes. Tracking customer invoices, payment deadlines, operating expenses, and upcoming bills helps owners understand when money is expected to arrive and when payments must be made. This information supports more realistic cash flow planning.
5. What Financial Documents Should Small Businesses Keep?
Common documents include invoices, receipts, bank statements, credit card statements, payroll records, supplier bills, loan documents, and equipment purchase records. Retention periods and documentation requirements depend on the type of record and applicable rules.
6. When Should a Small Business Consider Professional Bookkeeping Assistance?
Professional assistance may be worth considering when records regularly fall behind, transactions become more complex, financial reports are difficult to prepare, or bookkeeping consumes too much of the owner's time. The business should compare service scope, experience, security practices, and cost before deciding.