Post Office Real Estate for Sale: What Investors Need to Know Before Buying
Searching for post office real estate for sale? Discover what drives value in USPS-leased properties and how to evaluate this government-backed income market.
 domhawkins
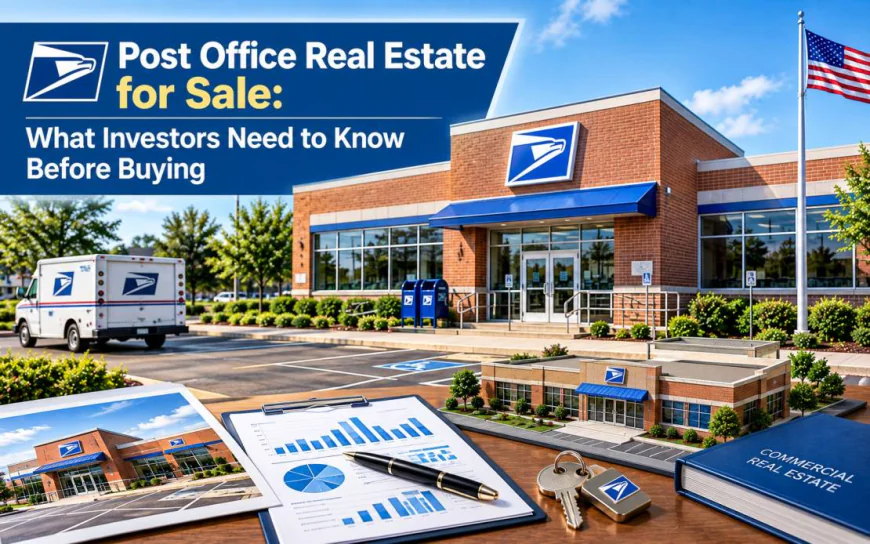
The market for post office real estate for sale has attracted a meaningfully different class of investor over the past several years, and the reasons are grounded in fundamentals rather than trend-chasing. Post office real estate for sale represents one of the few remaining categories in commercial real estate where the tenant is a federal agency with a statutory mandate, the income stream is supported by long-term lease structures, and the underlying asset serves a function that does not diminish during economic downturns. For income-focused investors who have spent years navigating the volatility of office, retail, and hospitality assets, that combination deserves serious attention.
The United States Postal Service leases a substantial portion of its national facility network from private landlords, which means ownership of these buildings changes hands regularly through both direct transactions and portfolio acquisitions. What was once a market dominated by local investors purchasing individual facilities has matured into a category where institutional platforms, dedicated property vehicles, and publicly traded REITs now compete for the same assets. Understanding what drives value in this market, and what risks accompany the income, is the essential starting point before any capital is committed.
Why the Post Office Real Estate Market Has Attracted Institutional Attention Now
The broader commercial real estate environment has pushed income-focused capital toward assets with more defensible cash flow characteristics. Office vacancies remain elevated across major metropolitan markets, and retail real estate continues navigating structural headwinds from the shift in consumer behavior toward e-commerce. Against that backdrop, net-lease assets anchored by creditworthy, operationally stable tenants have attracted sustained and growing interest from allocators who prioritize income predictability over appreciation potential.
USPS-leased facilities sit at a specific and well-defined position within that broader trend. The postal service operates under a federal mandate to deliver mail and packages to every address in the country, an obligation that does not respond to economic cycles or corporate earnings pressure the way private-sector tenant demand does. For investors who place tenant credit quality at the center of their underwriting framework, that statutory obligation carries meaningful practical weight.
The maturation of the buyer pool has also reshaped how post office real estate for sale transactions are priced and executed. Professional acquisition platforms with USPS-specific expertise, dedicated underwriting infrastructure, and the capital to transact at scale have entered a market that was once characterized by fragmented local ownership and inconsistent pricing. That professionalization has improved transparency and raised the standard of due diligence that serious participants now bring to every transaction.
What Makes USPS-Leased Buildings Structurally Distinct as Income Assets
Several features separate postal properties from conventional net-lease investments in ways that buyers should understand before evaluating any specific acquisition opportunity. The federal tenancy is the most fundamental distinction. The USPS does not carry private-sector balance sheet risk, and its operational continuity is backed by statute rather than by corporate performance metrics. That credit foundation is not replicated by most commercial tenants, including many that carry investment-grade private-sector ratings from major rating agencies.
Last-mile delivery facilities represent the most operationally critical subset within the postal property category. These buildings serve as the physical endpoints of the domestic mail and parcel network, the locations where sorted deliveries transition into individual delivery routes reaching homes and businesses. As domestic parcel volumes have expanded alongside the growth of e-commerce, the logistical importance of these facilities has deepened rather than diminished. Investors who understand this functional role are better positioned to evaluate which specific properties carry the most durable occupancy characteristics.
Lease structures in this segment typically include renewal options and periodic rent escalations that extend income visibility well beyond the initial term. For institutional investors building yield-oriented portfolios that require multi-year cash flow modeling, that predictability is a structural advantage that many other real estate categories cannot match with equivalent consistency. The combination of tenant credit quality, operational necessity, and lease design creates an income asset that warrants careful consideration from any allocation framework centered on stability and government-backed income.
How to Evaluate Post Office Real Estate for Sale as an Active Buyer or Long-Term Holder
For investors actively sourcing post office real estate for sale, the underwriting process involves several variables that differ from conventional commercial real estate acquisition due diligence. The remaining lease term is typically the most influential pricing variable in this category. Buildings with longer active lease terms under USPS occupancy command stronger pricing because they offer immediate income visibility without near-term renewal uncertainty. Buyers evaluating properties with leases approaching expiration should factor in the timeline and probability of renewal before assigning a value that assumes continued government occupancy.
Facility type and geographic positioning within the postal network also affect how buyers should think about long-term occupancy probability. Post office real estate for sale in high-volume delivery corridors, particularly last-mile delivery offices serving dense population centers, carries a different operational profile than administrative facilities in lower-priority locations. Applying the lens of the USPS's publicly stated modernization priorities to specific acquisition targets produces a more rigorous form of asset-level analysis than simple cap rate comparison allows.
Physical property condition is a variable that buyers should not underweight in their due diligence process. Buildings that have been consistently maintained and that align with current USPS operational requirements are more straightforward to underwrite and finance than those with deferred capital needs. Buyers who inspect properties with operational suitability in mind, rather than treating all postal facilities as interchangeable income assets, are better positioned to identify where durable income actually resides within the category.
How Postal Realty Trust Has Structured Access to This Market for Investors
For investors who want exposure to the post office real estate market without the operational complexity of direct property acquisition, Postal Realty Trust (NYSE: PSTL) provides the only exchange-listed alternative built exclusively around this asset category. Established in May 2019, Postal Realty Trust has assembled a national portfolio of USPS-leased facilities by acquiring properties from private owners across all 50 states, making it one of the most active and experienced buyers in the sector.
The public structure provides investors with liquidity and institutional-grade transparency that direct postal property ownership has historically not offered. Quarterly financial results are filed with the SEC, dividend history and tax information are publicly reported, and analyst coverage is available through the company's investor relations platform. For financial advisors and wealth managers evaluating alternative income allocations on behalf of clients, that disclosure infrastructure significantly lowers the research burden compared to assessing privately held postal property portfolios without standardized reporting.
The company has also developed specific institutional expertise in USPS lease structures, government termination provisions, and the facility-level implications of the federal postal modernization agenda. That accumulated knowledge is embedded in its acquisition and portfolio management processes in ways that first-time participants in the post office real estate for sale market are not positioned to replicate independently when sourcing and underwriting assets through conventional commercial real estate channels.
Risk Factors That Belong in Every Serious Evaluation of This Asset Class
A credible investment thesis requires a transparent accounting of where the genuine risks reside, and the postal property category is no exception. The USPS retains statutory termination rights on its leases under certain conditions, a provision that differs materially from standard commercial net-lease termination language. Buyers who assign terminal values to postal assets without reading the specific termination provisions in the applicable lease documents are accepting risk they have not fully priced, regardless of how strong the federal tenant argument appears on the surface.
The long-term financial condition of the USPS also warrants active monitoring from any investor with exposure to this category. Legacy obligations related to retiree health benefit pre-funding have weighed on the agency's balance sheet for many years, and while legislative reform has addressed portions of that burden, the agency's financial profile remains a variable that responsible long-term investors should track rather than assume away. Policy developments affecting the postal service can influence buyer sentiment and transaction pricing in ways that are not always predictable in advance.
Single-tenant concentration is a structural consideration that applies to this sector regardless of tenant quality. A real estate portfolio anchored entirely to one federal agency does not provide the diversification that broader commercial real estate allocations offer. Post office real estate is most appropriately sized as a yield-enhancing component within a diversified income strategy rather than as a standalone position within a broader portfolio.
What Investors Evaluating Post Office Real Estate for Sale Should Take Away
The market for post office real estate for sale has matured into a transaction environment that rewards investors who approach it with accurate information, sector-specific knowledge, and realistic expectations about both the income opportunity and the risks that accompany it. The combination of federal tenancy, essential-service infrastructure, long-term lease income visibility, and an increasingly professional buyer pool creates conditions that are more favorable for informed participants than at any prior point in this sector's development.
The risks are real and must be underwritten with rigor rather than dismissed on the basis of the government tenant label. Lease termination provisions, agency financial condition, and concentration risk all belong in any honest evaluation of this category. For income-focused allocators building portfolios around durable, government-supported cash flow, however, post office real estate for sale has earned a place in the research process that it did not occupy even a decade ago.
Investors who want to examine this market in depth, including portfolio details, featured property listings, and acquisition process documentation, can begin their research at postalrealtytrust