Philippines Digital Payments Market Size, Share, Trends, Growth & Forecast Report 2026-2034
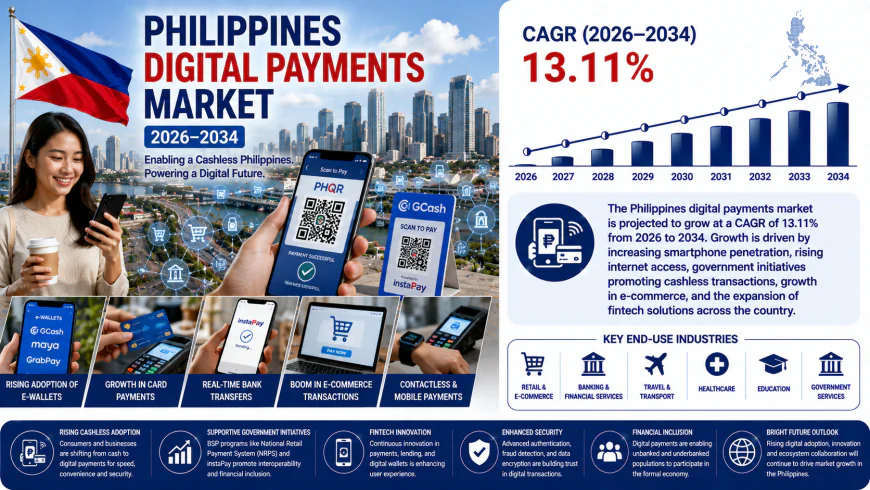
The Philippines digital payments market size reached USD 616.3 Million in 2025. Looking forward, the market is expected to reach USD 1,867.6 Million by 2034, exhibiting a growth rate (CAGR) of 13.11% during 2026-2034.
 Arlo Bennett
Market Overview
The Philippines digital payments market size reached USD 616.3 Million in 2025 and is projected to reach USD 1,867.6 Million by 2034, growing at a compound annual growth rate (CAGR) of 13.11% from 2026 to 2034 . The market is driven by rising smartphone and internet penetration, government financial inclusion programs, rapid e-wallet adoption, increasing integration of QR code transactions in retail, expansion of e-commerce and social commerce platforms, and growing consumer preference for contactless and secure payments .
Request a Sample Report for In-Depth Market Insights: https://www.imarcgroup.com/philippines-digital-payments-market/requestsample
Philippines Digital Payments Market Summary
-
The Philippines digital payments market encompasses a range of solutions and services, including payment gateways, payment security, fraud management, professional services, and managed services, serving BFSI, retail and e-commerce, IT and telecom, healthcare, media and entertainment, transportation, and other end-use industries .
-
These solutions are valued for their role in enabling seamless transactions, supporting financial inclusion, enhancing payment security, and facilitating e-commerce and digital commerce across the archipelago.
-
The ecosystem includes payment service providers, banks, fintech companies, e-wallet operators, telecom companies, merchants, and regulatory bodies including the Bangko Sentral ng Pilipinas (BSP).
-
Major segments identified in the market include component (solutions, services), payment mode (bank cards, digital wallets, digital currencies, net banking, others), deployment type (cloud-based, on-premises), end use industry (BFSI, retail and e-commerce, IT and telecom, healthcare, media and entertainment, transportation, others), and region (Luzon, Visayas, Mindanao) .
-
The market is benefiting from the widespread adoption of digital wallets, growing use of QR Ph and real-time payment systems like InstaPay and PESONet, expansion of buy-now-pay-later (BNPL) services, and government initiatives promoting financial inclusion .
-
According to the Bangko Sentral ng Pilipinas (BSP), digital payments accounted for 64.7% of the total volume of retail payments in 2025, surpassing the 60%-70% target under the Philippine Development Plan for 2023-2028 .
Porter's Five Forces Analysis
-
Competitive Rivalry: High, with major e-wallet platforms including GCash and Maya, traditional banks, fintech startups, and international payment providers competing on price, convenience, security, and ecosystem breadth . Business implication: Providers must differentiate through user experience, merchant acceptance, and value-added financial services.
-
Supplier Power (Payment Infrastructure and Technology Providers): Moderate. Suppliers of payment gateways, security systems, and cloud infrastructure have some leverage, but the presence of multiple suppliers and the ability of large platforms to negotiate contracts moderates this power. Business implication: Payment providers should maintain diverse technology partnerships and invest in proprietary capabilities.
-
Buyer Power (Consumers and Merchants): High. Consumers and merchants have extensive choice across payment methods and platforms, with growing awareness of fees, convenience, and security. Business implication: Providers must focus on affordability, reliability, and user experience to build loyalty.
-
Threat of Substitutes: Moderate. Cash-on-delivery, traditional bank transfers, and informal payment methods compete, but the convenience, speed, and security of digital payments support their growing adoption . Business implication: The industry should emphasize convenience, security, and interoperability.
-
Threat of New Entrants: Moderate. Higher barriers for established players (network effects, user base, merchant networks), but lower barriers for fintech and niche entrants following the lifting of the moratorium on new non-bank EMI licenses . Business implication: Established players should build defensible positions through scale, ecosystem breadth, and merchant relationships.
Market Growth Drivers
Rising Smartphone and Internet Penetration
The Philippines digital payments market size is growing rapidly thanks to the widespread use of smartphones and better internet infrastructure. Digital wallets have become common, offering easy services such as peer-to-peer transfers, bill payments, and e-commerce transactions across the country . The Philippines smartphone market size reached USD 563.5 Million in 2025, with projections to reach USD 588.1 Million by 2034, supporting broader access to digital payment applications among mass-market consumers . Affordable mobile devices and competitive data plans are democratizing access to financial applications, while younger generations entering the workforce demonstrate strong preferences for mobile-first financial services.
Government Financial Inclusion Programs and Digital Payments Roadmaps
The Philippine government's commitment to financial inclusion is creating unprecedented opportunities for digital payment expansion across underserved populations. National strategies targeting increased account ownership and digital transaction adoption are driving coordinated efforts between public and private sector stakeholders . The Bangko Sentral ng Pilipinas (BSP) has implemented policies including Circular No. 1238, which pushes for reasonable transfer fees, requiring that charges for sending funds from one bank or e-wallet provider to a different financial institution should not be materially different from those made within the same institution . These regulatory frameworks are making electronic payments more accessible and affordable for consumers and businesses across the archipelago.
Rapid E-Wallet Adoption and Mobile Banking Usage
Digital wallets take the lead in the Philippines, accounting for an estimated 28% (USD 5.6 billion) of total e-commerce transactions in 2026, with this share projected to rise to 31% (USD 8.68 billion) by 2029 . GCash stands as the most crucial option in the market, commanding a staggering 89% of the domestic wallet share, having transformed into a household superapp with over 94 million users in 2025 . The growth of mobile banking and e-wallet adoption is supported by 2.47 billion QR Ph transactions worth PHP 1.16 trillion processed during 2025, reflecting a growing preference for interoperable, account-based payments .
Integration of Real-Time Payments and QR Code Transactions
Real-time fund transfer services like InstaPay and PESONet are improving transaction speed and convenience across the Philippines. At end-2025, the total value of transactions made via InstaPay and PESONet surged by 42.02% to PHP 24.745 trillion from PHP 17.423 trillion at end-2024 . The widespread adoption of QR Ph, the National QR Code Standard, has received extensive acceptance, enabling secure transactions based on the EMV standard across participating banks and non-bank electronic money issuers . The Paleng-QR Ph project, initiated by the BSP, promotes digital payments in public markets, educating local government units and stakeholders about digital payments and financial consumer protection .
Expansion of E-Commerce and Social Commerce Platforms
E-commerce platforms and popular social media apps are increasingly offering digital payment options, making them more accessible to consumers across the Philippines. The growth of buy-now-pay-later (BNPL) services is attracting more consumers, with the Philippines ranking third in Southeast Asia for BNPL adoption . New fintech startups, along with established payment providers, are launching new features and partnerships to capture growing demand. For example, Rakuten Viber has introduced Viber Pay to handle in-app peer-to-peer and business transactions, aiming to simplify payments for micro, small, and medium enterprises . The increasing e-commerce penetration is driving demand for dependable digital payment solutions that offer convenience, security, and seamless checkout experiences.
Philippines Digital Payments Market Segmentation
Component Insights:
-
Solutions (Payment Gateways, Payment Security, Fraud Management, etc.)
-
Services (Professional Services, Managed Services)
Payment Mode Insights:
-
Bank Cards
-
Digital Wallets
-
Digital Currencies
-
Net Banking
-
Others
Deployment Type Insights:
-
Cloud-Based
-
On-Premises
End Use Industry Insights:
-
BFSI
-
Retail and E-Commerce
-
IT and Telecom
-
Healthcare
-
Media and Entertainment
-
Transportation
-
Others
Regional Insights:
-
Luzon
-
Visayas
-
Mindanao
Competitive Landscape
The Philippines digital payments market features a competitive landscape encompassing e-wallet platforms, traditional banks, fintech companies, and international payment providers. Market participants differentiate through user experience, merchant acceptance, security features, and ecosystem breadth. The competitive environment is characterised by a shift from user-acquisition-led competition toward transaction depth, merchant acceptance, and cross-border monetization . Partnerships are becoming the main competitive tool, with players like GCash partnering with the Philippine Statistics Authority to colocate mobile wallet account opening with National ID registration activities, and with Alipay+ and Mastercard for global NFC acceptance . Maya's partnership with Atome reflects a broader move into embedded credit services . The competitive analysis includes market structure, key player positioning, top winning strategies, competitive dashboard, and company evaluation quadrant, with detailed profiles of all major companies provided in the report.
Key players mentioned in the report's context include:
-
GCash stands as the most crucial digital wallet option in the Philippines, commanding 89% of the domestic wallet share with over 94 million users in 2025. The platform has partnered with the Philippine Statistics Authority for wallet account opening during National ID registration, and with Alipay+ and Mastercard for global NFC acceptance .
-
Maya is a strong challenger in the digital payments market, linking payments with digital banking and credit. Maya Bank and Atome entered a US$48 million consumer financing partnership to expand access to flexible credit at checkout .
-
Rakuten Viber introduced Viber Pay to handle in-app peer-to-peer and business transactions, aiming to simplify payments for micro, small, and medium enterprises .
-
Thunes launched a new relationship with GCash in November 2024, allowing GCash users to top up their wallet balances directly within the app with funds from UK and European bank accounts .
Regional Analysis
-
Luzon: The dominant region driven by Metro Manila's high concentration of digitally connected consumers, banks, corporates, and government agencies. Luzon accounts for the largest share of digital payment demand, supported by high smartphone penetration, improving broadband coverage, and greater financial literacy among urban and peri-urban populations. A large base of micro, small, and medium enterprises increasingly relies on fintech platforms for payments, credit access, payroll, and working capital management .
-
Visayas: A growing market driven by increasing urbanization, expanding digital infrastructure, and rising adoption of digital payment solutions across Cebu, Iloilo, and other major urban centers. The region is emerging as a hub for fintech adoption beyond Metro Manila, supported by improving retail infrastructure and growing merchant acceptance.
-
Mindanao: An emerging market with growing digital payments demand, supported by improving internet connectivity, increasing financial inclusion efforts, and growing adoption of digital wallets and QR code payments in Davao and other regional centers. The region presents significant long-term potential as infrastructure and digital literacy continue to improve.
Recent Industry Developments
October 2026: Mynt, the parent company of GCash, priced its IPO at PHP6.60 per share, targeting approximately PHP53 billion in proceeds. The offering received strong demand from international and domestic institutional investors, with funds expected to support the expansion of GCash’s digital financial services and product development.
August 2026: Digital payments accounted for 64.7% of total retail payment volume in 2025, up from 57.4% in 2024, according to the Bangko Sentral ng Pilipinas. The result exceeded the government’s 60% to 70% digital-payment target range under the Philippine Development Plan.
August 2026: Combined transaction values through PESONet and InstaPay reached PHP19.16 trillion during January to July 2026, up 45% year-on-year. Transaction volume more than doubled to 4.98 billion, reflecting accelerating adoption of electronic fund transfers across consumers and businesses.
August 2026: Apple Pay officially launched in the Philippines, enabling payments through iPhone, Apple Watch, iPad and Mac. The service became available across thousands of participating in-store and online merchants, supported by major Philippine banks and card networks, adding another international payment platform to the country's expanding digital ecosystem.
July 2026: The BSP and Philippine Payments Management, Inc. launched Direct Debit PH, InstaPay Cash-In and InstaPay for Business. The business service increased the maximum registered-business transfer limit 10-fold, from PHP50,000 to PHP500,000, while the new services aim to improve interoperability, convenience and financial inclusion.
Key Aspects Required for the Philippines Digital Payments Market
-
Market Performance: USD 616.3 Million in 2025, with a projected trajectory to USD 1,867.6 Million by 2034 .
-
Market Outlook: A 13.11% CAGR through 2034 indicates robust growth across components, payment modes, deployment types, end-use industries, and regions, driven by smartphone penetration, government financial inclusion programs, e-wallet adoption, and real-time payment integration .
-
Growth Drivers: Rising smartphone and internet penetration; government financial inclusion programs and digital payments roadmaps; rapid e-wallet adoption and mobile banking usage; integration of real-time payments and QR code transactions in retail; expansion of e-commerce and social commerce platforms; and increasing consumer preferences for contactless and secure payments .
-
Competitive Landscape: A competitive market with e-wallet platforms, traditional banks, fintech companies, and international payment providers. Differentiation occurs through user experience, merchant acceptance, security features, and ecosystem breadth.
-
Value Chain Analysis: From payment gateway and security solution development through deployment and merchant integration to end-use by consumers and businesses across diverse industries, with digitalisation and financial inclusion trends shaping market dynamics.
-
Industry Trends: Rapid e-wallet adoption; growth of QR Ph and real-time payment systems; expansion of BNPL services; increasing focus on interoperability; and growing adoption of digital payments in public transport and utility payments .
-
Strategic Recommendations: Invest in payment security and fraud management capabilities; expand merchant acceptance networks; develop interoperable payment solutions; leverage government financial inclusion initiatives; and focus on user experience and ecosystem breadth to capture growing demand.
Note: If you need any specific information that is not currently covered within the scope of the report, we will provide the same as a part of customization.
Speak to an analyst: https://www.imarcgroup.com/request?type=report&id=28731&flag=C
Report Format, Delivery, and Customization Details
-
Report Format Mode: PDF and Excel (Editable version in PPT/Word format available on special request)
-
Report Delivery Mode: Online Delivery, Physical Delivery
-
Report Delivery Time: The report is delivered over email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
-
Report Confirmation Mode: Yes, via email
-
Report Customization Mode: Yes, via Email / Call
-
Report Table of Content: Yes
-
Report List of Figures: Yes
-
Report Methodology Mode: Yes
-
Request For Sample Report: Yes