GCC Car Rental Market Expansion: Industry Drivers & Investment Outlook 2026-2034
GCC car rental market size was valued at USD 1.81 Billion in 2025, expected to reach USD 4.03 Billion at a CAGR of 9.31% during 2026-2034.
 jackleen jackleen
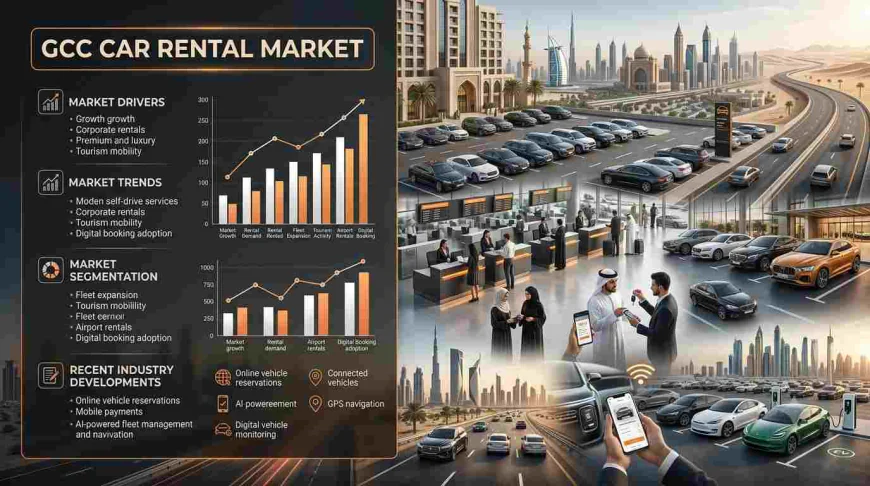
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the GCC Car Rental Market. The GCC car rental market size reached USD 1.81 Billion in 2025 and is projected to reach USD 4.03 Billion by 2034, exhibiting a CAGR of 9.31% during 2026-2034. Growth is being driven by surging inbound tourism, expanding expatriate populations, robust business travel demand, and the rapid adoption of digital booking platforms.
Car rental remains one of the most essential mobility services across the GCC, underpinning everything from Hajj and Umrah ground transport and airport transfers to long-term corporate fleets serving giga-project construction. With no fully integrated public transit network across several GCC cities, self-drive and chauffeur-driven rentals are a core mobility solution for both residents and visitors. As Gulf governments push ahead with tourism programs such as Saudi Vision 2030's target of 150 million tourist visits, regional demand for short-term, long-term, and subscription-based rentals is climbing steadily across Saudi Arabia, the UAE, Qatar, Kuwait, Oman, and Bahrain. At the same time, operators are investing heavily in AI-driven dynamic pricing, telematics, keyless vehicle access, and electric fleets, positioning the region as an early adopter of mobility-as-a-service models. Combined with strong government backing through infrastructure investment and fleet modernization programs, these forces are reshaping the competitive landscape and setting the stage for durable, long-term growth.
GCC Car Rental Market at a Glance:
- Market Size (2025): USD 1.81 Billion
- Market Forecast (2034): USD 4.03 Billion
- Growth Rate (2026-2034): CAGR of 9.31%
- Base Year: 2025 | Historical Period: 2020-2025 | Forecast Period: 2026-2034
- Leading Booking Type: Online Booking, at 71.2% share in 2025, supported by smartphone penetration above 98% in Saudi Arabia and the rise of super-apps such as Careem
- Leading Country Market: Saudi Arabia, commanding 42.6% of GCC revenue in 2025, backed by Vision 2030 tourism ambitions, the Hajj and Umrah travel cycle, and giga-project activity
How AI is Reshaping the Future of the GCC Car Rental Market
- AI-Driven Dynamic Pricing and Fleet Management: Machine learning platforms process seasonal tourism surges, corporate booking patterns, vehicle availability, and competitive rate benchmarks to set dynamic prices that maximize revenue per vehicle per day, with Hertz introducing AI-based dynamic pricing in its GCC operations.
- Predictive Maintenance and Idle Asset Reduction: AI-driven predictive maintenance can cut equipment downtime by up to 50% and extend machine life by 20-40%, while AI fleet optimization platforms reduce idle asset ratios from an industry average of 32% to approximately 20%, releasing around 12% of fleet capital for yield-generating deployment.
- Telematics, IoT and Keyless Digital Access: Saudi Arabia's Transport General Authority recorded a 31% rise in digital vehicle registrations in 2024, accelerating deployment of AI platforms that ingest government data alongside operator analytics, while NFC digital keys and QR-code unlock protocols let customers verify identity, pay, and unlock vehicles in a single workflow, trimming average check-in times to under four minutes.
Grab a sample PDF of this report: https://www.imarcgroup.com/gcc-car-rental-market/requestsample
GCC Car Rental Market Trends and Drivers:
Demand for car rental across the GCC is being underpinned by rising tourism and religious travel. Over 9.31 Million tourists visited Dubai in the first half of 2024, an increase of more than 8.9% year on year, while Saudi Arabia hosted 18.5 Million Hajj and Umrah pilgrims in 2024, generating sustained ground transport demand between Mecca, Medina, and Jeddah.
The market's structural differentiator is its large and transient expatriate workforce. Expatriates constitute 88% of the UAE's population in 2025, equal to approximately 9.2 Million foreign residents, and frequent job-linked relocations generate sustained demand for monthly and long-term rental contracts, with all-inclusive subscription rentals increasingly displacing ownership among expatriates and corporate clients.
A third driver is business travel and infrastructure development. The Middle East business travel market was projected to grow 11.2% in 2024, benefiting executive and chauffeur-driven rentals amid rising MICE activity in Riyadh, Dubai, and Doha, while more than USD 1.5 Trillion in planned infrastructure projects through 2035 is producing modern road networks and airport terminals with embedded rental desks, a dynamic that is set to intensify over the coming decade.
Government Schemes and National Vision Initiatives Driving Demand:
- Transport General Authority Telematics Subsidy Program: Saudi Arabia's Transport General Authority offers subsidies for telematics installation under its national fleet modernization program, allowing mid-sized operators to access connected-vehicle infrastructure at commercially viable cost points.
- UAE Net Zero 2050 and Saudi Green Initiative: Both programs are supporting charging network expansion and fleet electrification, with EV fleet adoption below 5% of GCC rental inventory in 2025 but expected to reach 18-22% by 2030, creating an estimated incremental revenue opportunity of USD 320 Million.
- Oman Vision 2040 and Qatar National Tourism Targets: Oman's eco-tourism target of 11 million visitors by 2040 and Qatar's goal of 6 million annual visitors by 2030 are creating latent demand for self-drive rentals in two of the region's smaller markets.
- Giga-Project Corporate Mobility Demand: Construction activity across NEOM, the Red Sea Project, and Diriyah Gate is the primary growth engine for long-term rentals and corporate subscription services, which are growing at an estimated 14% CAGR.
GCC Car Rental Market Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Booking Type:
- Offline Booking
- Online Booking
Online booking dominates with a 71.2% share in 2025 and is the fastest-growing channel at approximately 10.8% CAGR through 2034, while offline booking retains a 28.8% share by serving airport walk-in customers and SMEs with negotiated contracts.
Breakup By Rental Length:
- Short Term
- Long Term
Short-term rentals lead with a 66.3% share in 2025, reflecting 5 to 7 day average tourist stays, while long-term rentals of one month and above account for 33.7% and are growing at approximately 7.8% CAGR.
Breakup By Vehicle Type:
- Luxury
- Executive
- Economy
- SUVs
- Others
SUVs lead the vehicle type segment with a 42.4% share in 2025, favored for family travel, desert terrain, and pilgrim group transport across the GCC.
Breakup By Application:
- Leisure/Tourism
- Business
Leisure and tourism accounts for 68.5% of demand in 2025, while business travel represents roughly 38% of rental demand in the broader market context and favors daily or weekly contracts.
Breakup By End-User:
- Self-Driven
- Chauffeur-Driven
Self-driven rentals lead with a 60.4% share in 2025, while the chauffeur-driven segment faces a skilled driver deficit estimated at 15-20% of required headcount across Saudi Arabia and the UAE.
Breakup By Country:
- Saudi Arabia
- UAE
- Qatar
- Bahrain
- Kuwait
- Oman
Saudi Arabia leads at 42.6%, followed by the UAE (24.8%), Qatar (10.6%), Kuwait (8.7%), Oman (7.1%), and Bahrain (6.2%), with the UAE commanding the highest revenue per rental day at an estimated USD 55-80.
Competitive Landscape:
The GCC car rental market is moderately concentrated, with a mix of global rental brands and regional operators competing on fleet size, digital capability, and geographic coverage. Key players include:
- Enterprise Holdings, Inc.
- The Hertz Corporation
- Sixt
- Budget Rent A Car
- Al Sulaiman Rent-A-Car
Enterprise Holdings, the world's largest car rental company with 2.3 million vehicles globally, has introduced 500-plus EV units to its UAE fleet, while Sixt has targeted the premium and digital-native segment with an Arabic-language app and a first Saudi Arabia location opened in 2022, and Hertz is pursuing premiumization through its Prestige Collection and AI-powered predictive fleet management.
Market Concentration Analysis:
- The top players collectively account for an estimated 65-70% of GCC car rental revenue in 2025, driven by the high capital intensity of fleet procurement, with a top-tier operator holding 10,000 to 50,000 vehicles and creating significant barriers to entry.
- Fragmentation is most evident at the city and country level, where dozens of independent operators compete for SME and tourist demand, while mid-tier regional operators such as Al-Futtaim rely on local relationships and government fleet contracts.
- Consolidation is ongoing, with three significant M&A transactions involving GCC fleet operators recorded between 2022 and 2024, while digital aggregators such as Rentalcars.com are accelerating price transparency and compressing margins for smaller operators.
What Does The Full Report Cover?
- Historical, current, and forecast market size for the GCC car rental market from 2020 to 2034
- Market breakup by booking type, rental length, vehicle type, application, end-user, and country
- Country-level analysis covering Saudi Arabia, UAE, Qatar, Bahrain, Kuwait, and Oman
- Key growth drivers, restraints, and opportunities shaping the market
- Porter's Five Forces analysis and value chain assessment
- Competitive landscape, market structure, and player positioning
- Detailed profiles of major regional and international car rental companies
Recent News and Developments in the GCC Car Rental Market
- September 2026: ART Elite Car Rental partners with SelfDrive Mobility to expand long-term vehicle leasing in the UAE through a dealer-led digital platform, offering 12- and 24-month leases on JETOUR and SOUEAST SUVs via app, AI and web channels, with 100 vehicles pre-booked in August and a target of more than 50 monthly bookings toward a 3,000-car portfolio.
- June 2026: British technology platform Final Rentals partners with AUTORENT, gaining access to a fleet of more than 13,000 vehicles across the UAE, Saudi Arabia, Bahrain and Oman to accelerate digital bookings in the Gulf.
- August 2026: Thrifty Car Rental UAE signs an exclusive five-year partnership with Etihad Rail to launch the region’s first rail-to-road car rental service, providing digital kiosks and assistance desks at passenger stations with an initial dedicated fleet of around 500 vehicles bookable via the Etihad Rail app and website.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
- How big is the GCC car rental market and what is its growth outlook through 2034?
- What are the key growth drivers, restraints, and opportunities in the GCC car rental market?
- Which booking type and rental length segments hold the largest share of the market?
- What is the breakup of the market by vehicle type, application, and end-user?
- Which country leads the GCC car rental market, and why?
- Who are the key players in the GCC car rental market, and how is the competitive landscape evolving?
- What role is AI and electric fleet adoption playing in the future of GCC car rental?
About Us
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: [email protected]
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104