Network-Attached Storage Market Size, Share, Trends & Forecast 2026-2034
The global network-attached storage market size reached USD 47.9 Billion in 2025. Looking forward, IMARC Group expects the market to reach USD 153.1 Billion by 2034, exhibiting a growth rate (CAGR) of 13.78% during 2026-2034.
 ashish kumar
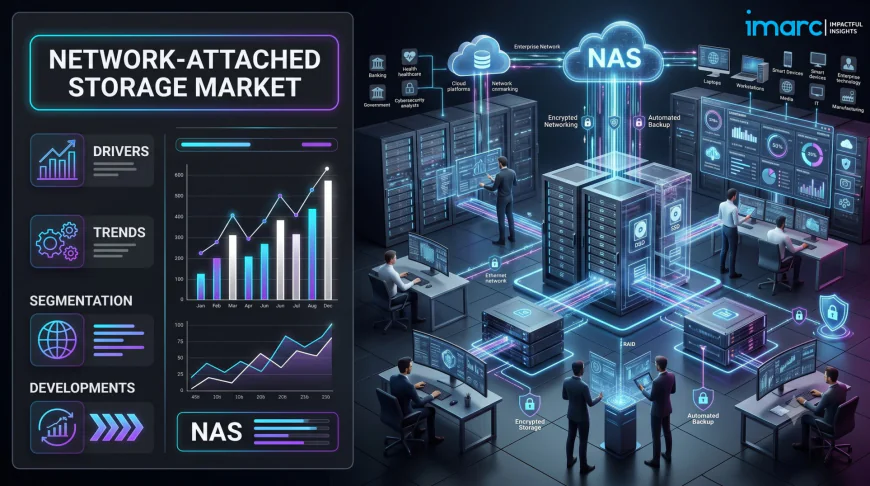
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the Network Attached Storage Market. The global network-attached storage market size reached USD 47.9 Billion in 2025. Looking forward, IMARC Group expects the market to reach USD 153.1 Billion by 2034, exhibiting a growth rate (CAGR) of 13.78% during 2026-2034, supported by rapid digitalization, rising penetration of wireless communication technologies, growing adoption of NAS systems among small and medium enterprises, and the increasing volume of sensitive data that organizations need to store securely and access remotely.
Network Attached Storage Market at a Glance
- Market Size: Valued at USD 47.9 Billion
- Projected Size: Expected to reach USD 153.1 Billion
- Growth Rate 2026-2034: CAGR of 13.78%
- Storage Architecture: Scale-Up NAS continues to lead adoption, favored by enterprises for vertically scalable, centrally managed storage capacity
- Deployment Trend: Hybrid deployment is gaining ground as organizations balance data sovereignty with cloud scalability
- Leading End-Use Vertical: IT and Telecommunications represents one of the largest and fastest-growing end-use segments
- Dominant Region: North America leads regional adoption, supported by advanced IT infrastructure and strong enterprise demand
How AI Is Reshaping the Network Attached Storage Market
- AI-Ready Data Pipelines: Storage vendors are re-engineering their platforms to support AI workloads directly. NetApp's enhancement of StorageGRID with improved performance and metadata management is aimed squarely at supporting AI data pipelines and enterprise AI training workflows.
- On-Premises AI Surveillance and Analytics: NAS is increasingly doubling as an AI inference layer at the edge. Synology's launch of the DVA7400, an enterprise-scale AI surveillance appliance built on its NAS hardware, brings deep learning video analytics fully on-premises rather than routing data through the cloud.
- Unified File and Object Storage for AI Workloads: Hardware vendors are collapsing the line between file and object storage to serve AI use cases. Hewlett Packard Enterprise's enhancement of its Alletra Storage MP X10000 platform with unified file and object storage capabilities reflects this shift toward flexible, AI-friendly data architectures.
Grab a sample copy of this report: https://www.imarcgroup.com/network-attached-storage-market/requestsample
Network Attached Storage Market Trends and Drivers
The rising volume of sensitive data being generated across banking, financial services, and insurance continues to be a foundational demand driver. As BFSI institutions store growing volumes of transactional and customer data, NAS systems are being adopted as a reasonably priced way to secure that data without compromising accessibility, particularly as fraud detection and compliance reporting increasingly rely on fast, centralized access to historical records.
A key structural differentiator shaping the market globally is the tightening of cloud portability and interoperability rules. The European Union's Data Act now requires cloud and data processing service providers to eliminate technical and contractual barriers that lock enterprises into a single provider, with switching charges being phased out entirely by January 2027. This regulatory push is prompting organizations to reassess how much of their data estate should sit in the cloud versus on-premises NAS, and industry analysts note that backup and long-term archive workloads in particular are becoming stronger candidates for on-premises secondary storage as exit costs stop distorting the buy-versus-cloud comparison.
The expansion of hyperscale and AI-driven data center capacity, particularly across Asia Pacific, is setting up sustained long-term demand for storage hardware. Government-backed digital infrastructure incentives are accelerating this build-out, and as more data centers come online, the underlying demand for scalable, secure, and increasingly AI-integrated storage systems continues to widen across both enterprise and hyperscale deployments.
Global Regulatory and Trade Landscape Shaping Demand
- EU Data Act, Cloud Switching and Interoperability: Core provisions became applicable in September 2025, requiring cloud and data processing providers to support functional equivalence during switching, publish open interfaces, and eliminate all switching fees by January 2027.
- EU Data Act, Data Sovereignty Provisions: Providers must disclose the jurisdiction governing their ICT infrastructure and the measures in place to prevent unauthorized international government access to data held in the EU, directly affecting how multinational enterprises architect their storage footprint.
- US Advanced Manufacturing Investment Tax Credit: The 35 percent investment tax credit for semiconductor and storage-related manufacturing equipment applies only to projects that begin fabrication construction before the end of 2026, shaping near-term capital investment decisions across the storage hardware supply chain.
- India MeitY Data Centre Notification Framework: Data centres notified under India's Ministry of Electronics and Information Technology now qualify for infrastructure financing status, directly supporting the buildout of storage-heavy data center capacity across the country.
Key Government Schemes and Policy Programs Supporting the Industry
- India, Union Budget Tax Holiday for Data Centres: The Union Budget introduced a tax holiday running until 2047 for eligible foreign cloud service providers using India-based data centre infrastructure to serve customers outside the country, a long-horizon incentive designed to attract global storage and cloud infrastructure investment.
- India, Electronics Components Manufacturing Scheme (ECMS): Budget allocation for the scheme was increased from roughly Rs 22,000 crore to Rs 40,000 crore, with 149 applications received, directly supporting domestic production of components used in storage and networking hardware.
- India, Gujarat Data Centre Policy: A new state-level policy came into effect in July 2026, offering long-term financial incentives and infrastructure support to data centre projects with a minimum approved IT load capacity of 150 MW, positioning the state as a hub for hyperscale storage infrastructure.
- United States, CHIPS and Science Act: The Department of Commerce had funded 19 semiconductor companies with USD 30.7 Billion in awards and USD 5.5 Billion in loans for 40 commercial fabrication projects, supporting the domestic supply chain for storage controllers and memory components.
- European Union, Data Act Cloud Market Reforms: By phasing out switching fees and mandating open interoperability specifications, the EU is actively reshaping the competitive dynamics of the cloud and storage services market across all member states.
Network Attached Storage Industry Segmentation
Breakup by Product Type
- High-End Enterprise NAS
- Midmarket NAS
- Low-End NAS
The report has categorized the market by product type to capture the differing needs of large enterprises, mid-sized businesses, and smaller organizations, with high-end enterprise systems typically deployed for mission-critical, high-availability workloads and midmarket and low-end systems serving cost-sensitive and small business use cases.
Breakup by Storage Solution
- Scale-Up
- Scale-Out
Scale-Up architecture remains a widely adopted approach, offering vertically scalable capacity with centralized management that suits enterprises with moderate to high but predictable storage growth, while Scale-Out architecture is gaining traction among organizations handling large, rapidly expanding unstructured data sets.
Breakup by Deployment Type
- On-premises
- Cloud-based
- Hybrid
Hybrid deployment continues to gain favor as organizations look to balance data sovereignty and latency-sensitive workloads with the scalability of cloud tiering and disaster recovery.
Breakup by End-Use Industry
- Banking, Financial Services, and Insurance (BFSI)
- Consumer Goods and Retail
- Telecommunications and IT
- Healthcare
- Energy
- Government
- Education and Research
- Media and Entertainment
- Others
Telecommunications and IT represents one of the largest end-use categories, reflecting the sector's need to manage network logs, virtualization files, and rapidly growing data volumes tied to 5G and cloud-adjacent infrastructure expansion.
Breakup by Region
- North America (United States, Canada)
- Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
- Europe (Germany, France, United Kingdom, Italy, Spain, Russia, Others)
- Latin America (Brazil, Mexico, Others)
- Middle East and Africa
North America continues to lead regional adoption, supported by advanced IT infrastructure, strong cloud computing adoption, and the concentration of major storage technology vendors, while Asia Pacific is expanding rapidly on the back of data center growth in China, India, and Japan.
Competitive Landscape
The market features a mix of established enterprise storage vendors and specialized NAS manufacturers, including:
- Buffalo Americas Inc.
- Dell Technologies Inc.
- Hewlett Packard Enterprise Company
- Hitachi Data Systems Corporation
- IBM Corporation
- NetApp Inc.
- Netgear Inc.
- QNAP Systems Inc.
- Seagate Technology Plc
- Synology Inc.
- Western Digital Corporation
Among leading players, Western Digital reported annual revenue of approximately USD 9.52 Billion with net income of USD 1.89 Billion, reflecting continued demand for its hard disk drive and storage systems portfolio. Synology, meanwhile, has been actively expanding at both ends of its product range, launching the DVA7400 AI surveillance appliance in July 2026 and introducing its DiskStation neo+ series in August 2026, positioned 20 to 30 percent below its recently repriced Plus lineup to defend its share among cost-sensitive business and prosumer buyers.
Market Concentration Analysis
- Fragmented Across Tiers: The broader enterprise storage market spans a wide range of players, from diversified technology giants like Dell, HPE, and IBM to specialized NAS manufacturers like Synology and QNAP, resulting in a competitive landscape that remains fragmented across enterprise, midmarket, and consumer tiers.
- Active Consolidation Through M&A: Larger firms are actively acquiring startups with capabilities in hyper-converged infrastructure, cloud-native storage, and AI-integrated data management to broaden their software and hardware portfolios, a trend expected to continue streamlining the competitive landscape over time.
- Premium Shifting to Software-Defined Storage: Private equity and strategic investors are increasingly targeting companies with recurring software revenue, storage automation capabilities, and ransomware-resistant platforms, suggesting that future market share gains will favor vendors with strong software-defined and AI-integrated capabilities over hardware-only players.
What Does The Full Report Cover?
- Historical and current market size across all major segments
- Detailed breakup by product type, storage solution, deployment type, and end-use industry
- Country-level analysis across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa
- Market drivers, restraints, and emerging opportunities
- Value chain analysis across the industry
- Competitive landscape with detailed company profiles
- Strategic recommendations for market entry and expansion
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
- What is the current size of the global network attached storage market?
- Which storage architecture, scale-up or scale-out, is more widely adopted?
- Which deployment type, on-premises, cloud-based, or hybrid, is gaining the most traction?
- Which end-use industry represents the largest demand for NAS solutions?
- Which region leads the global network attached storage market and why?
- How is artificial intelligence changing product development in the NAS industry?
- Who are the leading companies operating in the global network attached storage market?
About Us
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: [email protected]
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104