Latin America Fintech Market Size, Share, Report 2026-2034
Latin America's fintech market is set to grow from USD 17.5B to USD 54B by 2034. Explore financial inclusion, open banking, and opportunities.
 Ranjeet Sharma
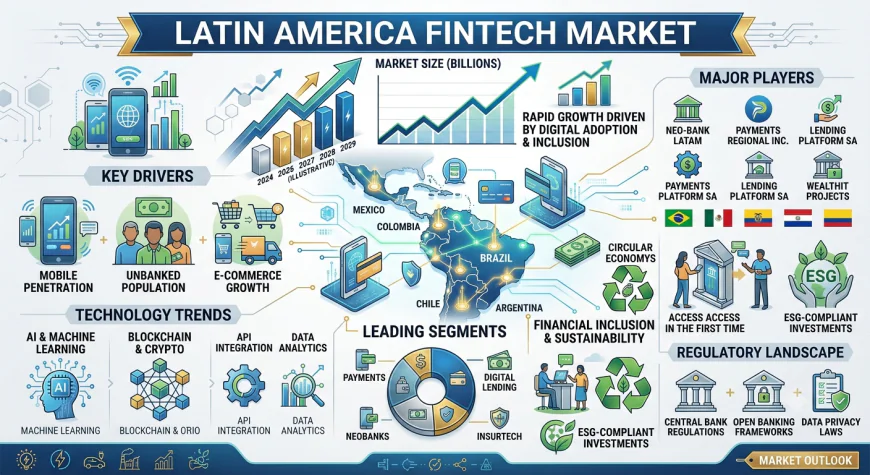
Latin American financial executives are confronting a paradox that has defined the region for generations. Millions of people remain excluded from traditional banking systems—unable to open accounts, access credit, or save securely—yet the same individuals increasingly carry sophisticated smartphones capable of processing complex financial transactions. This gap between technological capability and financial exclusion has created one of the world's most dynamic fintech ecosystems. From Brazil's PIX instant payment system to Mexico's digital wallets, technology is finally delivering what traditional banking could not. The Latin America fintech market sits at the centre of this transformation. Growing from USD 15.23 billion in 2025 to USD 17.53 billion in 2026, the market is projected to reach USD 54.01 billion by 2034, exhibiting a compound annual growth rate of 15.11 per cent during 2026-2034. These figures reflect an industry addressing longstanding barriers to financial access through technology-enabled solutions.
What's Driving Growth of Latin America's Fintech Market?
Financial inclusion imperatives are driving digital service adoption at scale. Latin America faces persistent banking exclusion challenges, with substantial populations lacking access due to geographic remoteness, documentation requirements, or minimum balance thresholds. Fintech platforms address these barriers through mobile-first service delivery, simplified account opening, and product designs accommodating irregular income patterns characteristic of informal economy participation. In 2025, the IDB Group introduced IDB Pay to accelerate real-time digital payment systems across the region, targeting the 30 per cent of the population that remains unbanked by 2030.
Cross-border remittance optimisation is creating sustained demand. Diaspora communities regularly transfer funds to family members across Latin America, and traditional channels imposed substantial costs through currency conversion fees and unfavourable exchange rates. Fintech solutions leveraging blockchain technology and digital currency bridges dramatically reduce transaction costs while accelerating transfer speeds from days to minutes. In 2025, dLocal and Félix revealed a collaboration providing instant remittance payouts in Mexico, Guatemala, Honduras, and El Salvador using stablecoin funding, with delivery generally taking less than two minutes and a success rate close to 99 per cent.
Smartphone penetration is exceeding banking infrastructure development. Mobile device adoption has accelerated throughout Latin America at rates substantially exceeding physical banking infrastructure expansion. In 2024, the smartphone market in Latin America increased by 15 per cent to reach 137 million units. This technological infrastructure enables fintech companies to reach consumers in areas underserved by traditional banking networks, delivering comprehensive financial services through mobile applications at dramatically reduced distribution costs.
Regulatory sandboxes are accelerating innovation cycles. Regulatory authorities across Latin America are establishing controlled testing environments that allow fintech companies to pilot innovative products without immediately complying with full regulatory requirements. This approach reduces barriers to market entry while maintaining consumer protection standards, encouraging experimentation with emerging technologies like decentralised finance protocols and embedded banking services.
Three Trends Reshaping the Industry
Open banking frameworks are reshaping financial data ecosystems.
Mandatory data-sharing initiatives are fundamentally altering competitive dynamics by requiring traditional banks to provide secure access to customer financial information through standardised interfaces. This regulatory shift empowers consumers to share their banking data with third-party providers, enabling personalised financial management tools and seamless account aggregation services. The transition creates opportunities for fintech companies to deliver superior user experiences while challenging incumbent institutions to differentiate through enhanced digital capabilities rather than data monopolisation.
Why it matters: Open banking dismantles the data monopolies that protected traditional banks from competition.
Business implication: Financial institutions must develop API infrastructure and partner strategies or risk disintermediation.
Future impact: A thriving ecosystem of third-party financial applications will emerge, delivering personalised services to millions of consumers.
Biometric authentication is enhancing security and enabling inclusion.
Financial technology providers are increasingly deploying facial recognition, fingerprint scanning, and voice authentication systems to strengthen identity verification processes and reduce fraud exposure. These biological identification methods address security concerns associated with password-based systems while improving user convenience. The adoption addresses regional challenges related to identity documentation gaps, enabling financial inclusion for populations lacking traditional identification credentials through alternative verification approaches. In 2025, Belvo launched Biometric Pix Payments to transform instant payments in Brazil.
Why it matters: Biometric authentication solves the identity verification challenge that has historically excluded undocumented populations from financial services.
Business implication: Fintech providers must invest in biometric capabilities to compete for underbanked customer segments.
Future impact: Universal financial identity will become achievable, enabling access to credit, savings, and insurance for millions currently excluded.
AI-driven transactions are transforming the payment experience.
In December 2025, Mastercard unveiled Agent Pay, a program designed to enable transparent, secure, and scalable AI-driven transactions across the payments ecosystem in Latin America and the Caribbean. The technology incorporates reliable payment experiences into personalised recommendations on conversational platforms, allowing digital agents to handle transactions and enhance purchasing experiences for users. This development signals a shift toward autonomous commerce where AI agents execute transactions on behalf of consumers.
Why it matters: AI-driven transactions represent the next frontier in payment convenience and personalisation.
Business implication: Payment providers must develop AI capabilities and conversational commerce strategies to remain competitive.
Future impact: Digital agents will become the primary interface for financial transactions, fundamentally changing how consumers interact with money.
What the Market Numbers Actually Tell Us
A market expanding from USD 15.23 billion to USD 54.01 billion over nine years suggests transformative commercial activity across fintech startups, traditional financial institutions, technology providers, and payment platforms. The 15.11 per cent compound annual growth rate signals one of the fastest-growing fintech markets globally. On-premises deployment dominates with a 35.01 per cent share, reflecting institutional preferences for maintaining direct control over sensitive financial infrastructure. Application programming interface leads the technology segment at 25.02 per cent, enabling seamless data exchange between traditional institutions and emerging fintech platforms. Payment and fund transfer represents the largest application segment at 45.05 per cent, driven by consumer demand for convenient digital payment alternatives. Banking exhibits clear dominance as an end user at 50.06 per cent, as traditional institutions accelerate digital transformation. Brazil leads the regional market, followed by Mexico, Argentina, Colombia, Chile, and Peru. For investors and industry participants, the trajectory indicates that fintech is fundamentally reshaping financial services delivery across the region.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of financial inclusion, cross-border payments, and emerging technologies. Brazil's PIX instant payment system exemplifies how government-backed digital infrastructure can accelerate fintech adoption, processing over three billion transactions monthly since launch. In 2025, Peru announced plans to launch a UPI-like real-time digital payments system. Prometeo unveiled its Borderless Banking service to facilitate business-to-business financial transactions between the US and Latin American markets. The market continues attracting substantial venture capital investment, enabling technology development and market expansion. Blockchain-based solutions addressing remittance inefficiencies, alternative credit scoring methodologies leveraging non-traditional data sources, and embedded finance platforms represent key growth vectors. Companies that can navigate the complex regulatory landscape, invest in security infrastructure, and develop products tailored to the region's unique needs are well-positioned to capture value in this rapidly evolving market.