How Recycled Fiber Packaging Is Reshaping the Global Kraft Paper Industry
Pharmaceutical applications are expected to achieve a CAGR of 6.2%, supported by demand for protective medicine packaging and sustainable secondary cartons.
 Eknath Girhepunje
The global kraft paper market covers strong, durable, and recyclable paper materials manufactured from wood pulp through the kraft pulping process. Products include bleached, unbleached, specialty, sack, and recycled kraft paper grades designed for different packaging requirements. Kraft paper is widely used in corrugated boxes, shopping bags, industrial sacks, wrapping materials, and protective packaging to support product safety and reduce dependence on conventional plastics.
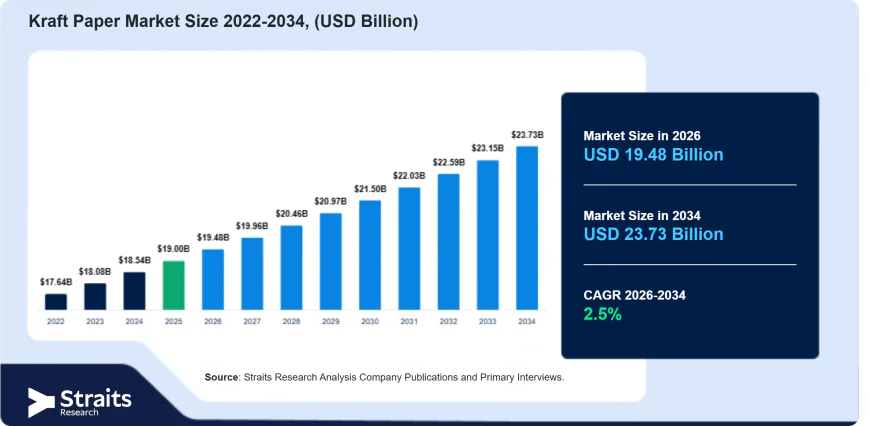
The global kraft paper market size was valued at USD 19 billion in 2025 and is projected to grow from USD 19.48 billion in 2026 to USD 23.73 billion by 2034, registering a CAGR of 2.5% during 2026–2034. Asia Pacific dominated the market with a 42% share in 2025, while North America is projected to record the fastest regional CAGR of 6.3%.
For detailed market insights, growth forecasts, and competitive analysis, visit:https://straitsresearch.com/report/kraft-paper-market
Kraft Paper Market Drivers
E-Commerce Packaging Requirements and Corrugated Box Production Drive Market
E-commerce retailers and logistics providers require durable packaging materials to protect products during storage and transportation. Kraft paper provides strength and flexibility for corrugated cartons, shipping envelopes, and protective wrapping. Online retail shipments of electronics, clothing, and household goods support demand for kraft-based packaging materials.
Replacement of Single-Use Plastic Packaging with Paper-Based Alternatives
Environmental regulations and corporate sustainability policies encourage businesses to replace selected single-use plastic packaging products. Retailers and packaging manufacturers use kraft paper bags, wrapping sheets, and recyclable packaging solutions to reduce dependence on conventional plastics. Adoption of paper-based alternatives supports kraft paper consumption across consumer goods and retail applications.
Industrial Packaging Requirements for Heavy-Duty Materials
Industrial manufacturers require strong packaging materials for cement, chemicals, and agricultural commodities. Sack kraft paper offers tensile strength and durability suitable for handling heavy products during storage and distribution. Continued demand for bulk packaging supports kraft paper procurement by industrial packaging converters.
Kraft Paper Market Trends
Use of PFAS-Free Grease-Resistant Coatings in Food-Grade Kraft Paper
The kraft paper market analysis shows that demand for safer food-contact packaging and chemical compliance encourages manufacturers to adopt PFAS-free grease-resistant coatings. Water-based polymers, bio-based coatings, and specialized surface treatments provide oil resistance while maintaining packaging flexibility. For instance, Ahlstrom offers PFAS-free grease-resistant paper solutions for bakery wraps and foodservice packaging.
Development of Wet-Strength Kraft Paper for Moisture-Exposed Packaging
Packaging requirements under humid conditions encourage manufacturers to develop wet-strength kraft paper grades. Specialized resins and fiber treatment processes improve cellulose bonding and help paper retain mechanical strength during moisture exposure. Enhanced durability supports packaging applications involving agricultural products, industrial sacks, and refrigerated goods.
Kraft Paper Market Segmentation
By Product
Specialty kraft paper is projected to record a CAGR of 5.9% during the forecast period, supported by demand for customized packaging, grease-resistant grades, and high-performance wrapping materials. Sack kraft paper is expected to grow at a CAGR of 5.1%, driven by its durability and suitability for cement, chemicals, and agricultural product packaging.
By Grade Type
Bleached kraft paper is expected to achieve a CAGR of 5.7% during the forecast period, supported by smooth surfaces, printing quality, and premium packaging applications. Unbleached kraft paper is projected to record a CAGR of 5.2%, supported by its strong fiber structure, natural appearance, and industrial packaging applications.
By Type
Virgin natural kraft paper accounted for a 34% market share in 2025, supported by high tensile strength and extensive use in heavy-duty packaging. Natural recycled kraft paper is projected to achieve a CAGR of 6.1%, driven by demand for recycled materials and efforts to reduce virgin fiber consumption.
By Packaging Form
Bags and pouches accounted for a 28% market share in 2025, supported by convenient handling and applications across food packaging, retail goods, and takeaway products. Cartons are projected to record a CAGR of 5.6%, driven by demand for recyclable secondary packaging and customized product protection.
By End User
Food & beverages accounted for a 39% market share in 2025, supported by extensive use of kraft paper in food wrapping, takeaway bags, and beverage carriers. Pharmaceutical applications are expected to achieve a CAGR of 6.2%, supported by demand for protective medicine packaging and sustainable secondary cartons.
Kraft Paper Market Regional Insights
North America Kraft Paper Market
North America is projected to register the fastest regional CAGR of 6.3% during 2026–2034. Recycled-fiber packaging solutions, specialized kraft grades, and industrial sack paper production support regional market development.
U.S. Kraft Paper Market
The U.S. offers recycled-fiber kraft packaging solutions through Smurfit Westrock's ReliaKraft portfolio. Recycled content and specialized wet-strength properties support the manufacture of grocery bags, agricultural packaging, and foodservice products. Packaging converters benefit from materials designed for commercial handling and sustainability requirements.
Canada Kraft Paper Market
Canada utilizes northern boreal forest fiber resources for sack paper production at Canadian Kraft Paper Industries' facility in The Pas, Manitoba. Extensible grades such as SPX and SPK provide tensile strength and flexibility for cement sacks and bulk commodity packaging. These properties support material optimization while maintaining load-bearing performance.
Asia Pacific Kraft Paper Market
Asia Pacific dominated the global kraft paper market with a 42% share in 2025. Established paper manufacturing facilities, integrated kraftliner production, and industrial packaging demand support regional market activity.
Japan Kraft Paper Market
Japan maintains specialized kraft paper manufacturing capabilities through Oji Holdings, which supplies unbleached, semi-bleached, and bleached grades. Machine-glazed surface treatments improve printability and appearance. These properties support applications in shopping bags, envelopes, and branded retail packaging.
China Kraft Paper Market
China operates large-scale kraftliner production facilities through Nine Dragons Paper, including its Shenyang manufacturing base. Integrated pulping infrastructure supports consistent production of virgin and conventional kraftliner grades. Corrugated packaging converters use these materials for shipping cartons and industrial transport packaging.
India Kraft Paper Market
India has established specialty paper manufacturing capabilities through Andhra Paper, which supplies plain and ribbed kraft grades. Different paper textures support production of pouches, envelopes, and converted packaging products. Domestic availability helps packaging manufacturers select suitable substrates for specific fabrication requirements.
Europe Kraft Paper Market
Europe is projected to record a CAGR of 4.9% during 2026–2034. Premium packaging papers, customized retail materials, and functional fiber-based barrier solutions influence regional market development.
U.K. Kraft Paper Market
The U.K. maintains specialized premium packaging paper capabilities through James Cropper, which manufactures luxury bag kraft and customized wrapping substrates. Bespoke color matching and tailored surface finishes support distinctive packaging designs. Premium retail brands use these materials for product presentation and brand differentiation.
Germany Kraft Paper Market
Germany is developing functional fiber-based packaging materials through Koehler Paper's NexFlex portfolio. Barrier-coated grades provide protection against grease, oxygen, and mineral oil migration. These properties support recyclable alternatives to conventional plastic laminates across food and consumer goods packaging.
Kraft Paper Market Competitive Landscape
The kraft paper market is moderately fragmented, with competition among integrated pulp and paper manufacturers, packaging material producers, specialty paper suppliers, and regional mills. Mondi Group, Holmen Board and Paper, and The Navigator Company are estimated to account for a cumulative market share of 10–15%. Competition focuses on paper strength, production efficiency, recycled fiber utilization, customized grades, sustainable sourcing, and distribution reliability.
Conclusion
The kraft paper market is supported by e-commerce packaging requirements, demand for recyclable materials, and industrial applications. Virgin natural kraft paper, bags and pouches, and food and beverage packaging represent major market segments, while recycled grades and pharmaceutical packaging offer growth opportunities. Asia Pacific maintains the largest regional share, whereas North America is projected to grow fastest. PFAS-free barrier technologies, wet-strength formulations, and sustainable fiber sourcing continue to influence packaging innovation.
About Us
Straits Research provides market intelligence, industry analysis, market forecasts, and competitive assessments across global industries. Its research helps organizations understand market dynamics, identify opportunities, and make informed strategic decisions.
Contact Us
Website: https://straitsresearch.com
Email: [email protected]
U.S.: +1 646 905 0080
India: +91 8087085354
U.K.: +44 203 695 0070