India Diagnostic Labs Market 2026–2034: Healthcare Demand, Diagnostic Trends & Expansion Opportunities
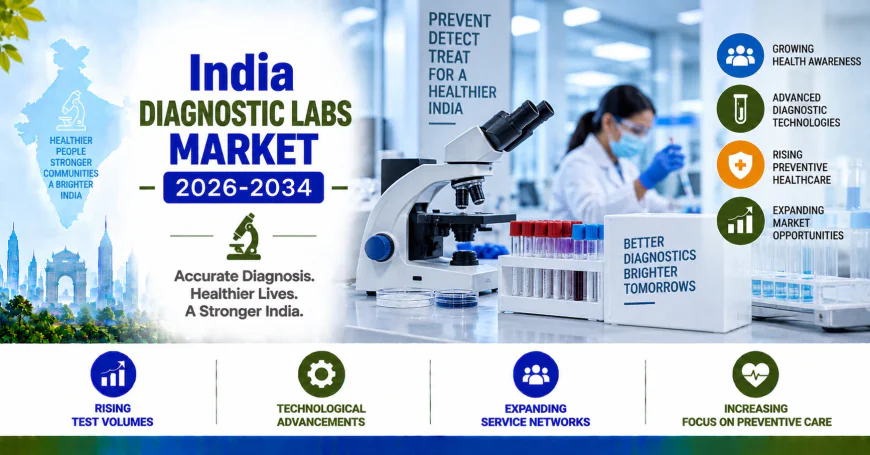
The India diagnostic labs market size was valued at USD 10.95 Billion in 2025 and is projected to reach USD 28.53 Billion by 2034 at 11.23% CAGR.
 chetan kalyan
India Diagnostic Labs Market Outlook
The market is expanding rapidly, driven by rising healthcare awareness, an escalating burden of chronic diseases, and accelerating technological advancement across the diagnostic ecosystem. Growing urbanization and rising disposable incomes have elevated consumer expectations for quality diagnostic services, while an expanding middle class demonstrates increasing willingness to invest in preventive healthcare screenings and wellness packages, strengthening the diagnostic labs market share in India.
Government initiatives, including Ayushman Bharat, alongside digital transformation through AI-powered diagnostics and home sample collection, are reshaping how diagnostic services are delivered across urban and rural India, creating a compelling structural growth environment through the forecast period.
Market Snapshot
- Market Size (2025): USD 10.95 Billion
- Forecast Market Size (2034): USD 28.53 Billion
- CAGR (2026–2034): 11.23%
- Leading Provider Type: Stand-Alone Labs
- Leading Test Type: Pathology
- Key Drivers: Chronic disease burden, government healthcare programs, digital transformation, insurance penetration
Evaluate Market Opportunity with the Business Sample Report
Key Market Drivers
- Rising Burden of Chronic and Lifestyle-Related Diseases:
The escalating prevalence of diabetes, cardiovascular conditions, cancer, and respiratory ailments is creating sustained demand for diagnostic testing across screening, progression monitoring, and treatment evaluation, with the aging population presenting compounding demand pressures for the number of diagnostic labs in India needed to serve them.
- Government Healthcare Initiatives and Digital Health Infrastructure:
The Ayushman Bharat Pradhan Mantri Jan Arogya Yojana provides health insurance coverage to over 50 Crore vulnerable citizens, while the Ayushman Bharat Digital Mission has enrolled over 67 crore citizens with ABHA health IDs, enabling seamless diagnostic record portability across facilities.
- Technology Adoption and Operational Efficiency Improvements:
Artificial intelligence is automating imaging analysis and pathology slide review, easing skilled-professional shortages while improving throughput. India's AI in medical diagnostics market reached USD 55.04 Million in 2024 and is projected to reach USD 546.95 Million by 2033, reflecting substantial technology investment reshaping the diagnostic labs market size in India.
- Expanding Insurance Penetration and Corporate Wellness Programs:
Rising health insurance coverage and employer-sponsored screening initiatives are broadening the consumer base for organized diagnostic chains beyond traditional physician-referral pathways.
Emerging Trends
- Digital Transformation and AI-Powered Diagnostics:
Cloud-based laboratory information systems and AI-powered digital pathology are enabling remote specialist consultations. In January 2026, Dr Lal PathLabs announced plans to launch "Sovaaka" preventive wellness centres integrating diagnostics with personalized digital health guidance.
- Home Sample Collection and Point-of-Care Testing Expansion:
Mobile sample collection networks are becoming mainstream. In December 2024, Orange Health Labs secured USD 12 Million from Amazon Smbhav Venture Fund to expand home collection capabilities and product innovation.
- Preventive Healthcare and Specialized Testing Growth:
Organized diagnostic chains are expanding into oncology, reproductive health, and autoimmune testing, supported by next-generation sequencing technologies enabling personalized medicine approaches.
- Consolidation Through Strategic Acquisitions:
In December 2024, Metropolis Healthcare acquired Core Diagnostics for approximately INR 246.8 Crores, strengthening its position across Northern and Eastern India and expanding cancer diagnostics capacity.
Market Challenges
Despite strong growth momentum, the India diagnostic labs market faces several structural headwinds:
- Limited rural healthcare infrastructure restricts diagnostic access, with only about 25% of populations in semi-rural and rural areas having nearby access to modern healthcare facilities
- India faces a critical shortage of qualified pathologists, microbiologists, and laboratory technicians, constraining service quality and capacity expansion, particularly outside urban centers
- Fragmented state-level regulatory oversight allows substandard operators to persist in underserved markets, affecting diagnostic accuracy and patient outcomes
- High operational costs and data-privacy concerns associated with digital transformation add compliance complexity for multi-state diagnostic networks
Segment Insights
By Provider Type
- Stand-Alone Labs (largest; accessible, cost-effective, appointment-free)
- Hospital Labs
- Diagnostic Chains (organized, accreditation-focused, expanding via acquisition)
By Test Type
- Pathology (largest; blood, urine, tissue diagnostics; routine and chronic-disease monitoring)
- Radiology
By Sector
- Urban (dominant; concentrated infrastructure, higher awareness, insurance penetration)
- Rural (underserved; expansion opportunity via hub-and-spoke models)
By End User
- Referrals (largest; physician-directed testing)
- Walk-ins
- Corporate Clients
Regional Insights
- North India — concentration of organized diagnostic chains, established infrastructure in Delhi-NCR, large population bases across Uttar Pradesh, Punjab, Haryana, and Rajasthan
- West and Central India — growing organized-sector penetration alongside industrial and urban expansion
- South India — strong physician-referral networks and specialty testing capacity
- East and Northeast India — emerging organized retail and expanding diagnostic access
Competitive Landscape
The India diagnostic labs market is characterized by intense competition among organized national chains, regional players, and hospital-based laboratories pursuing network expansion and service differentiation. Leading players are investing in advanced testing technologies, home-collection infrastructure, and digital platforms while pursuing acquisitions to consolidate market share from the fragmented unorganized sector that still accounts for a substantial share of the diagnostic labs market size in India.
Request Customized Data Tailored to Your Interest
Recent Developments
- January 2026 — Dr Lal PathLabs announced plans to launch "Sovaaka" preventive wellness centres combining diagnostics with digital health guidance
- April 2025 — Lupin Diagnostics announced that all 27 of its greenfield laboratories across India achieved NABL accreditation
Investment Opportunities
- Rural and Tier-2/3 Expansion: Hub-and-spoke models connecting urban reference laboratories to satellite collection centers present significant untapped potential given the low current density of diagnostic labs in rural India.
- AI-Enabled Digital Pathology: Investment in automated imaging analysis and teleradiology can address the professional shortage while improving turnaround times across networks.
- Specialized Testing Capacity: Oncology, genetic, and autoimmune testing represent high-value segments offering superior margins compared to routine pathology testing.
Frequently Asked Questions (FAQ)
- What is the diagnostic labs market size in India?
The India diagnostic labs market was valued at USD 10.95 Billion in 2025.
- What is the projected CAGR?
The market is projected to grow at a CAGR of 11.23% during 2026–2034, reaching USD 28.53 Billion by 2034.
- What is the diagnostic labs market share in India by provider type?
Stand-alone labs lead with a 42% share in 2025, owing to wide geographical presence and appointment-free accessibility.
- How many diagnostic labs are there in India?
While IMARC's report does not disclose an exact count, it notes that stand-alone labs, hospital labs, and organized diagnostic chains collectively serve a market where roughly 25% of rural populations have access to nearby modern facilities, underscoring the fragmented, high-volume nature of the number of diagnostic labs in India.
- Which segment leads by test type?
Pathology leads with a 65% share, driven by its central role in routine and chronic-disease diagnostic protocols.
Conclusion
India's diagnostic labs market is entering a sustained growth phase, propelled by a powerful combination of rising chronic-disease burden, government healthcare investment, and rapid digital transformation. Continued consolidation of the fragmented sector, alongside AI-enabled diagnostics and expanding insurance coverage, will define competitive positioning through 2034.
Diagnostic chains that invest in rural network expansion, digital pathology, and specialized testing capabilities will capture the largest share of the substantial incremental opportunity emerging across India's diagnostic labs market size through the forecast period.
Source: IMARC Group