Global Immunoassay Market Outlook: Advancing the Future of Disease Detection
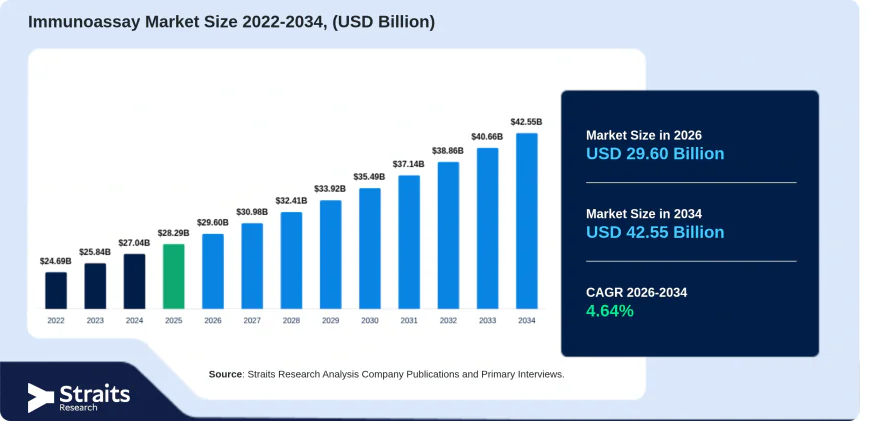
The global immunoassay market size was valued at USD 28.29 billion in 2025 and is projected to grow from USD 29.60 billion in 2026 to USD 42.55 billion by 2034, registering a CAGR of 4.64% during the forecast period (2026–2034).
 Aditi Jdv
Immunoassay Market
The global immunoassay market size was valued at USD 28.29 billion in 2025 and is projected to grow from USD 29.60 billion in 2026 to USD 42.55 billion by 2034, registering a CAGR of 4.64% during the forecast period (2026–2034). North America dominated the immunoassay market with a share of 39.5% in 2025. The market is witnessing steady growth due to the increasing prevalence of infectious and chronic diseases, rising demand for early disease detection, and continuous advancements in diagnostic technologies. Immunoassays are laboratory testing methods that use antigen-antibody interactions to identify and measure specific substances in biological samples, including blood, urine, and saliva.
The growing adoption of automated diagnostic systems and increasing demand for accurate laboratory testing are supporting the use of immunoassays across hospitals, clinical laboratories, and research facilities. These tests are widely used in infectious disease screening, hormone analysis, cancer diagnosis, cardiac testing, and autoimmune disorder detection. Additionally, improvements in rapid testing technologies and the increasing focus on personalized medicine are creating new opportunities for diagnostic manufacturers.
For detailed market insights, growth forecasts, and competitive analysis, visit: https://straitsresearch.com/report/immunoassay-market
Immunoassay Market Drivers
Increasing Prevalence of Infectious and Chronic Diseases
The rising prevalence of infectious and chronic diseases is a major factor driving the immunoassay market. Conditions such as HIV, hepatitis, influenza, diabetes, cardiovascular disorders, and cancer require accurate diagnostic testing for early detection and continuous monitoring. Immunoassays help healthcare professionals identify disease-associated biomarkers, antibodies, hormones, and antigens, supporting clinical decision-making.
The growing need for routine screening and disease monitoring is increasing testing volumes across hospitals and diagnostic laboratories. Immunoassay-based testing also supports the detection of infections and the assessment of treatment responses, making it an important component of modern diagnostic practices.
Advancements in Automated Diagnostic Technologies
Technological advancements in laboratory automation are supporting the adoption of immunoassay systems. Automated analyzers can process large sample volumes while improving testing consistency, turnaround times, and laboratory efficiency. These capabilities are particularly valuable for hospitals and reference laboratories handling high testing workloads.
Manufacturers are also introducing advanced detection technologies, improved assay sensitivity, and integrated laboratory platforms. The development of rapid immunoassay tests is further improving access to diagnostic services by enabling faster results in decentralized healthcare settings and point-of-care environments.
Immunoassay Market Challenges
High Costs of Advanced Diagnostic Equipment
The high initial cost of immunoassay analyzers and automated laboratory systems creates challenges for healthcare facilities, particularly smaller diagnostic laboratories and hospitals in developing economies. Advanced instruments require specialized installation, maintenance, calibration, and trained personnel, increasing overall operating expenses.
The recurring cost of reagents, testing kits, and other consumables can also affect laboratory budgets. These financial considerations may restrict the adoption of advanced immunoassay platforms in healthcare facilities with limited resources.
Risk of Testing Errors and Regulatory Complexity
Immunoassay results can be affected by cross-reactivity, sample interference, and variations in testing procedures. These factors may influence diagnostic accuracy and create challenges in interpreting results. Laboratories must follow standardized protocols and implement appropriate quality control measures to maintain testing reliability.
Additionally, diagnostic manufacturers must comply with regulatory requirements related to product safety, clinical performance, manufacturing, and quality assurance. Differences in regulatory frameworks across countries can increase product development costs and complicate international commercialization.
Immunoassay Market Segmentation
The immunoassay market is segmented by product, technology, specimen, application, and end user. Each category represents different diagnostic requirements and testing environments across the healthcare industry.
By Product
The reagents and kits segment dominated the market with a 61.8% share in 2025. These products are essential for conducting immunoassay tests and are regularly consumed across hospitals, clinical laboratories, and research facilities. Increasing diagnostic testing volumes and the recurring requirement for testing materials support the segment's leading position.
Analyzers represent another important product category, providing the equipment required to process and evaluate biological samples. Software and services support instrument management, data interpretation, system integration, and laboratory operations.
By Technology
The immunoassay market includes enzyme-linked immunosorbent assays (ELISA), rapid tests, Western blotting, radioimmunoassays, and other technologies. ELISA is widely used because of its versatility, sensitivity, and suitability for detecting different biological substances across clinical and research applications.
The rapid tests segment is projected to register the fastest growth at a CAGR of 8.65% during the forecast period. Increasing demand for point-of-care diagnostics, shorter turnaround times, and convenient testing procedures is supporting adoption. These technologies are particularly useful in infectious disease screening and decentralized healthcare settings.
By Specimen
The blood specimen segment dominated the market with a 72.6% share in 2025. Blood samples are extensively used in immunoassay testing to detect infectious diseases, cancer biomarkers, hormones, and indicators associated with chronic conditions. Their broad application across routine diagnostics and specialized testing supports the segment's leading position.
Other specimen categories include saliva, urine, and additional biological samples. These alternatives support different diagnostic requirements and provide convenient options for selected testing applications.
By Application
The immunoassay market serves infectious disease testing, endocrinology, oncology, cardiology, autoimmune disorders, allergy diagnostics, toxicology, and other applications. Infectious disease testing remains an important application due to the widespread use of immunoassays for detecting antibodies and antigens associated with different infections.
The oncology segment is projected to register the fastest growth at a CAGR of 9.15% during the forecast period. Increasing demand for cancer screening, biomarker detection, and treatment monitoring is supporting the adoption of immunoassay-based diagnostic solutions. These tests contribute to identifying tumor-associated biomarkers and supporting personalized treatment approaches.
By End User
Hospitals represent an important end-user category because they conduct routine, emergency, inpatient, and outpatient diagnostic testing. Clinical laboratories also contribute significantly through high-volume testing services and specialized diagnostic capabilities.
Pharmaceutical and biotechnology companies use immunoassays in drug discovery, clinical research, and therapeutic development. Contract research organizations, blood banks, research laboratories, and home healthcare settings also utilize these technologies for different diagnostic and research requirements.
Immunoassay Market Regional Insights
North America
North America dominated the global immunoassay market with a 39.5% share in 2025. The region benefits from advanced healthcare infrastructure, high diagnostic testing volumes, and widespread adoption of automated laboratory systems. The United States represents a major contributor due to its established clinical laboratory networks, investments in precision diagnostics, and presence of leading diagnostic manufacturers. Increasing screening for chronic diseases, cancer, and infectious conditions is further supporting regional demand.
Europe
Europe represents a significant market, supported by established public healthcare systems, increasing diagnostic testing requirements, and advancements in laboratory automation. Countries such as Germany, the United Kingdom, and France are important contributors to regional growth. The implementation of stringent diagnostic quality standards and increasing investments in early disease detection are encouraging healthcare facilities to adopt advanced immunoassay technologies.
Asia-Pacific
Asia-Pacific is expected to register the fastest growth during the forecast period, supported by expanding healthcare infrastructure, increasing healthcare expenditure, and rising awareness of preventive diagnostics. China, Japan, India, and South Korea are important markets. The growing number of diagnostic laboratories, increasing prevalence of infectious and chronic diseases, and investments in modern healthcare facilities are creating opportunities for immunoassay manufacturers.
Immunoassay Market Key Players Analysis
The global immunoassay market is characterized by the presence of established diagnostic equipment manufacturers, biotechnology companies, and specialized laboratory solution providers. Companies are focusing on developing automated analyzers, improving assay sensitivity, and expanding their diagnostic product portfolios. Strategic collaborations, product innovations, and investments in point-of-care testing technologies are also shaping the competitive landscape.
Key players operating in the global immunoassay market include:
-
Abbott Laboratories
-
F. Hoffmann-La Roche AG
-
Siemens Healthineers
-
Danaher Corporation
-
Thermo Fisher Scientific
-
Bio-Rad Laboratories
-
bioMérieux SA
-
QuidelOrtho Corporation
-
Sysmex Corporation
-
Becton, Dickinson and Company
-
DiaSorin S.p.A.
-
Agilent Technologies
These companies are focusing on strengthening their diagnostic capabilities through advanced testing platforms, automated laboratory solutions, and innovative reagent technologies. Expanding global distribution networks and improving diagnostic efficiency remain important competitive priorities.
Conclusion
The global immunoassay market is expected to experience steady growth as the demand for accurate disease detection, routine screening, and advanced diagnostic testing continues to increase. The widespread use of immunoassays across infectious disease testing, endocrinology, oncology, and cardiology is supporting their importance in modern healthcare systems.
Although high equipment costs, testing complexities, and regulatory requirements remain important challenges, advancements in laboratory automation and rapid diagnostic technologies are creating new opportunities. The increasing adoption of point-of-care testing and biomarker-based diagnostics is also expected to support industry development. With the market projected to reach USD 42.55 billion by 2034, manufacturers focusing on testing accuracy, technological innovation, and accessible diagnostic solutions are positioned to strengthen their competitive presence.
About Us
Straits Research is a leading market research and intelligence organization specializing in research, analytics, and advisory services. The company provides comprehensive market reports, industry insights, and strategic business intelligence across multiple industries, helping organizations identify growth opportunities and make informed business decisions.
Contact Us
Email: [email protected]
Tel: +1 646 905 0080 (U.S.)
Tel: +44 203 695 0070 (U.K.)