How to Get an International Mortgage in Dubai as an Overseas Buyer
Learn how overseas buyers can finance Dubai property, understand mortgage eligibility, deposits, documents, costs, and key considerations.
 Al Amal Mortgage Consultant
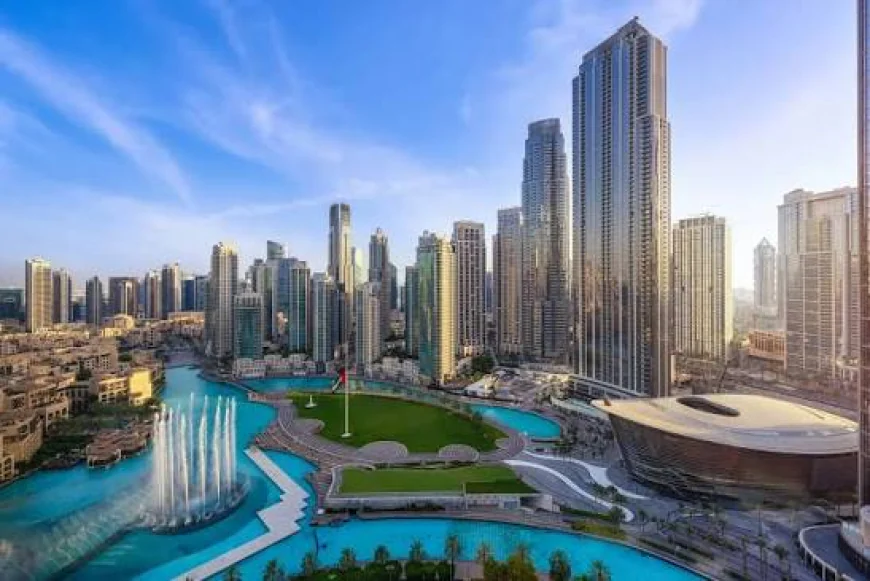
Dubai has become a popular destination for people who want to invest in property, move abroad, or simply own a home in one of the world's most dynamic cities. From modern apartments overlooking the skyline to spacious villas in family-friendly communities, the Dubai property market offers plenty of opportunities.But if you live outside the UAE, one question often comes up: How can I finance a property in Dubai?
This is where an international mortgage Duba solution can become important. For overseas buyers, understanding mortgage eligibility, deposits, documentation, and repayment options before purchasing a property can make the entire experience much smoother.
What Is an International Mortgage in Dubai?
An international mortgage is a financing option designed for buyers who are purchasing property in Dubai while living outside the UAE or earning income internationally.
The process can be different from getting a mortgage in your home country. Lenders may look at your residency, nationality, income source, employment status, existing financial commitments, and the property you want to purchase.
For someone unfamiliar with the UAE mortgage market, all these requirements can feel overwhelming. A mortgage consultant can help explain the process and help you understand what lenders may require.
Why Are Overseas Buyers Interested in Dubai Property?
Dubai attracts international property buyers for many reasons.
The city has developed into a major business, tourism, and lifestyle destination. It also offers a wide range of residential developments, from affordable apartments to high-end villas and luxury waterfront properties.
For some buyers, the goal is to purchase a home for personal use. Others see Dubai property as a long-term investment or a potential source of rental income.
Whatever the reason, financing is an important part of the decision. Understanding your mortgage options before choosing a property can help you set a realistic budget.
Who Can Apply for a Dubai Mortgage?
Mortgage eligibility depends on the lender and the borrower's circumstances. UAE residents and non-residents may have different requirements, and the available options can also vary based on nationality and income.
If you are an overseas buyer, you may be asked to provide evidence of your income, bank statements, identification, employment information, and details of your existing financial commitments.
The property itself can also affect the mortgage application. Lenders may have specific criteria regarding the location, type, value, and status of a property.
This is why it is useful to discuss your circumstances with a professional before assuming that a particular mortgage product will be available to you.
How Much Deposit Might You Need?
One of the first things international buyers should consider is the deposit.
The required deposit can vary depending on factors such as whether you are a resident or non-resident, the property value, the lender, and the type of property you are purchasing.
It is important to remember that your deposit is not the only upfront cost. Buyers should also plan for property-related fees, valuation costs, legal expenses, registration charges, and other transaction costs where applicable.
Having a complete picture of the upfront costs can help you avoid unpleasant surprises later.
Why Work With a Mortgage Consultant?
Searching for an international mortgage Dubai option on your own can be confusing. Different lenders have different criteria, and the mortgage that looks attractive at first may not necessarily be the most appropriate option for your circumstances.This is where Al Amal Mortgage Consultant can help.
A mortgage consultant can help you understand the process, review your requirements, and explain the types of financing that may be available. Instead of trying to understand every lender's criteria yourself, professional guidance can give you a clearer starting point.
The goal isn't simply to find a mortgage. It is to understand the financing arrangement as a whole and make a decision that fits your property plans and financial situation.
Don't Forget About Currency Considerations
Currency is particularly important for international buyers.
If you earn your income in another country or another currency, changes in exchange rates can affect how much your mortgage payments effectively cost in your home currency.
For example, an overseas buyer earning in euros, pounds, dollars, or another currency should think carefully about how currency movements could affect their finances.
Before taking a mortgage, make sure you understand which currency the loan and your income are in and consider getting appropriate financial advice about currency risk.
Final Thoughts
Buying property in Dubai from overseas can be an exciting opportunity, but it shouldn't be rushed. An international mortgage Dubai arrangement involves more than simply borrowing money to purchase a property. Residency, income, deposits, documentation, currency, property type, and lender requirements can all play a role.
The good news is that you don't have to navigate everything alone.
With guidance from Al Amal Mortgage Consultant, international buyers can gain a clearer understanding of the mortgage process and the factors they should consider before making a property purchase.
Before making a commitment, take the time to understand your budget, compare your available options, review the associated costs, and seek appropriate professional advice. A well-planned mortgage can help turn your Dubai property ambitions into a more manageable and informed investment journey.
FAQs
1. What is an international mortgage in Dubai?
An international mortgage in Dubai is a financing option that can help overseas buyers purchase eligible property in Dubai.
2. Can foreigners get a mortgage in Dubai?
Yes, foreign buyers may be able to obtain a Dubai mortgage, subject to the lender’s eligibility requirements and applicable regulations.
3. How much deposit is needed for a Dubai mortgage?
The required deposit can vary depending on factors such as residency status, property value, lender requirements, and the buyer’s financial profile.
4. What documents are needed for an international mortgage?
Buyers may need identification, proof of income, bank statements, employment details, and other financial or property-related documents.