How Infrastructure Development Impacts Property Prices: An Evidence-Based Analysis
Metros, expressways and airports can lift property prices 4% to 30%, even 100%+. See the evidence from NCR, Gurugram and Greater Noida, plus the risks.
 MORES
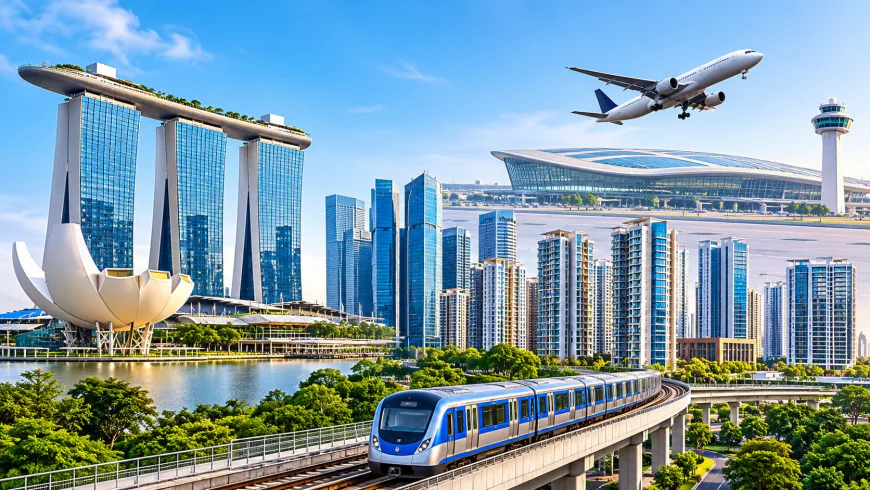
Infrastructure investment raises the price of properties due to reduced travel times and increased accessibility to employment opportunities, which lead to 4% to 30% increases around transport projects and more than 100% around expressways, although nearby noise and traffic congestion can cause localized reductions in values.
In urban economics, the link between infrastructure and real estate valuations can be understood through the lens of the bid-rent theory, according to which land and property prices are positively correlated with their accessibility to places of work and business. Reductions in commutation times and costs brought about by new transit systems, expressways, or international airports result in an increase in bids made for accessible sites.
1. Transit and Rail Infrastructure: Global and Regional Evidence
Mass Rapid Transit Systems (MRTS) and commuter rail systems have been the most widely studied catalysts for real estate valuation. Using meta-analysis techniques, researchers have derived reliable benchmarks regarding the impact of transit systems on the real estate market.
In one of the major studies published in The Journal of Real Estate Finance and Economics by Ghebreegziabiher Debrezion, Eric Pels, and Piet Rietveld, the authors have investigated the impact of railway stations on property values in different parts of the world. The results of this study indicated a significant difference between the two categories of property; while the property value within ¼ mile (approximately 400 meters) of the station is 16.4 percent more than the value of property away from the station area, the residential property values are only 4.2 percent more. Moreover, at other distances, the residential premiums stay consistent; for each 250 meters closer to the station, the property values are 2.3 percent higher compared to the commercial properties. Another similar study by Sara I. Mohammad et al., in Transportation Research Part A, showed that rail transportation projects increase land and property values by about 8 percent on average.
In rapidly urbanizing economies with severe traffic problems on roads, the transit premium is much higher. According to a 2025 hedonic pricing and DID research conducted by the International Journal of Contemporary Urban Affairs on the Mass Rapid Transit System corridor of Gurugram, it was found that houses within 500 meters of metro stations gained a 20% to 30% value uplift from transit development. This clearly indicates the rise in property prices near infrastructural development.
2. Expressways, Airports, and Growth Corridors
As metro routes densify existing areas, expressways and greenfield airports release peripheral areas to develop them into commercial and residential areas. Market data from India's National Capital Region (NCR), which is one of the busiest infrastructure-led real estate markets in the world, illustrates how multi-modal connectivity influences valuation:
Infrastructure Catalyst |
Micro-Market / Corridor |
Documented Price Impact |
Dwarka Expressway (Haryana section opened 2024; Delhi section 2025) |
Dwarka Expressway Belt, Gurugram |
Average residential prices surged 135% between 2021 and H1 2026 (climbing from ~₹6,032/sq. ft. to ₹14,180/sq. ft., per ANAROCK Research), shifting the belt into a luxury housing corridor. |
Noida International Airport (Jewar) & Yamuna Expressway |
Yamuna Expressway & Greater Noida Belt |
Following airport commissioning in 2026, Greater Noida expanded to 28% of total NCR residential launches (per Knight Frank India), while corridor property values roughly tripled over five years ahead of commercial flight operations. |
Urban Road Upgradation (Tender S.U.R.E. Project) |
Central Bengaluru, India |
Statistically significant uplift in commercial and residential sale values, occurring primarily upon project completion rather than at initial announcement (per IIM Bangalore Working Paper No. 646). |
3. Four Core Mechanisms Driving Appreciation
Four major economic channels through which infrastructure adds value to property include:
-
Commute-Time Capitalization: Every minute spent commuting has an associated opportunity cost. If a highway or subway reduces a daily one-and-a-half-hour commute to 35 minutes, buyers and tenants will be willing to pay extra to save their time.
-
Job Creation and Commercial Agglomeration: Transport links are always associated with corporate offices, warehouses, logistics facilities, and commercial areas such as shopping centers. Aviation, logistics, and information technology clusters create jobs that are located close to new highways and airports.
-
Increased Zoning Rights for Transit Corridors: Transit zones are always associated with high FAR or FSI requirements. This implies that a developer can construct high-rises and dense buildings around the station, thus adding value to the underlying land.
-
Rental Yield Expansion: While capital values appreciate during the construction period, rental rates spike when infrastructure is ready for use and commercial and employment nodes become active. Walkable transit access reduces tenant vacancy and commands reliable rental premiums.
4. The Proximity Paradox and Market Risks
There are empirical studies that advise investors against relying on proximity to infrastructure for guaranteed positive returns in all cases:
-
Negative Externalities Around Nodes: According to a classic study carried out by David R. Bowes and Keith R. Ihlanfeldt in the Journal of Urban Economics, though transit stations increase the value of surrounding neighborhoods, houses adjacent to stations or above-ground rail lines, within a quarter mile, incur discounts as high as 19%. This is caused by noise, vibration, congestion on roads, and lower privacy. In global literature, the perfect spot to reap gains of appreciation lies somewhere between 400 and 800 meters from a station—a distance close enough to get to a station within five minutes but far away from negative externalities around a station.
-
Announcement versus Completion Risk: According to research done at the Indian Institute of Management Bangalore, an important consideration when comparing developed economies to developing economies is the risk factor. While the developed economies tend to appreciate once there is news of the infrastructure development projects, developing economies rarely appreciate at the announcement stage and sometimes depreciate as construction starts due to uncertainty about execution and funding. Appreciation tends to come after the projects are completed.
-
Speculative Overpricing: When investors bid up land values years ahead of commissioning, late-stage entrants face compressed returns. On major expressway and airport corridors, institutional data show that substantial infrastructure-led repricing occurs prior to full commissioning—after which quarterly growth moderates and returns shift from rapid speculative gains to steadier, end-user-driven growth.