Germany Health & Medical Insurance Market: Navigating Demographic Change with Innovation
Germany health & medical insurance market worth USD 82.4 Billion in 2025 is growing at a CAGR 5.08% to reach USD 128.7 Billion by 2034.
 Yadwender Kumar
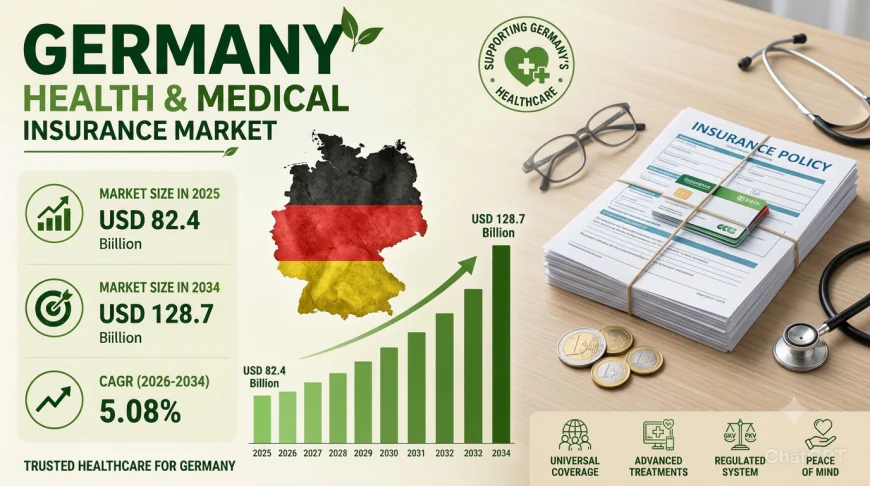
The German health and medical insurance landscape is navigating a period of remarkable transformation. For generations, the nation's healthcare system has been defined by universal coverage, a dual public-private structure, and a deep-rooted commitment to social solidarity. But demographic shifts and digital innovation have arrived with force, reshaping how insurers design products, how providers deliver care, and how millions of residents access medical services. The Germany health & medical insurance market is at the epicentre of this evolution. Valued at USD 82.4 Billion in 2025, the market is projected to reach USD 128.7 Billion by 2034, growing at a compound annual rate of 5.08 per cent from 2026 to 2034. These figures reflect an industry entering a new era of digital health integration and specialised coverage, even as it contends with the fiscal pressures of an ageing population.
What's Driving Growth of Germany's Health & Medical Insurance Market?
Soaring geriatric populations are reshaping demand for specialised coverage. Germany's older population is growing rapidly, with the number of people aged 65 and above predicted to expand by 41 per cent by 2050 to 24 million, representing nearly one-third of the total population. This demographic shift is driven by the country's robust healthcare system and high life expectancy, with the super-aged population demonstrating high levels of fitness. Geriatric patients typically require more frequent medical care, including chronic disease management, long-term care, and rehabilitation, creating sustained demand for health insurance coverage. Insurers are responding with specialised products covering long-term care, rehabilitation, and home healthcare, designed to meet the unique needs of this growing segment.
Strong regulatory frameworks are ensuring universal access and market stability. Germany's mandatory health insurance regime provides broad-based coverage for all residents, including foreigners and self-employed individuals, guaranteeing access to healthcare services. The regulatory framework determines premiums and benefits, promoting fairness and transparency in the system. In 2025, Germany implemented significant healthcare reforms, including the rollout of electronic patient files (ePA) on January 15, higher insurance contributions to 2.5 per cent, increased long-term care insurance premiums, and new hospital funding reforms from January 1. Faced with an estimated deficit of €17 billion in 2024, the government raised statutory health insurance contribution rates by 0.1 percentage points to 1.7 per cent, as declared by Federal Health Minister Karl Lauterbach, to preserve the fiscal soundness of the healthcare sector.
Rquest Sample for PDF Report: https://www.imarcgroup.com/germany-health-medical-insurance-market/requestsample
Digital health innovations are transforming how insurance is accessed and delivered. The introduction of electronic patient files represents a fundamental shift toward digitalised healthcare records, enabling more coordinated care and streamlined claims processing. Insurers are increasingly leveraging digital platforms to engage customers directly, with direct selling via online platforms, telephone services, and personal consultations becoming more prevalent. These channels offer personalised relationships between insurers and customers, typically leading to more favourable pricing, transparency, and assistance for consumers seeking simple insurance solutions.
Three Trends Reshaping the Industry
The Dual Public-Private System Is Adapting to Demographic Pressures
Germany's health insurance market is uniquely structured around two pillars: Statutory Health Insurance (SHI) and Private Health Insurance (PHI). SHI is compulsory for individuals with incomes below a certain threshold, offering comprehensive coverage at relatively low premiums financed by employee and employer contributions. PHI is available to those with higher incomes, freelancers, and civil servants, providing greater individualised coverage, private hospital accommodations, reduced waiting periods, and greater access to specialists.
The financial sustainability of the system is under increasing pressure as the population ages and the working-age population is anticipated to decline by 23 per cent, contributing less to the healthcare system. Insurers and the government are being forced to adapt their models to provide long-term coverage to an ageing populace while maintaining fiscal soundness. Incremental changes in contribution rates, such as the 0.1 percentage point increase in 2024, are being implemented to narrow the envisaged budget gap. These reforms speak to balancing increased healthcare need with demands for financial sustainability.
Why it matters: The dual system's ability to adapt to demographic change will determine whether Germany can maintain universal coverage while ensuring financial viability.
Business implication: Insurers must develop innovative products that cater to evolving healthcare needs, including specialised care for the elderly, while optimising operational efficiency to manage rising costs.
Future impact: As the population ages further, the market will need to incorporate new solutions to remain sustainable and accessible to everyone, potentially including expanded preventive care and integrated healthcare models.
Digitalisation Is Reshaping Distribution and Customer Engagement
The distribution landscape for health insurance in Germany is undergoing significant digital transformation. While single tied agents and insurance group intermediaries continue to provide specialised expertise and personal recommendations, digital platforms are enabling customers to easily compare, buy, and administer insurance policies at their fingertips. Direct selling through online platforms, telephone services, and personal consultations offers a more personalised relationship between insurers and customers, typically leading to more favourable pricing and transparency.
Recent developments underscore this trend. In January 2024, Allianz Partners released the Allyz mobile app, a digital solution offering travelers trusted guidance and access to the full range of insurance benefits, with the release in France, Germany, and the Netherlands representing a significant step in the growth of Allianz Partners' digital platform. In August 2024, ERGO, O2 Telefónica, and Telefónica Insurance formed an alliance to introduce embedded insurance services in Germany, launching O2 Care Travel, which includes international health insurance with repatriation, rescue, and recovery costs along with hassle-free travel and emergency assistance.
Why it matters: Digital channels are becoming essential for reaching younger, tech-savvy consumers and for delivering seamless, personalised insurance experiences.
Business implication: Insurers must invest in digital infrastructure, mobile applications, and embedded insurance partnerships to remain competitive and meet evolving customer expectations.
Future impact: The integration of digital health records, telemedicine, and AI-powered claims processing will become standard, further streamlining the insurance experience and enabling more personalised product offerings.
Embedded Insurance and Strategic Partnerships Are Expanding Market Reach
The German health insurance market is witnessing a proliferation of embedded insurance solutions and strategic partnerships that extend coverage to new customer segments. In August 2024, ERGO, O2 Telefónica, and Telefónica Insurance formed an alliance for the introduction of embedded insurance services, launching O2 Care Travel for individuals and families. In July 2024, Fintiba collaborated with BARMER to provide comprehensive health insurance for international students and professionals, combining BARMER's medical services — including visits to doctors, dental consultations, hospitalisation, and preventive checks — into Fintiba's offerings.
In March 2025, BlackRock, Allianz, and T&D Holdings agreed to buy Viridium Group from Cinven for EUR 3.5 billion. Viridium has expertise in closed life insurance portfolio management, managing approximately EUR 67 billion in assets for 3.4 million policyholders. The deal, set to close during the second half of 2025, will further enhance Allianz's position in Germany's health and medical insurance business.
Why it matters: Embedded insurance and partnerships allow insurers to reach customers at the point of need, expanding coverage to niche segments such as travellers, international students, and expatriates.
Business implication: Insurers must develop flexible, API-driven products that can be integrated into third-party platforms and partner ecosystems, enabling seamless distribution beyond traditional channels.
Future impact: The boundaries between insurance, healthcare, and technology will continue to blur, with embedded solutions becoming a primary distribution channel for supplementary health products.
What the Market Numbers Actually Tell Us
A market expanding from USD 82.4 billion to USD 128.7 billion over nine years suggests significantly greater commercial activity across statutory insurers, private insurers, distribution channels, and digital health platforms. The 5.08 per cent compound annual growth rate signals steady, sustained expansion driven by structural shifts in demographics, regulatory reform, and technology adoption.
Regional dynamics within Germany reveal distinct insurance profiles. Western Germany has a higher proportion of both employed and self-employed individuals, creating greater demand for health insurance coverage, with private insurance highly preferred in urban areas such as Cologne and Düsseldorf. Southern Germany, particularly Bavaria, enjoys higher income levels and greater private health insurance uptake, supported by robust economic performance. Eastern Germany, traditionally less economically advanced, has a higher percentage of its population covered under statutory health insurance, reflecting generally lower incomes. Northern Germany reveals an uneven insurance profile, with equilibrium between private and statutory schemes, and coastal cities such as Hamburg and Bremen showing a mixed profile of affluent individuals choosing private insurance while rural settings demonstrate greater dependence on statutory coverage.
The dual reality of persistent fiscal pressures alongside the health insurance sector's emergence as one of Germany's most stable and dynamic markets creates a complex but opportunity-rich environment. The market is highly competitive, with public insurers providing wide coverage with emphasis on availability and affordability, while private insurers service the more affluent population with flexible and individualised policies. This competition encourages ongoing improvements in service provision and the creation of innovative insurance products.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of technology, demographic change, and personalised coverage. The growing geriatric population creates sustained demand for long-term care insurance, rehabilitation coverage, and home healthcare products. Insurers that can develop comprehensive, custom-tailored offerings for this segment will capture significant market share.
The self-employed and civil servant segments offer distinct opportunities. Self-employed individuals have the freedom to choose between private and statutory insurance, though private premiums are often more expensive, leading many to base their choice on the necessity for full coverage and their ability to efficiently manage medical expenses. Civil servants can receive special public health insurance benefits with lower premiums and more services, making statutory health insurance highly desirable, though some prefer private insurance for additional benefits.
Digital health innovations, including electronic patient files, telemedicine, and AI-powered diagnostics, are creating new avenues for insurers to engage customers and streamline operations. The expansion of embedded insurance solutions and strategic partnerships will enable insurers to reach new customer segments, including international students, expatriates, and travellers. For companies that can navigate the regulatory environment, invest in digital infrastructure, and develop products that address the evolving needs of Germany's ageing population, the pathway to sustained growth in the health and medical insurance market is increasingly clear.
Recent Industry Developments
BlackRock, Allianz, and T&D Holdings Acquire Viridium Group (March 2025) — BlackRock, Allianz, and T&D Holdings agreed to buy Viridium Group from Cinven for EUR 3.5 billion. Viridium specialises in closed life insurance portfolio management, managing approximately EUR 67 billion in assets for 3.4 million policyholders. The deal, set to close during the second half of 2025, will further enhance Allianz's position in Germany's health and medical insurance business.
GKV-SV Signs Agreement with Santhera Pharmaceuticals for AGAMREE (February 2025) — The German National Association of Statutory Health Insurance Funds signed an agreement with Santhera Pharmaceuticals on the reimbursement of treatment with AGAMREE (vamorolone) for Duchenne Muscular Dystrophy. With this achievement, AGAMREE became the first medicine in Germany to be granted a government price for the treatment of DMD in patients 4 years and older.
DKV Introduces New Supplementary Dental Insurance (September 2024) — ERGO Group's subsidiary DKV Deutsche Krankenversicherung AG announced it will introduce a new supplementary dental insurance product to the German market. The new plan is intended to improve protection of dental health through the introduction of contemporary benefits and flexible variants.
ERGO, O2 Telefónica, and Telefónica Insurance Form Embedded Insurance Alliance (August 2024) — The companies formed an alliance for the introduction of embedded insurance services in Germany, launching O2 Care Travel, which includes international health insurance with repatriation, rescue, and recovery costs along with hassle-free travel and emergency assistance. Individuals and families are eligible to buy this insurance plan.
Fintiba Collaborates with BARMER for International Student Insurance (July 2024) — Fintiba partnered with BARMER to provide comprehensive health insurance for international students and professionals. With this partnership, Fintiba combines BARMER's medical services such as visits to doctors, dental consultations, hospitalisation, and preventive checks into their repertoire.
Allianz Partners Releases Allyz Mobile App (January 2024) — Allianz Partners announced the release of the Allyz mobile app, a digital solution offering travelers trusted guidance and expertise along with access to the entire range of insurance benefits. The release of the mobile app in France, Germany, and the Netherlands is a significant step in the growth of Allianz Partners' digital platform.
Germany Implements Major Healthcare Reforms (January 2025) — Germany's insurance and healthcare reforms included the implementation of electronic patient files (ePA) on January 15, higher insurance contributions to 2.5 per cent, long-term care insurance premiums up, and new hospital funding reforms from January 1. These reforms aim to preserve the fiscal soundness of the healthcare sector while maintaining comprehensive coverage.