GCC Drones Market Growth: Defense Demand & Commercial Applications Forecast 2026-2034
GCC drones market size was valued at USD 666.4 Million in 2025, expected to reach USD 2,083.1 Million at a CAGR of 13.50% during 2026-2034.
 jackleen jackleen
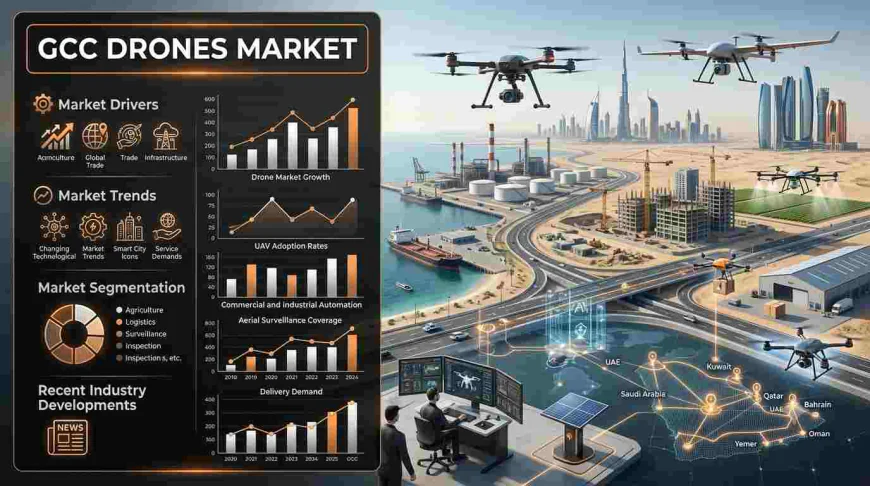
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the GCC Drones Market. The GCC drones market size reached USD 666.4 Million in 2025. Looking forward, IMARC Group expects the market to reach USD 2,083.1 Million by 2034, exhibiting a growth rate (CAGR) of 13.50% during 2026-2034. Regulatory support and government initiatives, increasing defense expenditure, a rise in commercial applications, significant technological advancements, and infrastructure development and urban planning represent some of the key factors driving the market.
The GCC drone market is undergoing a wave of regulatory recalibration across all six member states. In the UAE, a nationwide drone suspension ran from February 28, 2026, to a reported lift on June 30, 2026, under GCAA Safety Decision 2026-03, even as the UAE Ministry of Defence awarded the region's largest disclosed 2026 drone contract, worth AED 1.396 billion (about USD 380 million), to EDGE Group subsidiary ANAVIA for 92 HT-750 aircraft at UMEX 2026. Meanwhile, Saudi Arabia's General Authority of Civil Aviation (GACA) tested drone-based postal parcel delivery in September 2025 and issued the Kingdom's first operational permit for drone-based medicine delivery during Hajj by May 2026, and Qatar, Oman, and Kuwait have each introduced or rewritten national drone laws through 2026.
GCC Drones Market at a Glance
- Market Size (2025): USD 666.4 Million
- Market Forecast (2034): USD 2,083.1 Million
- Growth Rate (2026-2034): CAGR of 13.50%
- Base Year: 2025 | Historical Period: 2020-2025 | Forecast Period: 2026-2034
- Key Types: Fixed Wing, Rotary Wing, and Hybrid
- Key End-Use Industries: Construction, Agriculture, Military and Defense, Law Enforcement, and Logistics
How Regulation and Defense Investment Are Reshaping the Future of the GCC Drones Market
- UAE's National Drone Services Platform: The UAE Cybersecurity Council announced the country's first national drone guidelines in May 2025, launching a jointly run platform with the GCAA allowing residents to register as pilots, get real-time situational awareness, receive immediate mission approvals in controlled airspace, and access live airspace updates for safe drone operations.
- Record Defense Drone Contracts: EDGE Group and its subsidiaries ANAVIA and ADASI continue to anchor UAE state procurement, with ANAVIA's AED 1.396 billion contract for 92 HT-750 aircraft marking the region's largest disclosed 2026 drone deal, awarded at the UMEX exhibition in Abu Dhabi.
- Localized Manufacturing Partnerships: Saudi Arabia's SAMI-Baykar localisation programme continues to build domestic drone manufacturing capability in the Kingdom, mirroring similar state-backed conglomerate models seen in the UAE's EDGE Group ecosystem.
Grab a sample PDF of this report: https://www.imarcgroup.com/gcc-drones-market/requestsample
GCC Drones Market Trends and Drivers
Demand is underpinned by rising adoption of drones across agriculture, real estate, and defense, with research and development activities and strategic collaborations between governmental agencies and tech companies continuing to enhance the technological capabilities of drones deployed across the region.
The market's structural differentiator is the introduction of local drone manufacturing and service platforms offering customized solutions tailored to regional needs, with decentralization in drone services emphasizing local development and application across construction, surveillance, and environmental monitoring use cases.
A third driver is deepening commercial and medical logistics applications, with Saudi Arabia's GACA testing drone-based postal parcel delivery in September 2025 and issuing its first operational permit for drone-based medicine and medical-logistics delivery to Terra Drone Arabia by May 2026, covering the boundaries of the Holy Sites in Makkah during Hajj.
Government Schemes and Regulatory Initiatives Driving Demand
- UAE Federal Law No. 26 of 2022: This law established a new federal framework governing all unmanned aircraft (UA) operations across the UAE, superseding earlier ad hoc restrictions and forming the legal basis for the GCAA's ongoing CAR-UAS regulatory development.
- UAE National Drone Guidelines and GCAA Platform: Announced in May 2025 by the UAE Cybersecurity Council in partnership with the GCAA, these guidelines and the accompanying digital platform support pilot registration, mission approval, and airspace awareness for recreational, commercial, and government drone operators.
- UAE 2026 Nationwide Drone Suspension and Lift: Under GCAA Safety Decision 2026-03 (Issues 01 and 02), the UAE suspended drone operations nationwide from February 28, 2026, to a reported lift on June 30, 2026, reflecting the regulator's ongoing recalibration of airspace safety policy.
- Saudi Arabia's GACA Drone Delivery Authorization: Saudi Arabia's General Authority of Civil Aviation, working with the Transport General Authority, tested drone-based postal parcel delivery in September 2025 and issued the Kingdom's first operational permit for drone-based medicine delivery to Terra Drone Arabia in 2026, covering Makkah's Holy Sites during Hajj.
- Qatar, Oman, and Kuwait National Drone Laws: Qatar introduced a new drone law carrying prison terms for violations, Oman established a sales and registration regime, and Kuwait issued a decree-law, each rewriting national drone rules through 2026 as part of a region-wide regulatory modernization effort.
We explore the factors propelling the GCC drones market growth, including technological advancements, consumer behaviors, and regulatory changes.
GCC Drones Market Industry Segmentation
The report has segmented the market into the following categories:
Breakup By Type:
- Fixed Wing
- Rotary Wing
- Hybrid
Breakup By Component:
- Hardware
- Software
- Accessories
Breakup By Payload:
- <25 Kilograms
- 25-170 Kilograms
- 170 Kilograms
Breakup By Point of Sale:
- Original Equipment Manufacturers (OEM)
- Aftermarket
Breakup By End Use Industry:
- Construction
- Agriculture
- Military and Defense
- Law Enforcement
- Logistics
- Media and Entertainment
- Others
Breakup By Country:
- Saudi Arabia
- UAE
- Qatar
- Bahrain
- Kuwait
- Oman
The UAE and Saudi Arabia lead the country segment, anchored by the UAE's EDGE Group-led defense procurement and national drone platform, and Saudi Arabia's GACA-led commercial and medical drone delivery authorizations alongside the SAMI-Baykar localisation programme.
Competitive Landscape
The GCC drones market features a mix of state-backed defense conglomerates and specialized commercial drone operators. Notable participants and developments include:
- EDGE Group (via subsidiaries ANAVIA and ADASI)
- SAMI-Baykar (Saudi Arabia localisation programme)
- Terra Drone Arabia
- Space Autonomous Drones (UAE delivery start-up)
EDGE Group continues to anchor UAE defense procurement through its ANAVIA and ADASI subsidiaries, securing the region's largest disclosed drone contracts, while Saudi Arabia's SAMI-Baykar partnership builds domestic manufacturing capability, and specialized operators such as Terra Drone Arabia expand into medical and logistics delivery applications under new regulatory authorizations.
Market Concentration Analysis
- The UAE and Saudi Arabia account for the bulk of GCC drone market activity, anchored by EDGE Group's dominant defense procurement position in the UAE and GACA's commercial and medical drone delivery authorizations in Saudi Arabia.
- Defense-linked manufacturing and procurement remain concentrated around state-backed conglomerates, including EDGE Group in the UAE and the SAMI-Baykar localisation programme in Saudi Arabia.
- Smaller markets, including Qatar, Oman, Kuwait, and Bahrain, compete on niche regulatory modernization and specialized commercial drone applications rather than head-on volume competition with the UAE's and Saudi Arabia's dominant defense and logistics drone programs.
What Does The Full Report Cover?
- Historical, current, and forecast market size for the GCC drones market
- Market breakup by type, component, payload, point of sale, end use industry, and country
- Country-level analysis covering Saudi Arabia, UAE, Qatar, Bahrain, Kuwait, and Oman
- Key growth drivers, restraints, and opportunities shaping the market
- Porter's Five Forces analysis and value chain assessment
- Competitive landscape, market structure, and player positioning
- Detailed profiles of major companies operating in the market
Recent News and Developments in the GCC Drones Market
- May 2026: Saudi Arabia's GACA issued the Kingdom's first operational permit for drone-based medicine delivery and medical-logistics operations to Terra Drone Arabia, covering the boundaries of the Holy Sites in Makkah during Hajj.
- February-June 2026: The UAE implemented a nationwide drone suspension from February 28 to a reported lift on June 30, under GCAA Safety Decision 2026-03, affecting commercial and recreational drone operations across the Emirates.
- January 2026: The UAE Ministry of Defence awarded EDGE Group subsidiary ANAVIA a contract worth AED 1.396 billion (about USD 380 million) for 92 HT-750 aircraft at the UMEX exhibition in Abu Dhabi, the region's largest disclosed 2026 drone contract.
- September 2025: Saudi Arabia's GACA, working with the Transport General Authority, tested drone-based postal parcel delivery as part of the Kingdom's broader commercial drone logistics push.
- May 2025: The UAE Cybersecurity Council announced the country's first national drone guidelines, launching a joint platform with the GCAA for pilot registration, mission approval, and airspace awareness.
- January 2025: The UAE's Ministry of Interior announced the partial lifting of its 2022 drone ban, allowing individuals to resume drone use under new federal and emirate-level regulatory requirements.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
- How big is the GCC drones market and what is its growth outlook through 2034?
- What are the key growth drivers, restraints, and opportunities in the GCC drones market?
- Which type, component, payload, and end-use industry segments hold the largest share of the market?
- Which country leads the GCC drones market, and why?
- How are evolving national drone regulations shaping regional demand?
- Who are the key players in the GCC drones market, and how is the competitive landscape evolving?
- What role are defense procurement and medical logistics delivery playing in the market's future?
About Us
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: [email protected]
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104