Furniture Market Outlook: Global Industry Growth, Segments, and Forecast 2026–2034
Hotels, resorts, and dining establishments require durable, aesthetically customized furniture aligned with brand experiences, continuously creating new commercial procurement cycles.
 Kapil Kazade
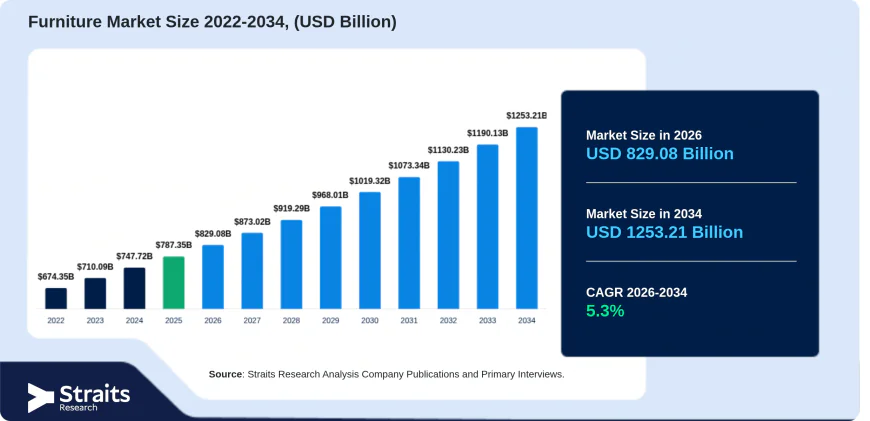
The global furniture market is projected to expand significantly from USD 829.08 billion in 2026 to USD 1,253.21 billion by 2034, demonstrating a consistent CAGR of 5.3%. Sustained market expansion is primarily propelled by rapid worldwide urbanization, expanding housing construction pipelines, and strong commercial demand across the hospitality sector.
Global Furniture Market Overview & Market Dynamics (2026–2034)
The global furniture market represents one of the most vital segments of the international consumer goods and commercial furnishings sector. Characterized by steady evolution, modern product integration, and shifting consumer preferences, the market continues to experience sustained expansion worldwide. Valuation data indicates that the global furniture market was valued at USD 787.35 billion in 2025 and is projected to expand from USD 829.08 billion in 2026 to USD 1,253.21 billion by 2034. This trajectory corresponds to a compound annual growth rate (CAGR) of 5.3% across the forecast timeline. Earlier sector estimates placed the industry at USD 747.72 billion in 2024, demonstrating consistent momentum driven by structural demographic and economic trends.
At its core, furniture encompasses movable items engineered to support essential human activities, including resting, sleeping, dining, seating, and organized storage. Products span beds, tables, desks, sofas, couches, chairs, stools, cabinets, and shelves. Beyond structural utility, contemporary furniture plays a fundamental aesthetic role in interior architecture, significantly shaping the ambiance and visual identity of both residential and professional environments.
Key Industry Drivers & Macroeconomic Tailwinds
- Accelerating Urbanization and Residential Construction: A primary catalyst fueling market expansion is the ongoing migration toward urban centers. UNCTAD demographic records show global urban population share increasing from 52.5% in 2012 to 56.9% in 2022, with United Nations projections anticipating an urban concentration of 68% by 2050. This demographic transition directly fuels new housing developments and home renovations. Furthermore, Oxford Economics projects global construction output to grow by USD 4.5 trillion (a 42% increase) to reach USD 15.2 trillion by 2030, with major contributions coming from China, India, the United States, and Indonesia.
- Robust Recovery in Travel, Tourism & Hospitality: Commercial demand is strongly reinforced by the global hospitality revival. According to the World Travel & Tourism Council (WTTC), travel sector revenues recovered to USD 10 trillion by year-end 2023, heading toward a projected USD 15 trillion contribution over the coming decade. Hotels, resorts, and dining establishments require durable, aesthetically customized furniture aligned with brand experiences, continuously creating new commercial procurement cycles.
Market Segmentation & Structural Breakdown
The report provides comprehensive segmentation across product type, raw material composition, end-user applications, and geographic performance:
- Product Type Analysis: The Beds category leads the market overall, capturing a dominant 39.9% share within bedroom furniture. Growth in this segment is driven by evolving sleep health awareness and product innovations, projecting a 6.5% CAGR. Other major product categories include sofas and couches, tables and desks, chairs and stools, and storage cabinets.
- Material Composition:Wood remains the predominant material choice, accounting for a massive 55% revenue share. Wood is widely favored due to its natural warmth, structural longevity, structural versatility, and low maintenance requirements across hardwood, softwood, and engineered timber types. Metal, plastic, and glass account for the remaining share, catering to modern minimalist and commercial applications.
- End-User Verticals: The Residential segment represents the major end-user share at 68%, projected to expand at a 6.0% CAGR. Growth is sustained by nuclear family formation, housing completions, and demand for multi-functional space-saving solutions. The commercial sector comprises office complexes, educational institutions, healthcare facilities, and hospitality venues.
Emerging Opportunities, Industry Restraints & Regional Landscape
Technological convergence serves as a prominent growth opportunity, specifically through the integration of smart furniture. Product developments such as app-connected sleep tracking mattresses, ergonomic adjustable beds, and space-saving modular mechanical units (highlighted by releases from Sleep Number, Living Spaces, and Ebarza) are redefining modern living standards.
Conversely, industry growth faces constraints from environmental regulations and raw material sourcing standards. Mandates such as the European Union Timber Regulation (EUTR) and California Air Resources Board (CARB) formaldehyde standards enforce strict compliance around deforestation, indoor air quality, and waste management, raising compliance and manufacturing costs.
Regionally, Asia-Pacific dominates the global market with a commanding 48.7% share, driven by strong manufacturing bases and rapid urban growth in China, India, Japan, and Australia, delivering an anticipated 7.6% CAGR. Meanwhile, North America maintains position as a highly lucrative and rapidly expanding market driven by smart home integration and high consumer spending.
Get the Complete Market Report=https://straitsresearch.com/report/furniture-market