Europe Smart Windows Market Size, Growth 2026–2034
Europe smart windows market is set to grow from USD 518M to USD 1.34B by 2034. Explore electrochromic technology, IoT integration, and opportunities.
 Ranjeet Sharma
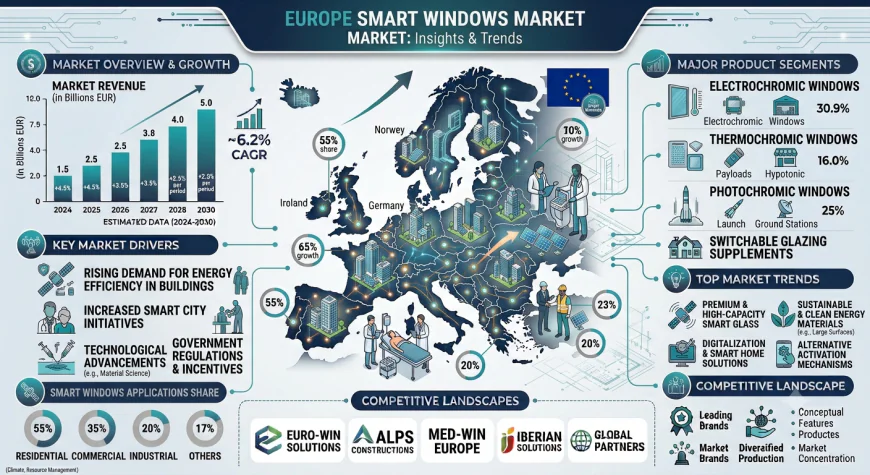
European building managers are confronting an uncomfortable reality. Buildings account for approximately 40 per cent of the region's energy consumption, yet much of that energy is wasted through inefficient glazing that allows heat to escape in winter and solar gain to overheat interiors in summer. Traditional solutions—blinds, shades, and mechanical cooling—consume additional energy while adding maintenance complexity. A more elegant answer is emerging from the glass itself. The Europe smart windows market sits at the intersection of energy efficiency, occupant comfort, and building automation. Valued at USD 517.9 million in 2025, the market is projected to reach USD 1,335.9 million by 2034, exhibiting a compound annual growth rate of 10.77 per cent during 2026-2034. These figures reflect an industry poised to transform how buildings manage light and heat.
What's Driving Growth of Europe's Smart Windows Market?
Significant growth in the construction industry is expanding the addressable market. Europe's construction sector, despite periodic fluctuations, continues to invest in new commercial, residential, and industrial projects. Smart windows are increasingly specified in premium developments where energy performance and occupant comfort are prioritised. The push for nearly zero-energy buildings under EU directives is making dynamic glazing an attractive solution for meeting stringent performance requirements.
Growing awareness of energy conservation benefits is accelerating adoption. Smart windows regulate the amount of light entering a room, minimising and conserving energy in buildings. As building owners and occupants become more conscious of operational costs and carbon footprints, the value proposition of dynamic glazing becomes increasingly compelling. The ability to reduce cooling loads in summer and heating demands in winter delivers measurable savings.
Increasing demand for smart windows in automobiles is creating a significant application segment. They are installed in electric cars to maintain inner temperature, thereby enhancing comfort and convenience for passengers. The transport sector currently accounts for the largest market share, driven by premium vehicle manufacturers seeking to differentiate their offerings through advanced glazing technology.
Favourable government policies are promoting energy-efficient systems. Implementation of supportive government policies promoting the use of energy-efficient systems is anticipated to drive the market further across the continent. Building codes that mandate energy performance standards, combined with incentives for retrofit projects, create a regulatory environment that favours smart window adoption.
Three Trends Reshaping the Industry
Electrochromic technology is consolidating its market leadership.
Electrochromic technology holds the majority of the total market share, offering proven performance and reliability for architectural applications. These windows change tint in response to electrical voltage, allowing precise control over light transmission and solar heat gain. The technology's ability to maintain tint without continuous power draw makes it particularly attractive for energy-conscious building owners.
Why it matters: Electrochromic dominance reflects its maturity and proven performance in large-scale architectural installations.
Business implication: Manufacturers must continue improving switching speeds and durability while reducing costs to expand adoption beyond premium projects.
Future impact: Electrochromic windows will become standard in high-performance commercial buildings, with costs declining as production scales.
IoT integration is transforming windows into intelligent building components.
Rising product integration with Internet-of-Things for improved manageability and advanced configuring abilities is currently catalysing the market. Smart windows are evolving from standalone products into connected building systems that respond to occupancy patterns, weather forecasts, and energy pricing signals. Integration with building management systems enables automated optimisation that maximises both comfort and efficiency.
Why it matters: IoT integration multiplies the value of smart windows by enabling responsive, data-driven operation.
Business implication: Manufacturers must develop robust software platforms and interoperability standards to compete in an increasingly connected ecosystem.
Future impact: Smart windows will become nodes in intelligent building networks, contributing data and responding to grid signals.
Self-dimming windows are dominating the product segment.
Among product types, self-dimming windows exhibit clear dominance in the market. These windows automatically adjust their tint in response to ambient light conditions, eliminating the need for manual intervention or external control systems. The simplicity of operation appeals to both residential and commercial customers who value convenience alongside energy savings.
Why it matters: Self-dimming functionality offers passive optimisation that requires no occupant intervention.
Business implication: Product development should prioritise autonomous operation alongside manual override capabilities.
Future impact: Self-dimming technology will migrate into mainstream building products, becoming a standard feature rather than a premium upgrade.
What the Market Numbers Actually Tell Us
A market expanding from USD 517.9 million to USD 1,335.9 million over nine years suggests significantly greater commercial activity across glass manufacturers, coating suppliers, electronics providers, and building automation companies. The 10.77 per cent compound annual growth rate signals one of the fastest-growing segments in European building materials. Electrochromic technology leads the market, while self-dimming windows dominate the product segment. The transport sector accounts for the largest application share, though commercial buildings represent a substantial and growing opportunity. Germany currently dominates the regional market, supported by its strong automotive industry, advanced construction sector, and leadership in building energy efficiency standards. For investors and industry participants, the trajectory indicates that smart windows are transitioning from premium novelty to essential building component, driven by regulatory requirements and sustainability imperatives.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of energy efficiency and building automation. Retrofitting existing building stock represents a substantial market, particularly in Western Europe where older buildings require significant energy performance upgrades to meet climate targets. The integration of smart windows with building management systems creates opportunities for software developers and systems integrators alongside hardware manufacturers. Self-repairing window technology, while still emerging, offers potential for reduced maintenance costs and extended product lifespans. The commercial building segment, currently smaller than transport, is poised for accelerated growth as office developers seek to meet sustainability certifications and attract environmentally conscious tenants. Companies that can demonstrate verifiable energy savings, seamless integration with existing building systems, and competitive total cost of ownership are well-positioned to capture value in this evolving market. Key countries including Germany, France, the United Kingdom, Italy, and Spain represent the largest regional markets, with growth opportunities across residential, commercial, industrial, and transport applications.