Europe Self Storage Market Size, Share, Report 2026-2034
Europe's self storage market is set to grow from USD 27.4B to USD 35.4B by 2034. Explore urban densification, remote operations, and opportunities.
 Ranjeet Sharma
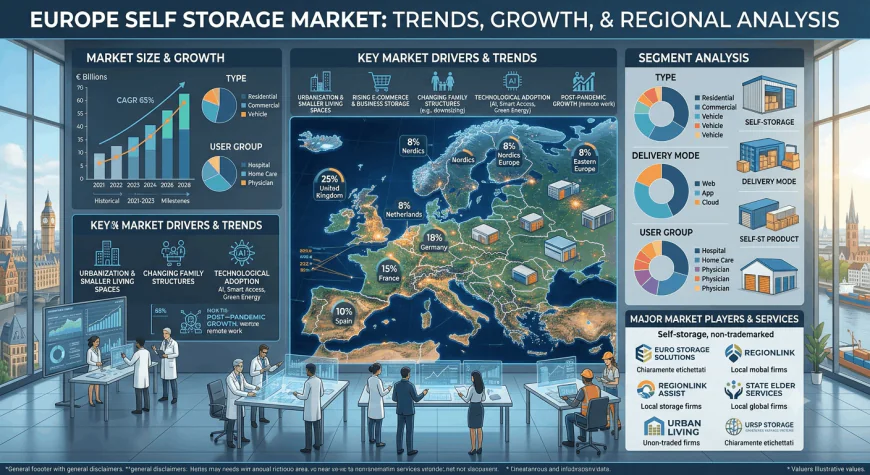
European urban households are facing a space crisis that shows no sign of abating. Apartments in major cities are being delivered with less storage per resident, rental housing markets generate frequent moves, and small businesses increasingly need flexible inventory space without committing to long commercial leases. The solution for millions of consumers and entrepreneurs has become external storage—secure rooms rented on flexible terms that can scale up or down as circumstances change. The Europe self storage market sits at the centre of this urban necessity. Growing from USD 27.40 billion in 2025 to USD 28.19 billion in 2026, the market is projected to reach USD 35.38 billion by 2034, exhibiting a compound annual growth rate of 2.88 per cent during 2026-2034. These figures reflect a mature but still-expanding industry that has become a mainstream urban service.
What's Driving Growth of Europe's Self Storage Market?
Urban densification and shrinking homes are creating structural demand. New apartments in major European cities are being delivered with less storage space per resident. Households turn to external rooms to hold seasonal items, sports gear, and furniture that no longer fits. This trend is particularly pronounced in dense urban catchments where living space commands premium prices and every square metre must justify its cost.
Residential mobility and life events generate predictable storage needs. Moving, renovation, separation, and bereavement create predictable storage demand. Rental-heavy housing markets in Germany and the Nordics generate frequent moves, lifting short-cycle demand across urban catchments. A meaningful share of these short-term users convert into long-stay customers once their storage becomes routine, creating a stable revenue base.
E-commerce and small business inventory needs are expanding the customer base. Online sellers and service firms use storage rooms as low-cost, close-to-market inventory space. The flexibility to scale storage capacity with changing stock levels further supports demand among growing businesses. Business use is expanding as small retailers, tradespeople, and online sellers replace conventional warehouse leases with flexible rooms close to their customers and job sites.
Flexible leases and digital booking models are removing friction from the purchase journey. Month-to-month contracts, online reservation, and remote entry have eliminated the need to visit a sales office. Customers can compare, book, and access a unit entirely through digital channels, dramatically reducing the barriers to trial and making storage accessible to a broader demographic.
Three Trends Reshaping the Industry
Remote and unmanned site operations are democratising market access.
Operators are running smaller facilities without permanent on-site staff, using app-based entry, video surveillance, and centralised call teams. The model lowers the break-even occupancy for secondary towns and makes smaller catchments viable for expansion. This technology-enabled approach is allowing operators to serve markets that would previously have been uneconomic, extending storage services beyond major metropolitan centres.
Why it matters: Remote operation reduces the scale required for profitable operations, opening up under-served secondary markets.
Business implication: Operators must invest in access-control technology and centralised management systems to compete in smaller catchments.
Future impact: A distributed network of smaller, technology-enabled facilities will emerge, challenging the traditional model of large urban sites.
Conversion of redundant retail and industrial assets is accelerating supply delivery.
Vacant retail parks, older warehouses, and light industrial units are being converted into storage facilities. Conversion shortens delivery timelines against ground-up construction and gives operators well-located space at a lower entry cost. As retail landscapes evolve and physical stores close, these conversions represent a strategic opportunity for self storage operators to acquire prime urban sites without the lengthy planning processes associated with new construction.
Why it matters: Conversion reduces the time and capital required to bring new capacity to market.
Business implication: Operators must develop expertise in identifying and converting suitable industrial and retail assets.
Future impact: Conversion projects will become the primary method of market entry for operators in densely built European cities.
Sustainability and energy retrofits are reshaping asset valuations.
Rooftop solar, LED retrofits, and smart building controls are becoming standard across larger portfolios. Energy performance influences both operating costs and the valuation of assets held by listed and institutional owners. Operators are increasingly recognising that sustainability credentials are not merely ethical considerations but financial imperatives that affect their ability to access capital and attract environmentally conscious customers.
Why it matters: Energy efficiency directly impacts operating margins and asset valuations in an era of volatile energy costs.
Business implication: Operators must invest in energy-efficient infrastructure or face higher operating costs and potential valuation discounts.
Future impact: Sustainability credentials will become a prerequisite for institutional investment in self storage assets.
What the Market Numbers Actually Tell Us
A market expanding from USD 27.40 billion to USD 35.38 billion over nine years suggests steady commercial activity across facility operators, property developers, technology vendors, and investors. The 2.88 per cent compound annual growth rate signals a mature market where growth comes from new site development and wider digital customer acquisition rather than rapid demand expansion. Medium storage units dominate with a 45.7 per cent share, balancing affordability with usable capacity for household contents. Small storage units account for 32.5 per cent, anchored in compact city living and solo households. Personal use leads at 55.3 per cent, driven by relocation, renovation, separation, and downsizing events. Business use at 44.7 per cent is growing fastest as online sellers and tradespeople shift from conventional warehouse leases to flexible rooms. The United Kingdom commands a 39.2 per cent share, supported by high consumer awareness and a mature investment market for purpose-built storage assets. Germany follows at 19.8 per cent, while France at 15.7 per cent and Italy at 10.6 per cent represent significant but under-penetrated markets. Spain at 7.8 per cent is the fastest-growing country market, driven by low supply per capita and rapid network expansion in Madrid, Barcelona, and Valencia.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of under-penetrated markets and business storage. Spain, Italy, Portugal, and Poland offer far lower supply per capita than the United Kingdom, creating first-mover advantages for operators establishing sites in dense residential catchments. Purpose-designed rooms with loading access, longer opening hours, and parcel handling let operators serve online sellers and trades, lifting average tenancy length and revenue per square metre. Capitals flowing into ground-up development in under-supplied cities, conversion of redundant retail and industrial buildings, and platform acquisitions of regional chains. Technology investment is concentrated in access control, revenue management, and remote site operation. Leading operators including Safestore Holdings, Shurgard Self Storage, Big Yellow Group, and Groupe Rousselet are expanding lettable space through development, extensions, and selective acquisitions while strengthening digital customer acquisition. Companies that can navigate the complex planning landscape, secure prime urban sites, and develop technology-enabled operating models are well-positioned to capture value in this evolving market.