Europe Ceramic Tiles Market: How Digital Printing and Sustainable Design Are Transforming a Centuries-Old Industry
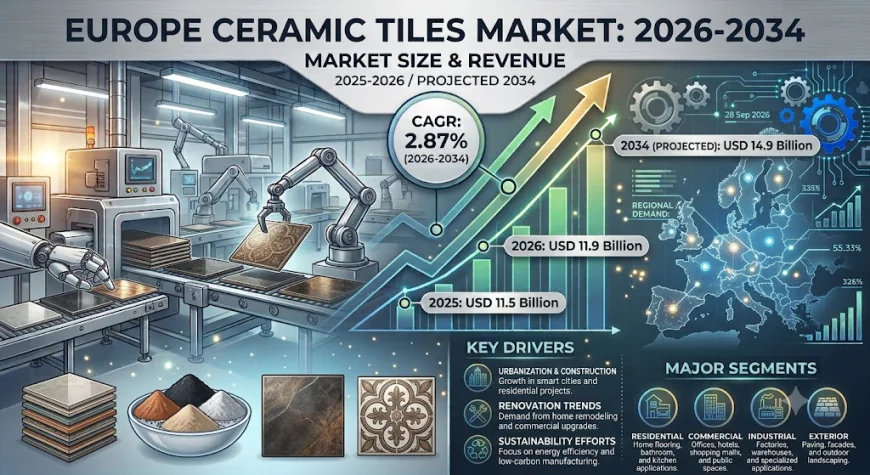
Europe ceramic tiles market increased from USD 11.5 Billion in 2025 to USD 11.9 Billion in 2026 and is expected to reach USD 14.9 Billion by 2034, growing at a CAGR of 2.87% during 2026–2034.
 Team Imarc
There is something quietly remarkable about an industry built on one of humanity's oldest manufacturing traditions fired clay that is now being reshaped by digital printing technology, augmented reality showroom tools, and EU energy efficiency mandates that have turned a decorative material into an active contributor to building sustainability performance. The European ceramic tiles market sits at this intersection of cultural heritage and technological reinvention, serving a continent where craftsmanship in ceramics has been a point of national identity for centuries particularly in Italy, Spain, and Portugal while simultaneously responding to a construction environment where design sophistication, hygiene standards, and environmental credentials are all rising as purchase criteria simultaneously.
The market data reflects this durable commercial momentum clearly. The Europe ceramic tiles market increased from USD 11.5 Billion in 2025 to USD 11.9 Billion in 2026 and is expected to reach USD 14.9 Billion by 2034, growing at a CAGR of 2.87% during 2026–2034. That consistent, compounding growth across a building materials category as mature and geographically established as ceramic tiles reflects the cumulative effect of infrastructure investment, renovation cycle activity, and a sustained shift in consumer expectations around design quality and environmental performance that is progressively raising the average value of each transaction across the market.
What's Driving Growth in the Europe Ceramic Tiles Market?
- Accelerating construction and renovation activity across the continent is providing the foundational demand that sustains the ceramic tiles market's consistent growth trajectory. Government initiatives aimed at housing development and energy-efficient building renovation — including programmes supporting deep renovation of existing building stock to meet EU energy performance targets — are generating consistent project pipelines that specify ceramic tiles for flooring, wall cladding, and façade applications across both new build and refurbishment contexts.
- Residential applications commanding the largest market share reflect the category's deep integration into European home renovation culture. As homeowners across Germany, France, Italy, and Spain pursue kitchen and bathroom upgrades the two renovation contexts where ceramic tiles offer unmatched combinations of durability, water resistance, and aesthetic versatility — the residential segment sustains demand volumes that neither commercial nor replacement channels can approach at equivalent scale.
- Floor tiles leading the type segment anchored by the growing adoption of underfloor heating systems across European homes, where ceramic's exceptional heat conductivity makes it the preferred flooring substrate, and by the expanding trend toward open-plan living spaces where continuous flooring from room to room drives large-area floor tile consumption that smaller format wall tile applications cannot match in volume terms.
- Italy's market dominance rooted in the country's unparalleled concentration of ceramic tile manufacturing expertise, design heritage, and technological innovation with Sassuolo's ceramic district producing world-leading brands including Marazzi, Florim, and Atlas Concorde that command premium positioning across European markets and set the design and technological benchmarks that competitors across the continent aspire to match.
- Rising hospitality and tourism sector investment across Southern and Central Europe is generating consistent commercial specification demand for ceramic tiles in hotel construction and refurbishment, resort development, restaurant fit-outs, and airport terminal upgrades applications where tiles' combination of high-traffic durability, easy maintenance, and design flexibility makes them the default commercial specification for floor and wall surfaces across virtually every hospitality project type.
Three Trends Reshaping the Industry
Digital printing technology enabling design capabilities that have redefined what ceramic tiles can look like
The integration of advanced digital and 3D printing technologies into ceramic tile manufacturing has produced a design revolution whose commercial consequences are still unfolding across the European market. Manufacturers are now capable of producing ceramic tiles with photorealistic reproductions of natural stone, timber, concrete, fabric, and metal surfaces at resolutions and dimensional accuracy that make the distinction from the original material genuinely difficult to discern at normal viewing distances. This capability is commercially transformative because it enables consumers to access the aesthetic appeal of premium natural materials marble, travertine, exotic hardwoods at the cost, hygiene, and maintenance profile of ceramic tile, while simultaneously enabling architects and interior designers to create entirely novel surface aesthetics that have no natural material precedent. The result is a category that has moved decisively beyond its historical positioning as a functional, hygienic surface covering into a design material whose specification is increasingly driven by aesthetic ambition rather than purely practical criteria. Leading manufacturers are extending this digital capability into 3D surface texturing that replicates the tactile dimensionality of natural materials alongside their visual characteristics further closing the perceptual gap between ceramic tile and the premium materials it emulates.
Sustainability and hygiene certification becoming mainstream specification criteria
Europe's position as the global leader in sustainable construction regulation is directly reshaping what ceramic tile manufacturers must demonstrate to win commercial and institutional specification. Tiles produced from natural materials clay, sand, and mineral pigments with manufacturing processes increasingly powered by renewable energy and incorporating recycled content in both body and glaze compositions are gaining specification advantages in green building certification schemes including LEED, BREEAM, and the EU's own Level(s) framework. The thermal mass properties of ceramic tile its ability to absorb heat during warm periods and release it gradually, moderating indoor temperature fluctuations are increasingly recognised in building energy modelling as a passive contribution to energy efficiency performance, adding a quantifiable sustainability credential to the material's existing durability and recyclability advantages. Simultaneously, the COVID-19 pandemic's lasting impact on hygiene consciousness is sustaining demand for antibacterial ceramic tiles treated with micronised silver compounds that inhibit bacterial and viral surface persistence a product category whose specification has expanded beyond its original healthcare and food service origins into mainstream residential and commercial applications where hygiene assurance has become a valued purchase attribute rather than a specialist requirement.
Augmented reality and digital visualisation transforming the consumer purchase journey
The integration of augmented reality and virtual reality tools into ceramic tile retail and specification processes is fundamentally changing how European consumers and architects make tile selection decisions and in doing so, is removing one of the category's most persistent friction points. The inability to visualise how a tile will actually look across an entire room, under specific lighting conditions, and in combination with other surface materials and furnishings has historically driven conservative specification decisions that favoured safe, neutral formats over the more distinctive and design-forward options that manufacturers would prefer to sell. AR tools that allow consumers to visualise their actual room with different tile selections applied in real time are enabling more confident specification of larger formats, bolder patterns, and premium-priced design tiles that consumers would previously have hesitated to commit to based on showroom samples alone. For manufacturers and retailers, this technology is simultaneously reducing return rates, increasing average transaction values, and creating a digital engagement layer with consumers that enables more sophisticated relationship marketing and personalisation than traditional tile showroom retail could support. Companies investing in proprietary AR visualisation platforms are building commercial infrastructure that converts a historically low-engagement purchase category into an immersive design experience — creating a meaningful competitive differentiator against rivals whose customer journey remains anchored in physical sample displays.
What the Market Numbers Actually Tell Us
The single-year growth from USD 11.5 Billion in 2025 to USD 11.9 Billion in 2026 before the CAGR of 2.87% compounds through to USD 14.9 Billion by 2034 reflects a market that is already in active, measurable expansion rather than early-stage recovery. Adding USD 3.4 Billion in cumulative annual market value over the forecast period across a construction materials category as geographically mature and culturally embedded as European ceramic tiles reflects the combination of residential renovation cycle activity sustaining consistent baseline demand, commercial construction responding to hospitality, healthcare, and infrastructure investment, and the progressive premiumisation of average transaction values as digital printing technology enables more consumers to specify design-led products at price points that were previously accessible only to premium residential and high-specification commercial projects. The replacement application segment's presence alongside residential and commercial channels signals that the market benefits from three distinct demand streams operating on different cycle timescales new construction, residential renovation, and commercial replacement providing structural resilience across different phases of the broader European construction investment cycle.
Where New Opportunities Are Emerging
The most commercially significant emerging opportunity in the Europe ceramic tiles market lies at the intersection of large-format porcelain panel technology and the commercial interior design sector's growing appetite for seamless, monolithic surface aesthetics that conventional tile formats and grout joints cannot deliver. Large-format porcelain panels produced in dimensions exceeding 120 × 60 centimetres and increasingly available in slab formats reaching 320 × 160 centimetres re enabling architects and interior designers to specify continuous surface treatments for floors, walls, countertops, and façades that eliminate the visual interruption of grout lines entirely, producing the kind of refined, high-end spatial aesthetic that premium hospitality, retail, and corporate interior projects demand. For manufacturers with the kiln technology and precision handling infrastructure to produce and transport these large-format panels without dimensional distortion or edge damage, this segment commands meaningfully superior pricing over conventional tile formats and is attracting a commercial specification audience luxury hotel developers, premium retail fitout contractors, and high-specification residential developers whose design priorities and willingness to pay create a margin environment that the commodity tile segment cannot replicate. Simultaneously, the growing specification of exterior façade cladding systems using frost-resistant, large-format ceramic panels across the European building renovation market where improving the thermal performance and aesthetic quality of ageing building envelopes is a stated EU policy priority represents a structurally new application category that extends the ceramic tiles market's addressable commercial opportunity well beyond its traditional interior floor and wall positioning.