Europe Carbon Black Market: Why the Electric Vehicle Revolution Is Rewriting Demand for an Industrial Staple
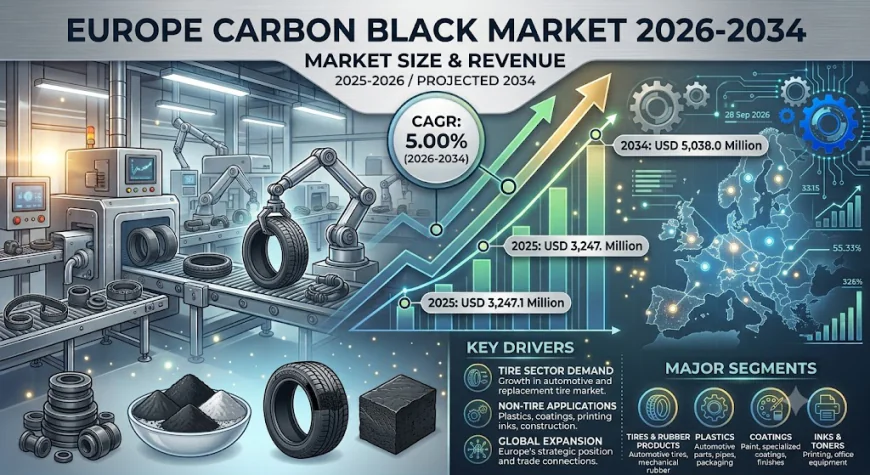
Europe carbon black market was valued at USD 3,247.1 Million in 2025 and is projected to reach USD 5,038.0 Million by 2034, growing at a CAGR of 5.00% during 2026–2034.
 Team Imarc
There is a material so foundational to modern industrial life that most people encounter its effects every single day without ever knowing it exists. Carbon black a fine powder produced through the controlled combustion of heavy petroleum products is what gives vehicle tires their durability, rubber seals their resilience, plastics their UV resistance, and printer inks their opacity. It is an unglamorous but commercially essential industrial chemical whose European market is now being reshaped by two forces pulling simultaneously in different directions: the accelerating transition to electric mobility, which is creating entirely new demand categories for specialty carbon black, and EU environmental regulation, which is fundamentally restructuring how the material is produced, sourced, and certified.
The market data captures the net commercial outcome of those competing forces clearly. The Europe carbon black market was valued at USD 3,247.1 Million in 2025 and is projected to reach USD 5,038.0 Million by 2034, growing at a CAGR of 5.00% during 2026–2034. That consistent, compounding growth trajectory across a chemically essential industrial material reflects a market that is simultaneously defending its established automotive and industrial demand base while actively building the specialty segments that will define its next decade of commercial expansion.
What's Driving Growth in the Europe Carbon Black Market?
- European automotive and tire manufacturing sustaining foundational demand with a reliability that is structurally built into the continent's industrial base. New car registrations in the EU reached approximately 10.6 Million Units in 2024, sustaining both original equipment and replacement tire channels that collectively account for the tire application segment's commanding 60% market share. Europe's concentration of world-leading tire manufacturers — all of whom require substantial and consistent carbon black volumes to maintain tread durability, rolling resistance performance, and structural integrity across their product ranges — creates the demand floor on which the entire market's commercial architecture is built.
- Furnace black's 74% market dominance reflecting the production technology whose unmatched versatility, scalability, and adaptability to both standard and specialty formulations make it the foundational carbon black type across every application in the European market. Furnace black's precisely controllable particle size distribution, surface area, and structure enable manufacturers to optimise performance characteristics for applications ranging from heavy-duty truck tires requiring maximum abrasion resistance to specialty coatings demanding uniform pigmentation and UV protection — a breadth of capability that no alternative production process can match at comparable commercial scale.
- EU Circular Economy Action Plan identifying recovered carbon black as a strategic secondary raw material is providing the regulatory foundation that is accelerating investment in pyrolysis-based recovery technology across the continent. The designation of recovered carbon black as strategically important signals that EU policy is actively directing supply chain investment toward circular production — creating commercial incentive for producers and tire manufacturers alike to build the infrastructure that transforms end-of-life tires from a waste stream into a certified feedstock.
- Electric vehicle adoption creating a structurally new and premium-priced demand segment as EV-specific tires require precisely engineered carbon black formulations with controlled particle morphology to achieve the low rolling resistance that maximises battery range without compromising grip or longevity. Beyond tires, carbon black is increasingly used as a conductive additive in lithium-ion battery electrodes — a technically demanding application that commands significant price premiums over commodity tire reinforcement grades and is positioning specialty carbon black as an essential material in Europe's clean energy transition.
- Standard grade's 76% market share anchoring the volume base through its widespread utilisation as a reinforcing filler in tire manufacturing and non-tire rubber goods — mechanical seals, conveyor belts, automotive hoses, and vibration dampeners — where its optimal balance of cost-effectiveness, tensile strength enhancement, and abrasion resistance improvement makes it the default specification across a manufacturing sector that consumes carbon black in volumes that specialty grades cannot approach at equivalent economics.
Three Trends Reshaping the Industry
Recovered carbon black transitioning from regulatory aspiration to commercial infrastructure
The shift toward recovered carbon black derived from end-of-life tire pyrolysis is moving decisively from pilot programme to committed industrial investment across Europe — and the pace of that transition is accelerating faster than the policy frameworks that initially incentivised it. Enviro Systems and Antin Infrastructure Partners' February 2024 signing of the final investment decision for a commercial-scale tire recycling plant in Uddevalla, Sweden — specifically designed to produce recovered carbon black — represents the kind of institutional capital commitment that signals an industry moving from feasibility validation to production scale. The commercial logic is compelling on multiple dimensions simultaneously: recovered carbon black reduces the market's dependence on petroleum-derived feedstocks whose pricing is chronically volatile, provides a certified circular credential that tire manufacturers need to meet their own sustainability commitments, and aligns with EU regulatory frameworks that are progressively tightening requirements on both polycyclic aromatic hydrocarbon content and recycled material incorporation across packaging and industrial applications. As Fastmarkets' growing coverage of recovered carbon black pricing signals, the material is maturing into a recognised, formally priced commodity category — the commercial infrastructure milestone that unlocks institutional procurement confidence and enables large-scale supply agreements between recyclers and tire manufacturers.
Specialty carbon black for EV and energy storage applications building the market's highest-margin growth segment
The electric vehicle transition is not reducing European carbon black demand — it is reshaping it toward higher-value, more technically demanding formulations that command meaningfully superior pricing over commodity tire reinforcement grades. Orion Engineered Carbons' expansion into conductive additives critical for high-voltage cable compounds and battery energy storage systems — leveraging its PRINTEX kappa product line — illustrates how leading producers are actively building commercial positions in EV-specific applications that did not represent material revenue opportunities five years ago. The technical requirements of battery-grade conductive carbon black — precise particle size distribution, controlled surface chemistry, and high electrical conductivity at minimal loading levels — require manufacturing sophistication and quality consistency that commodity furnace black production cannot readily deliver without significant process engineering investment. For European producers willing to make those investments, the specialty segment offers not only superior unit economics but also the customer relationship depth and switching cost architecture that provides commercial durability unavailable in the commodity tire reinforcement market where procurement is predominantly conducted through competitive tender.
Environmental compliance investment reshaping competitive dynamics in favour of technologically advanced producers
The cumulative burden of EU environmental compliance — covering REACH regulations on polycyclic aromatic hydrocarbons, industrial emissions directives, waste heat recovery requirements, and the emerging circular economy mandates — is creating a structural competitive bifurcation between producers with the capital and technical capability to invest in compliant production technology and smaller operators for whom the compliance cost burden represents an existential margin challenge. European producers are channelling resources into low-PAH production technologies, bio-based feedstock research, and co-generation systems that recover waste heat from carbon black production to supply both plant operations and regional power grids — investments that simultaneously reduce emissions and improve energy cost competitiveness in a market where energy costs represent a significant proportion of total production economics. Trade policy shifts restricting carbon black imports from certain non-European origins have further accelerated supply chain localisation, prompting manufacturers to strengthen regional production capabilities and reduce their exposure to the import competition from Asian producers that has historically pressured European pricing in commodity grade segments.
What the Market Numbers Actually Tell Us
A CAGR of 5.00% sustained over nine years across a foundational industrial chemical market reflects the compounding effect of automotive demand resilience, specialty segment premiumisation, and recovered carbon black's progressive substitution of virgin material — three growth mechanisms operating across different parts of the market simultaneously rather than any single driver pushing the entire market forward. The trajectory from USD 3,247.1 Million to USD 5,038.0 Million adds approximately USD 1.8 Billion in annual market value — distributed across tire manufacturers investing in EV-compatible formulations, industrial rubber goods producers benefiting from expanding manufacturing activity across Central and Eastern Europe, and the emerging recovered carbon black producers whose pyrolysis facilities are building the circular supply chain that EU policy is actively directing the market toward. For investors and operators, the market's moderate consolidation structure — with several established global manufacturers holding significant positions based on production network scale, product portfolio breadth, and deep customer relationships — creates both a stable competitive foundation and ongoing consolidation opportunity as compliance cost pressures accelerate the rationalisation of smaller producers unable to independently finance the regulatory investment burden.
Where New Opportunities Are Emerging
The most commercially significant emerging opportunity in the Europe carbon black market sits at the precise intersection of battery-grade conductive carbon black and the recovered carbon black certification infrastructure now being built across Northern and Western Europe. As European battery cell manufacturers — including Northvolt, ACC, and the growing pipeline of gigafactory developments across Germany, France, and Eastern Europe — seek to align their supply chains with the EU's Battery Regulation requirements for recycled content and carbon footprint disclosure, the producers who can supply conductive carbon black with certified circular credentials will occupy a uniquely differentiated commercial position. No currently scaled European producer has fully achieved this combination — making it the defining product development frontier for the market's next phase of competitive differentiation. Simultaneously, the increasing scrutiny on tire particle abrasion as an environmental pollutant — with the EU for the first time incorporating tire particle emissions into vehicle environmental standards — is compelling tire manufacturers to develop advanced compound formulations with optimised carbon black integration that minimise particle release without compromising safety performance, creating a sustained R&D procurement pipeline for the specialty carbon black producers capable of co-developing next-generation tire compound solutions alongside their largest customers.