Europe Aluminium Cans Market: How the Circular Economy Is Turning a Packaging Format Into an Investment
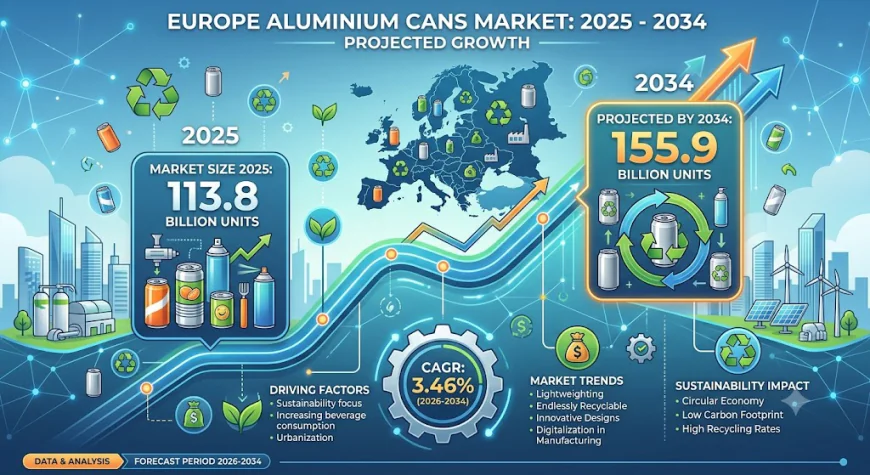
Europe aluminium cans market reached 113.8 Billion Units in 2025 and is projected to reach 155.9 Billion Units by 2034, expanding at a CAGR of 3.46% during 2026–2034.
 Team Imarc
There is a packaging material that can be recycled indefinitely without losing any of its properties, that chills faster than glass, weighs a fraction of what competing formats require, and that European consumers are already sorting and returning at collection rates exceeding 90% in leading markets. That material is aluminium — and the can format built around it is quietly becoming one of the most commercially compelling packaging investment stories on the continent, driven not by trend but by the structural alignment between what aluminium offers and what European regulation is increasingly demanding.
The market data captures that structural momentum clearly. The Europe aluminium cans market reached 113.8 Billion Units in 2025 and is projected to reach 155.9 Billion Units by 2034, expanding at a CAGR of 3.46% during 2026–2034. For a packaging category this mature and this widely distributed, adding over 42 Billion Units in annual volume over nine years reflects the compounding effect of three simultaneously operating growth forces — rising sustainability preferences, growing canned beverage consumption, and continuous product innovation — each of which independently reinforces the other two.
What's Driving Growth in the Europe Aluminium Cans Market?
- Rising consumer and regulatory preference for infinitely recyclable packaging is fundamentally reordering the competitive landscape between packaging formats across Europe. The EU's Packaging and Packaging Waste Regulation — with general application beginning August 12, 2026 — establishes lifecycle-wide requirements for packaging design, composition, and recyclability, with all packaging placed on the EU market required to be economically recyclable by 2030. Aluminium's infinite recyclability without material degradation positions it as the packaging format most naturally aligned with this regulatory direction, creating a structural commercial advantage over competing materials that cannot make the same claim.
- Sustained and growing canned beverage consumption is anchoring the market's dominant application segment at 82.6% share in 2025. The United Kingdom soft drinks market alone reached a record value of GBP 26.3 Billion in 2025, reflecting the broad-based consumer appetite for canned carbonated soft drinks, beer, energy drinks, and juices that sustains baseline volume demand across all European markets regardless of individual country growth rates. Crown Holdings' Q2 2026 report confirming a 7% increase in European beverage can volumes underscores that this demand expansion is active and measurable rather than projected.
- Germany's market leadership anchoring regional commercial confidence with a 24.8% share in 2025 provides the proof point that the largest and most infrastructure-sophisticated European economy views aluminium cans as a long-term packaging category worthy of sustained investment. Germany's combination of large beverage manufacturing capacity and deposit return scheme infrastructure achieving can collection rates above 90% creates the circular economy model that EU policy is progressively directing all member states to replicate.
- Continuous product innovation in easy-open and resealable can formats is broadening the addressable application base beyond conventional one-time-use beverage packaging into categories where can reclosability was previously a structural barrier to adoption. Canovation and CANPACK's June 2026 collaboration to advance the patented CanReseal all-aluminium resealable can-end technology toward commercial readiness is a direct commercial response to consumer demand for convenience that the current standard can format cannot fully satisfy.
- Premium branding and advanced decoration technology is elevating the can from commodity packaging into a brand communication medium capable of competing with glass and premium PET formats on shelf appeal. High-definition 8-colour wet-on-wet UV offset printing, tactile varnish application, embossing, and metallic finish effects are enabling brands to create differentiated, limited-edition packaging with the kind of premium visual execution that was previously achievable only in glass — at a fraction of the weight and with far superior recyclability credentials.
Three Trends Reshaping the Industry
EU circular economy policy creating a regulatory tailwind of unprecedented commercial scale
The EU's Circular Economy Act and Packaging and Packaging Waste Regulation represent the most commercially consequential regulatory development in European packaging in a generation — and aluminium cans are positioned as the natural beneficiary. The EU's own analysis estimates that circular measures could deliver 20–25% of the emissions reductions required for climate neutrality by 2050, with packaging a central component of that contribution. Deposit return scheme expansion — already operational in Germany, Sweden, and the Netherlands at collection rates above 90% — is being progressively adopted across additional EU member states, creating the infrastructure that transforms the regulatory aspiration for recyclable packaging into a commercially functional closed-loop system. For aluminium can manufacturers, this policy direction is not a compliance cost — it is a structural competitive advantage over glass and PET competitors whose recyclability credentials are materially weaker and whose circular economy positioning is correspondingly more difficult to sustain under intensifying regulatory scrutiny.
Capacity expansion and strategic M&A reshaping the competitive architecture
The scale of capital being committed to European aluminium can manufacturing capacity is itself a signal of the industry's long-term confidence in the market's growth trajectory. Ball Corporation's December 2025 agreement to acquire an 80% stake in Benepack's European beverage-can business for approximately EUR 184 Million — covering production facilities in Belgium and Hungary — directly strengthens Ball's manufacturing footprint across both Western and Eastern Europe simultaneously, capturing both the established demand of mature Western markets and the growth potential of Eastern European markets where rising beverage consumption and expanding recycling infrastructure are creating accelerating category penetration. This acquisition strategy reflects institutional confidence that the volume trajectory from 113.8 Billion Units to 155.9 Billion Units requires committed manufacturing capacity to be in place ahead of demand rather than responsive to it — a capital discipline that favours well-resourced incumbents over new market entrants.
Food can application expansion diversifying the market beyond its beverage foundation
The aluminium can's commercial story has historically been written almost entirely in the language of beverages. The emerging chapter being written in food packaging represents a meaningful structural diversification that is expanding the total addressable market in ways that beverage volume growth alone cannot. Food application currently holds an 11.4% share in 2025 — modest relative to the 82.6% beverage dominance, but commercially significant and growing. Dozz's September 2025 launch of the United Kingdom's first chilled, ready-to-eat soup packaged in a 100% recyclable aluminium can — designed for consumption straight from the pack without heating or utensils — illustrates the kind of application innovation that is introducing aluminium cans to entirely new purchase occasions and retail environments. As consumers increasingly value on-the-go meal solutions that combine convenience, sustainability, and extended shelf life, the aluminium can's technical properties — hermetic sealing, temperature retention, and infinite recyclability — align naturally with the functional requirements of this growing food application category.
What the Market Numbers Actually Tell Us
Adding 42 Billion Units in annual volume over nine years — across a market base that already spans the full spectrum of European beverage and food consumption from southern Spain to Scandinavia — reflects the cumulative effect of deposit return scheme expansion increasing consumer return behaviour, regulatory pressure shifting brand procurement away from less sustainable packaging formats, and the continuous expansion of the canned beverage product universe into new drink categories and premium segments. The geographic distribution of the market — with Germany at 24.8%, the United Kingdom at 19.6%, France at 15.8%, Italy at 12.4%, Spain at 10.2%, and the remaining 17.2% concentrated in Central and Eastern European markets where growth rates are running above the continental average — provides a structural resilience that single-market dependency cannot offer. North German aluminium billet premiums rising sharply amid high energy costs and supply disruptions to USD 1,175–1,250 per ton in May 2026 from USD 560–600 in February represent the primary cost headwind the market is navigating — but for manufacturers with established recycled aluminium supply relationships and closed-loop deposit return infrastructure, the exposure to primary metal price volatility is progressively diminishing as recycled content ratios increase.
Where New Opportunities Are Emerging
The most commercially significant emerging opportunity in the Europe aluminium cans market sits at the intersection of food application expansion and the resealable can format technology now moving toward commercial readiness. A resealable aluminium can that maintains the format's recyclability credentials while enabling partial consumption and reclosure opens an entirely new product category — portable, shelf-stable, recyclable food and beverage packaging suitable for meal replacement, functional nutrition, and premium beverage applications that the current one-time-open standard can cannot address. For manufacturers and brands that invest early in resealable format capability, this represents a first-mover advantage in a sub-segment that could command meaningfully higher per-unit pricing than conventional can formats — improving margin structure while simultaneously expanding the total addressable market beyond the beverage categories that currently define the competitive conversation. Simultaneously, Central and Eastern European markets — currently representing 17.2% of regional volume but growing faster than the continental average as beverage consumption rises and deposit return infrastructure is progressively installed — offer geographic expansion opportunity for manufacturers willing to commit capacity ahead of the demand maturity that makes these markets as commercially dense as Germany and the United Kingdom already are.