Service Exporters in India: Managing Foreign Payments and GST Refunds
Learn about EPCG export obligation closure, EODC documentation, e-BRC verification, and GST refund compliance for Indian exporters. Explore essential records, export realisation requirements, and practical steps to avoid documentation errors.
 Getmyca Work
India has a growing service export sector that includes IT companies, consultants, design agencies, engineering service providers and professional service firms.
These businesses regularly invoice international clients and receive payments through authorised banking channels.
While service exports differ from physical goods exports, accurate financial records and appropriate tax compliance remain important.
Understanding the documentation requirements helps businesses avoid errors when reporting export income or preparing GST refund claims.
Why Is Payment Realisation Important for Service Exporters?
Exporters should maintain records connecting overseas customer invoices with payments received.
Service agreements, bank statements, remittance references and accounting entries help establish the nature of the transaction.
A single overseas payment may sometimes cover several invoices, making proper allocation necessary.
Businesses should also review whether the transaction meets the relevant regulatory conditions for export of services.
Simply receiving payment from a foreign customer does not automatically establish GST export eligibility.
What Is the Role of e-BRC in Export Documentation?
The electronic Bank Realisation Certificate provides information relating to export payment realisation.
The DGFT system uses inward remittance information transmitted through participating banks.
Exporters can review applicable records and complete the prescribed matching procedure where relevant.
DGFT has also introduced additional fields for certain services export transactions, making accurate classification and payment information important.
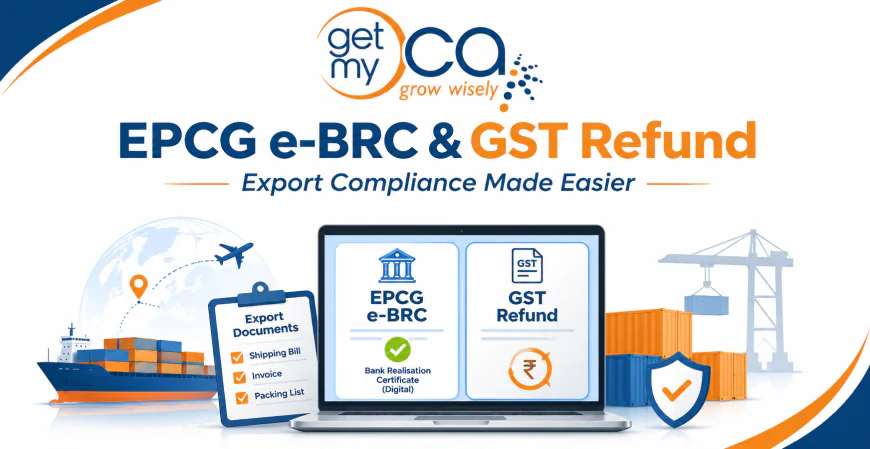
Businesses reviewing EPCG e-BRC updates and DGFT requirements should distinguish between general electronic realisation procedures and the specific requirements of their export activity.
EPCG benefits themselves apply only where the business and relevant transaction satisfy the scheme conditions.
When Can Service Exporters Claim GST Refunds?
Export of services is subject to conditions under the Integrated Goods and Services Tax framework.
These conditions include the location of the supplier and recipient, applicable place-of-supply rules and prescribed payment requirements.
Qualifying zero-rated service exports may create opportunities for refunds under the relevant GST provisions.
Businesses making eligible supplies without payment of IGST under a valid Letter of Undertaking may be able to claim accumulated eligible Input Tax Credit.
However, the actual claim depends on applicable rules and supporting information.
Professional GST refund services for service exporters can help businesses review eligibility, transaction records and prescribed calculations.
What Records Should Be Reviewed Regularly?
Service exporters should maintain:
-
Overseas customer contracts.
-
Service invoices and supporting agreements.
-
Bank remittance details.
-
Applicable e-BRC information.
-
GST returns and purchase records.
-
LUT documentation, where relevant.
-
Eligible ITC calculations.
-
Refund applications and departmental correspondence.
Businesses should ensure that the service description, customer information and payment records accurately reflect the underlying transaction.
How Can Service Exporters Improve Compliance?
Companies should reconcile international customer receipts every month and investigate unmatched payments.
They should also review the applicable place-of-supply rules and maintain separate records for domestic and overseas transactions.
Before preparing a refund claim, the finance team should verify all legal conditions rather than assuming every international invoice qualifies.
Conclusion
Service exporters benefit from maintaining accurate agreements, invoices and banking records.
Proper documentation supports financial reporting, DGFT-related procedures where applicable and GST refund preparation.
Regular reconciliation and correct transaction classification can reduce avoidable compliance difficulties.