How Remote Pathology Consultations Are Reshaping Digital Diagnostic Workflows
The software segment is projected to grow at a CAGR of 10.4% during the forecast period, driven by digital workflow platforms, AI integration, automated image analysis, and data management requirements.
 Eknath Girhepunje
The global digital pathology market is transforming diagnostic workflows through whole-slide imaging, artificial intelligence (AI), and digital image management technologies. Healthcare providers are adopting digital solutions to improve tissue analysis, support remote pathology consultations, and streamline laboratory operations. Growing demand for efficient disease diagnosis, centralized pathology services, and AI-assisted image analysis is creating opportunities for technology providers across healthcare and pharmaceutical research.
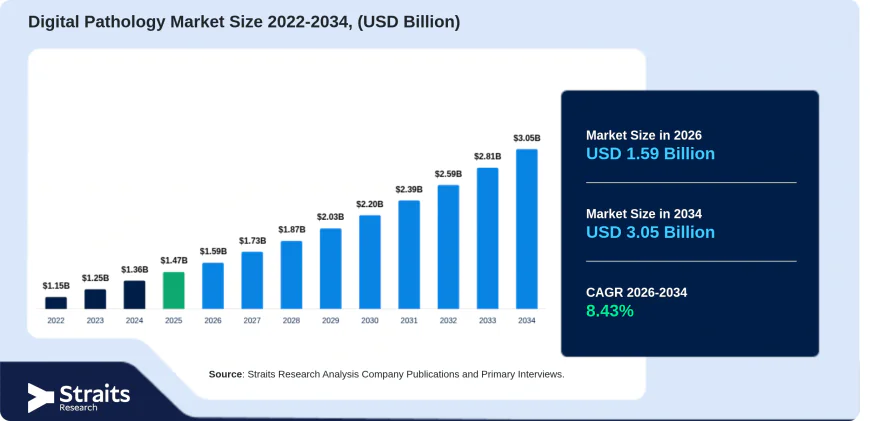
The global digital pathology market size was valued at USD 1.47 billion in 2025 and is projected to grow from USD 1.59 billion in 2026 to USD 3.05 billion by 2034, registering a CAGR of 8.43% during the forecast period from 2026 to 2034. North America dominated the market with a 41.6% share in 2025.
For detailed market insights, growth forecasts, and competitive analysis, visit:https://straitsresearch.com/report/digital-pathology-market
Market Drivers
Remote Consultation and Centralized Pathology Services
The need for specialist pathology expertise across geographically separated healthcare facilities is encouraging the adoption of digital systems that support remote case review. Digital pathology platforms allow hospitals to share high-resolution tissue images with specialists for second opinions without physically transferring glass slides. Centralized laboratory workflows also help healthcare networks consolidate specialized resources and pathology expertise. These requirements support investment in secure image-sharing platforms, data storage, and remote diagnostic solutions.
Integration of Artificial Intelligence in Pathology Workflows
AI is supporting the analysis of large volumes of whole-slide images and helping pathologists assess tissue characteristics more consistently. Automated image analysis can support quantitative evaluation, identify relevant tissue features, and improve research workflows. The FDA's qualification of the AI-based AIM-NASH tool in 2025 for assessing liver biopsy features in MASH clinical trials demonstrates the role of AI in standardized histological evaluation. Such developments are encouraging investment in AI-enabled digital pathology software.
Adoption of Whole-Slide Imaging for Routine Diagnosis
Whole-slide imaging enables high-resolution digital examination of tissue samples and supports image sharing across healthcare facilities. Pathologists can review scanned slides through digital viewing platforms, supporting remote collaboration and clinical workflows. The technology also provides a foundation for AI-based image analysis and digital consultation. Greater adoption of whole-slide imaging is supporting demand for scanners, software, and image management systems.
Market Challenges
Digital Infrastructure and Data Storage Requirements
Digital pathology systems generate large volumes of high-resolution image data that require secure storage, reliable networks, and efficient image management. Healthcare facilities may need to invest in servers, cloud infrastructure, cybersecurity, and data backup systems. These infrastructure requirements can increase implementation costs, particularly for smaller diagnostic laboratories and hospitals.
Integration with Existing Laboratory Workflows
Integrating digital pathology platforms with existing laboratory information systems, diagnostic equipment, and hospital infrastructure can be complex. Differences in software compatibility, data formats, and workflow procedures may require additional technical support and system customization. These challenges can delay implementation and affect the transition from conventional microscopy to digital diagnostic processes.
Regulatory Compliance and Diagnostic Reliability
Digital pathology technologies used for clinical diagnosis must meet applicable regulatory and performance requirements. Image quality, software reliability, data security, and validation are important considerations when adopting digital diagnostic systems. Healthcare providers must ensure that digital platforms support dependable interpretation and fit established clinical procedures, which can increase evaluation and implementation requirements.
Market Segmentation
The digital pathology market is segmented by product, type, application, and end use. By product, the market includes software, devices, scanners, slide management systems, and storage systems. The device segment dominated with a 46.8% share in 2025, supported by its role in digital slide acquisition and diagnostic workflows. The software segment is projected to grow at a CAGR of 10.4% during the forecast period, driven by digital workflow platforms, AI integration, automated image analysis, and data management requirements. By type, the market includes human pathology and veterinary pathology. Human pathology accounted for a 91.3% share in 2025 and is expected to grow at a CAGR of 9.4%, supported by applications in disease diagnosis, cancer screening, tissue analysis, and clinical decision-making. Veterinary pathology supports digital examination and documentation of tissue samples in animal healthcare. By application, the market includes drug discovery and development, academic research, disease diagnosis, and others. Disease diagnosis dominated with a 42.6% share in 2025 due to demand for accurate and efficient tissue analysis. Drug discovery and development is expected to grow at a CAGR of 9.8%, supported by its use in preclinical research, biomarker evaluation, and pharmaceutical development. By end use, the market covers hospitals, biotech and pharmaceutical companies, diagnostic laboratories, and academic and research institutes. Hospitals accounted for a 38.9% share in 2025. Biotech and pharmaceutical companies are projected to grow at a CAGR of 9.9%, driven by digital pathology applications in drug discovery, biomarker analysis, and preclinical research.
Regional Insights
North America dominated the digital pathology market with a 41.6% share in 2025. In the U.S., FDA regulatory developments involving whole-slide imaging and AI-enabled pathology software are supporting the clinical integration of digital diagnostic technologies. In Canada, developments in whole-slide image quality-control solutions and research funding for AI-based tissue image analysis are supporting innovation in digital pathology. Asia Pacific is projected to be the fastest-growing region, registering a CAGR of 11.6% during the forecast period. Japan and China are advancing digital pathology networks, AI-assisted diagnostic technologies, and whole-slide imaging adoption. South Korea's regulatory framework for AI-based tissue pathology software supports evaluation of digital medical devices, while India's government-backed initiatives are encouraging AI-assisted screening, digital slide imaging, and remote pathology analysis. Europe accounted for a 27.4% share in 2025. In the U.K., NHS digital pathology implementation and investments in digital diagnostics and histopathology automation are supporting wider adoption. Germany is advancing AI-based image analysis through platforms such as Fraunhofer IIS's MIKAIA. France is also pursuing a national digital pathology roadmap focused on laboratory digitization, AI integration, and investment in scanners, software, servers, and storage. Middle East and Africa is projected to grow at a CAGR of 7.9% during the forecast period. In the UAE, healthcare initiatives focused on AI, advanced diagnostics, and precision medicine may support adoption of digital pathology and AI-assisted workflows. Across Africa, efforts to improve pathology capacity and expand access to cancer diagnostics are creating potential applications for digital pathology, tele-expertise, and image-based diagnostic services.
Key Players Analysis
The digital pathology market includes medical imaging companies, healthcare technology providers, pathology solution developers, and specialized software companies. Key players include: - Oracle Health - Philips Healthcare - Siemens Healthineers - GE HealthCare - Tempus AI Established companies compete through image quality, scanner accuracy, software capabilities, AI integration, interoperability, data security, and regulatory compliance. Emerging providers focus on cloud-based platforms, AI-enabled image analysis, compact scanning technologies, and customized software solutions.
Conclusion
The digital pathology market is expected to maintain steady growth through 2034 as healthcare providers adopt whole-slide imaging, AI-assisted analysis, and remote diagnostic workflows. North America remains the leading market, while Asia Pacific is projected to record the fastest growth. Devices currently dominate the product segment, whereas software and biotech and pharmaceutical applications present notable growth opportunities. Continued investment in digital infrastructure, regulatory development, and AI-enabled pathology solutions will shape the industry's future.
About Us
Straits Research provides market intelligence, industry analysis, market forecasts, and competitive assessments across global industries. Its research helps organizations understand market dynamics, identify opportunities, and make informed strategic decisions.
Contact Us
Website: https://straitsresearch.com
Email: [email protected]
U.S.: +1 646 905 0080
India: +91 8087085354
U.K.: +44 203 695 0070