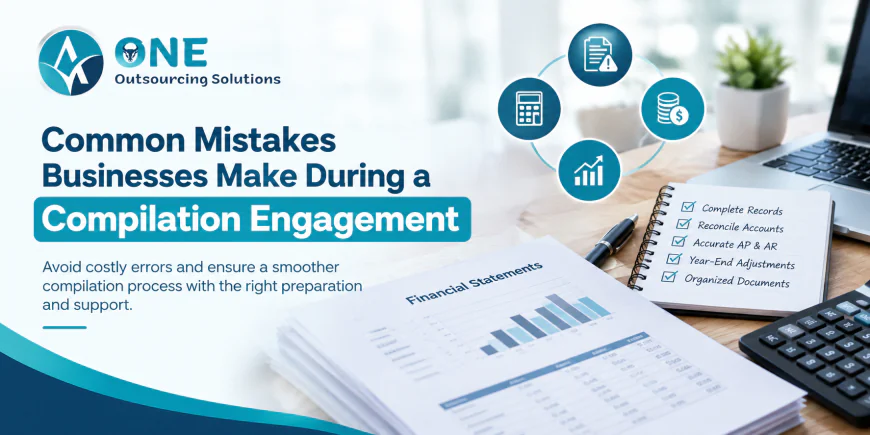
Common Mistakes Businesses Make During a Compilation Engagement
Understanding the most common mistakes can help business owners and management teams prepare properly and make the compilation process more efficient.
 Aone Outsourcing Canada
A compilation engagement helps Canadian businesses prepare financial statements based on information provided by management. While it is generally less extensive than a review or audit, businesses still need to provide accurate, complete, and well-organized financial information to ensure the process runs smoothly.
Under CSRS 4200, a compilation engagement involves the practitioner assisting management with compiling financial information into financial statements based on the applicable financial reporting framework. Because the quality of the final statements depends heavily on the information provided by the business, avoidable mistakes can lead to delays, inconsistencies, and additional work.
Understanding the most common mistakes can help business owners and management teams prepare properly and make the compilation process more efficient.
1. Providing Incomplete Financial Records
One of the most common mistakes is providing incomplete financial information to the accountant.
Businesses may submit bank statements and general ledger reports but overlook important records such as:
-
Credit card statements
-
Loan statements
-
Investment records
-
Fixed asset information
-
Payroll records
-
Expense receipts
-
Sales records
-
Tax documents
Missing information can make it difficult to properly compile the financial statements and may require additional follow-up with management.
Before the engagement begins, businesses should prepare a complete set of accounting records and supporting documents.
2. Not Reconciling Bank Accounts
Bank reconciliation is an important part of maintaining accurate accounting records. However, some businesses wait until year-end to identify differences between their accounting records and bank statements.
Unreconciled transactions can result from:
-
Outstanding cheques
-
Bank fees
-
Electronic payments
-
Deposits in transit
-
Duplicate transactions
-
Unrecorded transactions
Regular bank reconciliations can help identify these issues before the compilation engagement begins.
3. Poor Accounts Payable Records
Another common problem is inaccurate or incomplete accounts payable information.
Outstanding supplier invoices may be missing from the accounting system, recorded under incorrect vendors, or entered in the wrong accounting period. These issues can affect expenses and liabilities reported in the financial statements.
Businesses can reduce these problems by maintaining organized vendor records and ensuring invoices are recorded promptly. Companies that need additional support can consider professional Account Payable Services to improve invoice processing, vendor management, payment tracking, and AP reporting.
4. Not Keeping Accounts Receivable Up to Date
Accounts receivable can also create problems during a compilation engagement.
Businesses sometimes have:
-
Old unpaid customer invoices
-
Incorrect customer balances
-
Duplicate invoices
-
Unrecorded customer payments
-
Credit notes that have not been applied
-
Balances that require collection review
Keeping accounts receivable records current makes it easier to determine the amount actually outstanding from customers.
Businesses with a large volume of customer transactions may benefit from professional Accounts Receivable Services to help maintain accurate customer records, monitor outstanding invoices, and improve collections processes.
5. Mixing Personal and Business Expenses
Small business owners sometimes use business accounts for personal expenses. When these transactions are not properly identified, they can make the accounting records more difficult to analyze.
Examples include:
-
Personal purchases made using a business credit card
-
Personal withdrawals
-
Family expenses paid through the company
-
Personal subscriptions charged to the business
Business and personal transactions should be clearly separated and properly recorded.
6. Failing to Record Year-End Adjustments
Some businesses provide their accounting records without considering year-end adjustments that may be required.
Depending on the business and financial reporting framework, adjustments may relate to:
-
Accrued expenses
-
Prepaid expenses
-
Depreciation
-
Inventory
-
Deferred revenue
-
Interest
-
Loans
-
Payroll liabilities
Management should discuss relevant year-end information with the accounting professional so that the financial statements can be prepared appropriately.
7. Ignoring Old Outstanding Balances
Old balances in accounts receivable, accounts payable, loans, or other accounts should not simply be carried forward without review.
For example, an accounts receivable balance that has remained unpaid for several years may require management's attention. Similarly, an old payable may have already been paid but not properly recorded.
Reviewing aging reports and other account balances before the engagement can help identify unusual or outdated items.
8. Not Communicating Changes to the Accountant
Businesses sometimes fail to tell their accountant about significant changes during the year.
These may include:
-
New loans
-
New business locations
-
Major asset purchases
-
Business acquisitions
-
Changes in ownership
-
New shareholders
-
Large unusual transactions
-
Changes in business operations
Providing this information early allows the accountant to better understand the financial information being compiled.
9. Waiting Until the Last Minute
Starting the compilation process too late can create unnecessary pressure.
Last-minute preparation may result in:
-
Missing documents
-
Unanswered accounting questions
-
Delayed financial statements
-
Additional bookkeeping work
-
Difficulty meeting financing or tax-related deadlines
Businesses should begin organizing their records well before the expected completion date.
10. Assuming a Compilation Is the Same as an Audit
One of the biggest misconceptions is assuming that a compilation engagement provides the same level of assurance as an audit.
A compilation engagement does not provide assurance in the same way an audit or review engagement does. The practitioner primarily assists management in compiling financial information into financial statements based on information provided by management.
Businesses should therefore understand the purpose of the engagement and determine whether a compilation, review, or audit is appropriate for their specific needs.
11. Not Maintaining Organized Supporting Documents
Even when accounting records are technically complete, poorly organized documentation can make the process more difficult.
Businesses should maintain organized records for:
-
Sales
-
Purchases
-
Payroll
-
Bank transactions
-
Loans
-
Fixed assets
-
Taxes
-
Accounts payable
-
Accounts receivable
A well-organized accounting system can make the compilation process faster and reduce unnecessary back-and-forth.
12. Choosing the Wrong Accounting Support
The quality of the financial statements depends heavily on the quality and completeness of the underlying accounting information.
If bookkeeping records are consistently incomplete or inaccurate, businesses may spend additional time correcting issues before the compilation can be completed.
Working with a professional provider of Compilation Engagement Services can help businesses prepare their financial information more efficiently and ensure that the engagement process is properly managed.
How to Prepare for a Compilation Engagement
Businesses can take several simple steps before the engagement begins:
-
Reconcile all bank and credit card accounts.
-
Review accounts receivable and accounts payable aging reports.
-
Record all outstanding invoices and expenses.
-
Gather loan and financing statements.
-
Review fixed asset records.
-
Separate personal and business transactions.
-
Organize supporting documentation.
-
Identify unusual or significant transactions.
-
Communicate important business changes to the accountant.
-
Start the preparation process early.
These steps can help reduce delays and make the compilation process more efficient.
Conclusion
A compilation engagement can provide Canadian businesses with properly compiled financial statements for their specific reporting needs. However, the process depends heavily on the accuracy, completeness, and organization of the information provided by management.
Incomplete records, unreconciled accounts, outdated receivables, inaccurate payables, missing year-end adjustments, and poor documentation are among the most common issues businesses should address before the engagement begins.
By maintaining accurate accounting records throughout the year and working with experienced professionals, businesses can make the compilation process smoother and more efficient.
If your business needs assistance preparing financial information and financial statements, professional Compilation Engagement Services can provide the accounting support needed to complete the process efficiently.