Building Financial Confidence Through Smarter Retirement Planning
A balanced portfolio should reflect personal risk tolerance, expected withdrawals, investment timelines, and other available income sources.
 edwardsasset
Understanding the Importance of Long-Term Financial Preparation
Retirement represents a significant life transition, bringing the freedom to pursue personal interests, spend time with family, and enjoy a comfortable lifestyle without depending on a regular paycheck. However, achieving this independence requires thoughtful preparation, realistic expectations, and consistent financial decisions. Many individuals underestimate the expenses associated with later life, particularly healthcare, inflation, and unexpected emergencies. Effective financial preparation helps address these challenges before they become overwhelming. By understanding available investment options and establishing clear financial priorities, individuals can develop a strategy that supports long-term stability and greater confidence throughout retirement.
The Role of Professional Financial Guidance
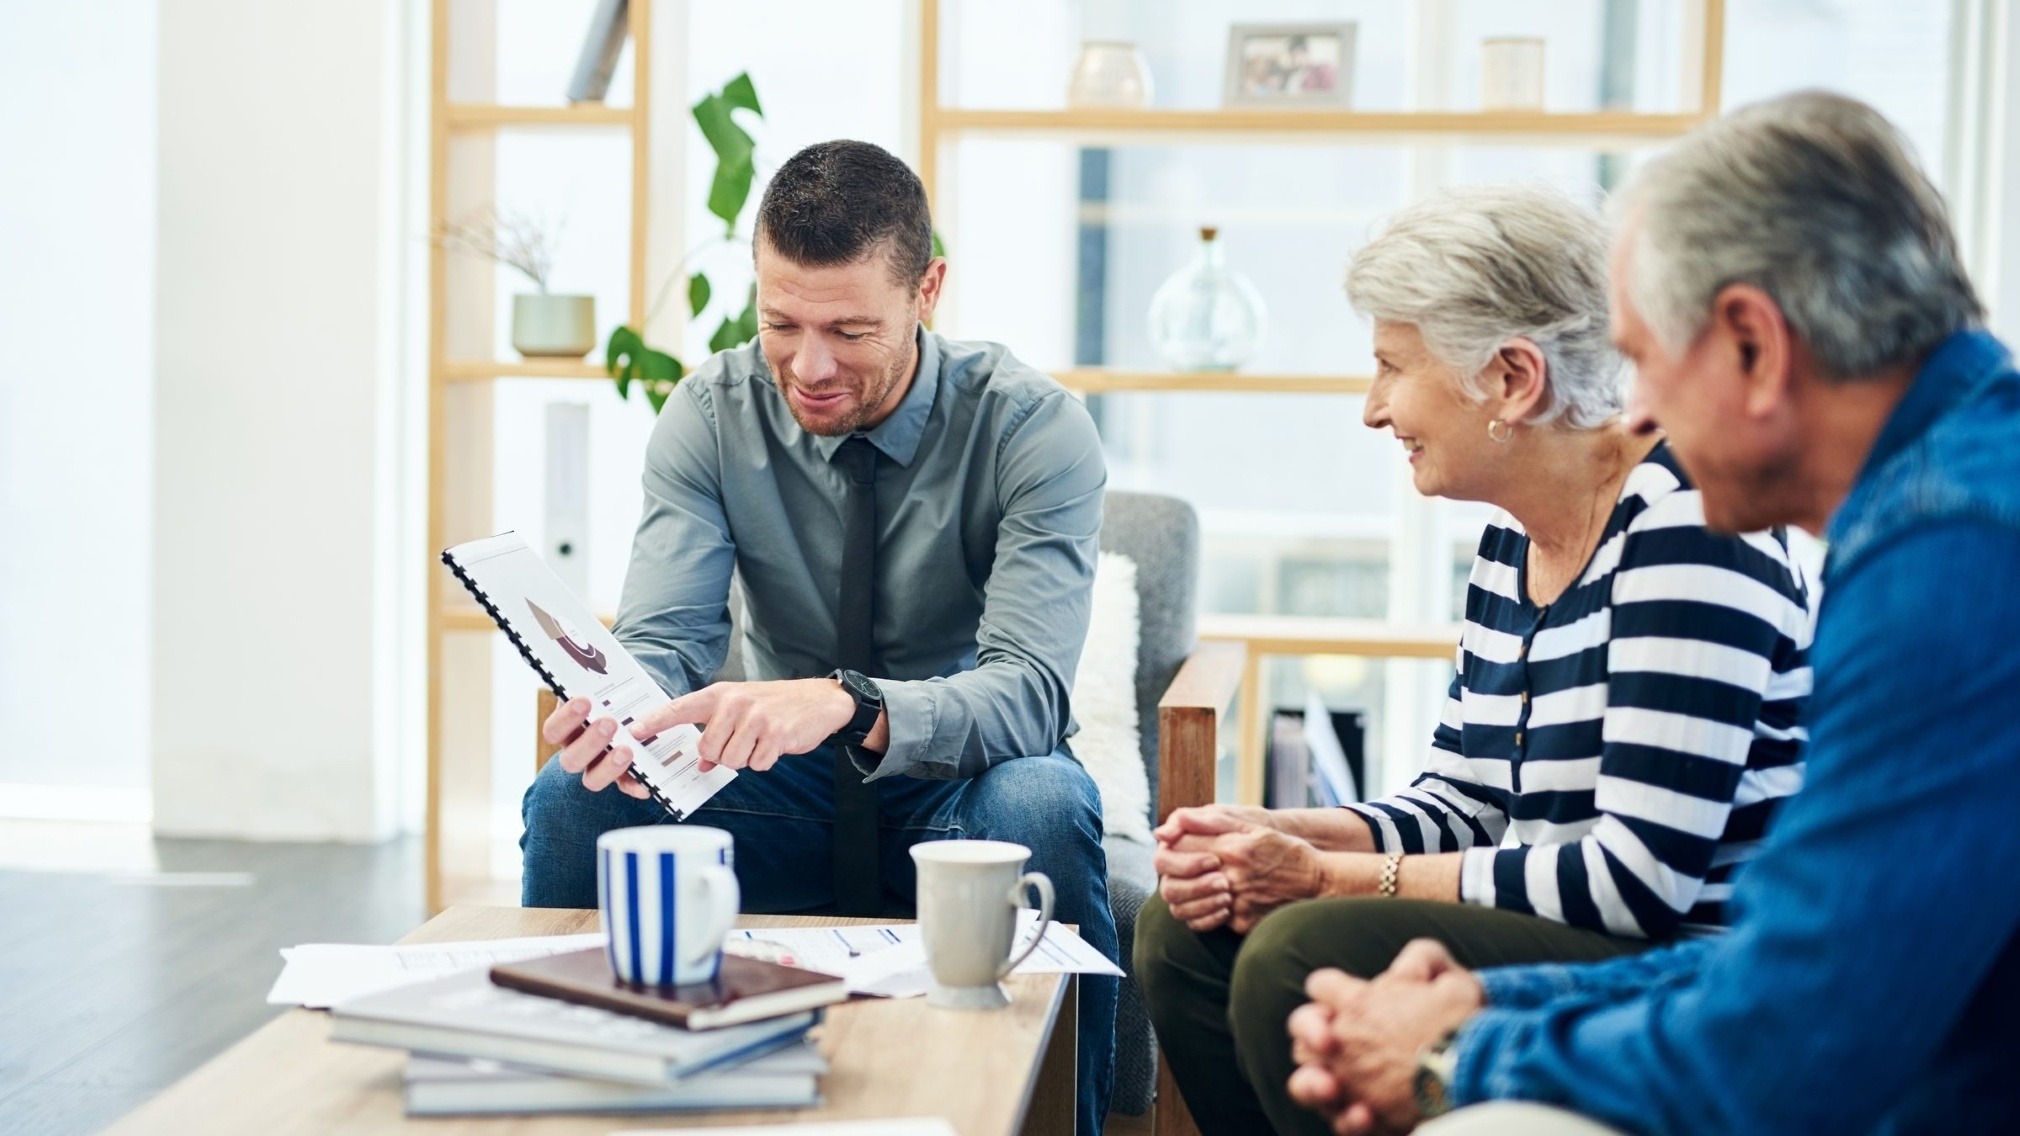
Managing personal finances becomes increasingly complex as investments, savings, taxes, and retirement goals begin to overlap. Professional guidance can help individuals evaluate their financial position and identify practical opportunities for improvement. Experienced advisers offering edwards asset management can assist with understanding investment risks, reviewing portfolio allocations, and establishing realistic expectations for future income. A well-designed strategy considers both present circumstances and anticipated financial responsibilities. Rather than relying on assumptions or short-term market movements, individuals benefit from a structured approach that connects everyday financial decisions with broader objectives, helping preserve resources while supporting changing needs over time.
Creating a Sustainable Retirement Income Strategy
Retirement planning involves more than accumulating a substantial savings balance. Individuals also need to determine how those resources will generate dependable income throughout retirement. Estimating living expenses, evaluating pension benefits, reviewing investment accounts, and considering potential healthcare costs can provide a clearer financial picture. An effective income strategy balances spending requirements with the need to preserve assets over an extended period. Because financial markets fluctuate and living costs change, regular assessments remain essential. Adjustments to withdrawals, savings contributions, and investment allocations can help maintain flexibility while reducing the likelihood of exhausting resources earlier than anticipated.
Why Local Knowledge Matters for Retirement Preparation
Financial circumstances often reflect the cost of living, housing arrangements, healthcare access, and lifestyle expectations associated with a particular location. For retirees considering Florida, retirement planning naples requires careful attention to property expenses, insurance premiums, healthcare needs, and everyday living costs. Understanding these factors can help individuals establish a realistic retirement budget rather than depending on broad national averages. Local considerations may also influence decisions about downsizing, relocating, or maintaining a second residence. By evaluating both current expenses and future possibilities, households can develop financial plans that reflect their preferred lifestyle while accounting for the practical realities of living in retirement.
Managing Investment Risk as Retirement Approaches
Investment decisions often change as individuals move from earning an income toward relying on accumulated assets. Younger investors may have greater capacity to tolerate short-term market fluctuations, while those approaching retirement typically need to consider liquidity and income stability more carefully. Nevertheless, avoiding growth-oriented investments entirely can create challenges when retirement may last several decades. A balanced portfolio should reflect personal risk tolerance, expected withdrawals, investment timelines, and other available income sources. Periodic portfolio reviews can help identify excessive concentration or unnecessary exposure. Maintaining diversification and a suitable cash reserve may also reduce pressure to sell investments during unfavorable market conditions.
Accounting for Inflation, Healthcare, and Unexpected Expenses
Even a carefully prepared retirement budget can become less reliable when expenses rise faster than expected. Inflation gradually reduces purchasing power, making future groceries, utilities, transportation, and medical services more expensive than their current equivalents. Healthcare deserves particular attention because insurance premiums, prescriptions, specialist appointments, and long-term care may create substantial financial obligations. Individuals preparing through retirement planning naples should evaluate these expenses alongside housing costs and discretionary spending. Emergency reserves can provide an additional layer of protection when unexpected repairs or medical bills arise. Incorporating realistic cost estimates and periodically updating assumptions helps retirement savings remain aligned with changing financial conditions.
Building Better Financial Habits Before Retirement
Strong retirement outcomes often develop through consistent habits rather than a single investment decision. Regular savings contributions, careful spending, responsible borrowing, and periodic financial reviews can steadily strengthen a household's position. Individuals should also understand how taxes, account withdrawal rules, and benefit eligibility may affect their future income. Reviewing beneficiary designations and organizing important financial documents can help simplify administrative responsibilities later. Families may benefit from discussing financial expectations early, particularly when supporting dependents or planning potential inheritances. These practical measures encourage informed decisions and reduce avoidable uncertainty, allowing retirement preparation to become a manageable process instead of a last-minute financial challenge.
Adapting Financial Plans to Changing Life Circumstances
Financial planning should remain flexible because personal goals and economic conditions rarely stay constant. A career change, unexpected inheritance, property purchase, health concern, or change in family responsibilities may require adjustments to existing arrangements. Periodic consultations with qualified financial professionals can help determine whether savings rates, investment strategies, insurance coverage, and income projections remain appropriate. Individuals exploring edwards asset management may find it useful to evaluate how different financial decisions affect their broader objectives. Reviewing progress at regular intervals also creates opportunities to identify gaps early, revise unrealistic assumptions, and preserve a clearer connection between available resources and long-term personal priorities.
Conclusion: Taking a Thoughtful Approach to Financial Security
A comfortable retirement depends on preparation, informed decision-making, and the willingness to adapt as circumstances evolve. Establishing clear goals, estimating future expenses, managing investment risks, and reviewing financial progress can help individuals approach later life with greater confidence. Professional guidance may also provide valuable perspective when financial decisions become complicated or competing priorities emerge. For individuals seeking additional information about financial planning services, Edwardsassetom offers a starting point for exploring relevant resources and considering available approaches. Ultimately, a practical financial strategy should reflect personal circumstances, realistic expectations, and the long-term objective of maintaining financial independence throughout retirement.