Australia Refrigerant Market Size, Share, Report 2026-2034
Australia's refrigerant market is set to grow from USD 666M to USD 1.42B by 2034. Explore low-GWP transition, cold chain growth, and opportunities.
 Ranjeet Sharma
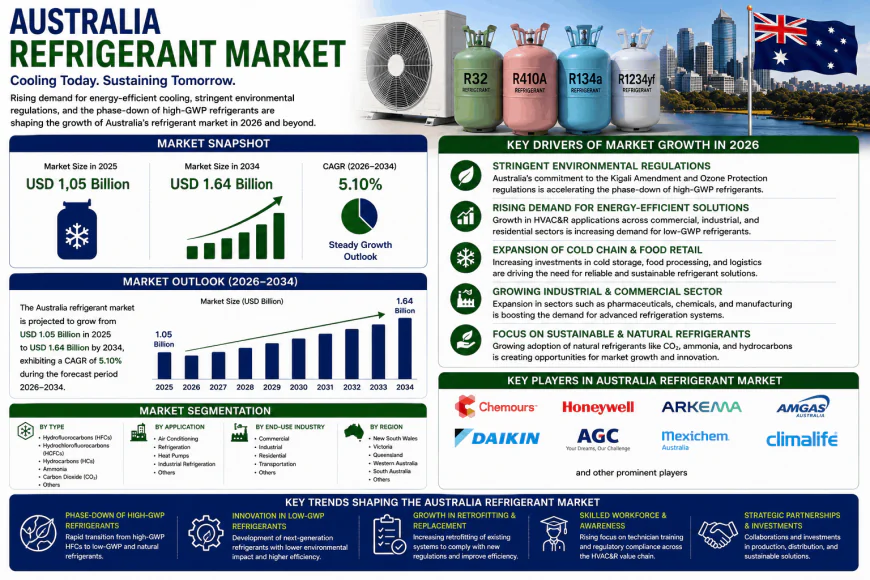
Australian HVAC technicians and cold chain operators are facing a transformation that reaches into every air conditioning unit and refrigerated warehouse in the country. The refrigerants that have powered cooling systems for decades are being phased down under environmental policy, replaced by alternatives with dramatically lower global warming potential. Meanwhile, demand for cooling continues to climb as temperatures rise and cold chain infrastructure expands to serve Australia's high-value agricultural exports. The Australia refrigerant market sits at the centre of this dual pressure. Valued at USD 665.9 million in 2025, the market is projected to reach USD 1,419.3 million by 2034, exhibiting a compound annual growth rate of 8.51 per cent during 2026-2034. These figures reflect an industry navigating regulatory transition while meeting growing demand.
What's Driving Growth of Australia's Refrigerant Market?
Regulatory shifts toward low-GWP refrigerants are reshaping the product landscape. The Australian Government's Ozone Protection and Synthetic Greenhouse Gas Management scheme imposes tight controls on hydrofluorocarbon imports, production, and usage. From 1 July 2024, the government planned to prohibit the import and production of small air conditioners with a GWP exceeding 750. This policy momentum is encouraging manufacturers to adopt low-GWP alternatives like hydrofluoroolefins, ammonia, CO2, and hydrocarbons.
Expanding cold chain infrastructure is driving demand across the food and beverage industry. Innovations in perishables such as dairy, meat, and seafood are driving demand for efficient refrigeration systems at all stages of storage, processing, and distribution. Australia's high-value agricultural exports require significant cold storage facilities to international standards. The IMARC Group predicts the Australia cold chain logistics market size will reach USD 7.1 billion by 2033, directly impacting refrigerant demand as more cooling systems are installed.
Increasing air conditioning adoption is accounting for most refrigerant consumption. Australia's average temperature increased by 1.44 ± 0.24°C since national records commenced in 1910, with every decade warmer than the previous since 1950. This warming drives high demand for air conditioning across residential, commercial, and industrial sectors. Urban development is facilitating HVAC installation in new homes, offices, shopping malls, and public facilities, with replacement cycles shifting toward new refrigerants including low-GWP blends.
Government energy-saving initiatives are accelerating the transition. Government-promoted schemes at the state level facilitate the transition to refrigerants that meet environmental standards. These programmes encourage consumers and businesses to replace older, less efficient systems with modern equipment using environmentally friendly refrigerants, accelerating the phase-down of high-GWP products.
Three Trends Reshaping the Industry
Natural refrigerants are gaining traction across commercial and industrial applications.
Policy momentum is encouraging air conditioner manufacturers to use low-GWP alternatives including natural refrigerants like ammonia, CO2, and hydrocarbons that have significantly lower environmental footprints. These substances offer zero or near-zero global warming potential, making them attractive for applications where regulatory compliance and environmental responsibility are priorities. Commercial refrigeration and industrial cooling systems are leading adoption, particularly in supermarkets and food processing facilities.
Why it matters: Natural refrigerants eliminate the regulatory risk associated with synthetic alternatives while delivering comparable performance.
Business implication: Manufacturers and installers must develop expertise in natural refrigerant systems, including safety protocols and training.
Future impact: Natural refrigerants will capture a growing share of commercial and industrial applications, displacing synthetic alternatives.
Retrofit activity is accelerating as existing systems transition to new refrigerants.
As units are replaced by newer, energy-efficient models, the shift toward new refrigerants including low-GWP blends is becoming more widespread. Existing systems are being retrofitted with new-generation refrigerants to comply with regulations and reduce environmental impact. This retrofit activity creates demand for compatible refrigerants, lubricants, and technical services, extending the lifecycle of existing equipment while meeting environmental standards.
Why it matters: Retrofit represents a cost-effective pathway for building owners to comply with regulations without replacing entire systems.
Business implication: Refrigerant suppliers must offer compatible retrofit solutions and technical support to capture this demand.
Future impact: The retrofit market will grow substantially as the HFC phase-down accelerates through 2034.
Cold chain investment is expanding refrigerant demand in food and beverage sectors.
Australia's high-value agricultural exports to various destinations require significant cold storage facilities up to international standards. Year-round availability of fresh and frozen products is encouraging retail chains and logistics firms to build refrigerated warehousing capacity and refrigerated transport fleets. Both have a direct impact on the refrigerant market as more cooling systems are put in place and existing systems retrofitted with new-generation refrigerants.
Why it matters: Cold chain expansion creates durable, recurring demand for refrigerants across the supply chain.
Business implication: Refrigerant suppliers must build relationships with cold chain operators and logistics providers to secure long-term contracts.
Future impact: As Australia's agricultural exports continue to grow, cold chain refrigerant demand will expand correspondingly.
What the Market Numbers Actually Tell Us
A market expanding from USD 665.9 million to USD 1,419.3 million over nine years suggests significantly greater commercial activity across refrigerant manufacturers, distributors, HVAC contractors, and cold chain operators. The 8.51 per cent compound annual growth rate signals robust, sustained expansion driven by regulatory transition and cooling demand growth. Fluorocarbon refrigerants currently dominate the product segment, though inorganic, hydrocarbon, and other alternatives are gaining share as regulations tighten. Commercial applications represent the largest segment, followed by industrial, domestic, and others. New South Wales and Victoria lead regional demand, reflecting population concentration and commercial activity. For investors and industry participants, the trajectory indicates that refrigerants are becoming an increasingly strategic component of Australia's cooling infrastructure, with growth driven by both replacement demand and new installations.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of regulatory compliance and technological innovation. Low-GWP alternatives including hydrofluoroolefins and natural refrigerants represent high-growth segments as the HFC phase-down accelerates. Retrofit services for existing systems offer a cost-effective pathway for compliance, creating demand for compatible refrigerants and technical expertise. Cold chain expansion, driven by Australia's agricultural exports and the projected growth of the cold chain logistics market to USD 7.1 billion by 2033, creates durable demand for refrigeration systems and refrigerants. Companies that can navigate the complex regulatory landscape, invest in low-GWP product development, and support customers through the transition are well-positioned to capture value in this evolving market. The industry's ability to balance environmental compliance with cooling performance will determine competitive positioning through 2034.