Australia Grocery Retail Market Size, Share, Report 2026-2034
Australia's grocery retail market is set to grow from USD 54.3B to USD 79.2B by 2034. Explore duopoly dynamics, online growth, and opportunities.
 Ranjeet Sharma
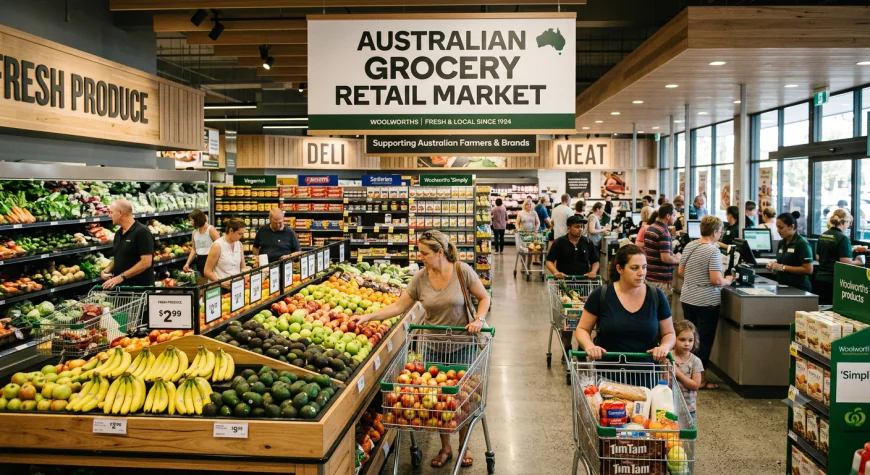
Australian grocery executives are navigating a landscape that would have seemed unthinkable a decade ago. The Woolworths-Coles duopoly, which has dominated the nation's food retail for generations, now faces unprecedented pressure on multiple fronts. The ACCC's Supermarkets Inquiry has created an adversarial regulatory environment, cost-of-living pressures are driving shoppers toward discount formats, and Amazon Fresh's potential large-scale entry threatens to disrupt online grocery economics. Yet beneath these challenges lies a market with formidable structural strengths: record migration-driven population growth, a grocery culture that prioritises fresh food, and a consumer base with one of the world's highest per-capita grocery expenditures. The Australia grocery retail market sits at the centre of this transformation. Valued at USD 54.32 billion in 2025, the market is projected to reach USD 79.23 billion by 2034, growing at a compound annual growth rate of 4.16 per cent from 2026 to 2034. These figures reflect an industry balancing regulatory pressure with demographic tailwinds.
What's Driving Growth of Australia's Grocery Retail Market?
Record net overseas migration is creating structural demand growth. Australia experienced record net overseas migration of 446,000 in 2023-24, adding new grocery consumers who typically maintain higher cooking frequency, higher fresh food spending, and specific category demand that mainstream supermarkets have responded to with expanded multicultural food sections. This migration wave is structurally beneficial beyond simple population addition, creating an enlarged consumer base contributing cumulative incremental grocery spend.
The accelerating online grocery channel is transforming channel dynamics. Australia's online grocery market is benefiting from both infrastructure investment and behavioural normalisation following COVID-19's forced adoption. Online grows fastest at approximately 7.8 per cent CAGR as Amazon Fresh expansion in Sydney and Melbourne builds infrastructure enabling same-day delivery at competitive economics. The channel's share has grown from 3 per cent pre-COVID to approximately 20 per cent by 2025.
Private label expansion is sustaining revenue growth amid value-seeking behaviour. Australia's grocery private label market growth, driven by both retailer investment in quality and range, and consumer willingness to substitute from branded to store-owned product in response to food inflation, is reshaping category dynamics. The success of Woolworths' Macro Wholefoods Market and Coles' Finest premium range demonstrates that consumers will pay premium prices for private label products perceived as superior quality.
Consumer premiumisation in health and wellness categories is elevating basket values. Health and sustainability values are reshaping category architecture as consumers increasingly prefer organic, plant-based, low-sugar, locally sourced, and eco-friendly products. Retailers are reorganising shelves, private labels, and online categories around wellness and responsible consumption, capturing premium demand while aligning with evolving shopper expectations.
Three Trends Reshaping the Industry
Automated fulfilment centres are transforming online grocery economics.
In June 2025, Woolworths and KNAPP achieved a major milestone with the launch of Woolworths' first fully automated Central Fulfilment Centre in Western Sydney. These automated systems are the physical infrastructure enabling Australia's online grocery market's economics to improve sufficiently for profitable delivery at competitive consumer prices. In March 2026, Woolworths switched on a $20 million high-tech "eStore" in St Mary's, doubling online delivery capacity for thousands of families across Western Sydney.
Why it matters: Automation is the prerequisite for sustainable online grocery market share growth beyond the 20 per cent penetration ceiling that expensive manual fulfilment would otherwise impose.
Business implication: Retailers must invest in automated fulfilment infrastructure or concede the online channel to more efficient competitors.
Future impact: Online penetration will push toward 28-30 per cent by 2034 as delivery economics approach parity with in-store shopping.
Private label premiumisation is building sustainable brand equity.
Private label premium tiers are emerging as retailers move beyond basic value products to offer higher quality, differentiated ranges. These premium private labels help supermarkets build stronger brand loyalty, improve margins, and compete with national brands. The premium private label tier represents the highest-margin, fastest-growing segment within grocery private label, commanding 20-35 per cent price premiums versus standard private label at gross margins 12-18 percentage points above branded equivalents.
Why it matters: Premium private label creates brand-equivalent revenues without the marketing investments that FMCG companies require.
Business implication: Retailers must invest in product development, quality assurance, and sustainable sourcing to build credible premium ranges.
Future impact: Private label penetration will cross 32 per cent of supermarket revenues by 2030, fundamentally altering retailer-supplier dynamics.
Retail media networks are creating high-margin revenue streams.
Retail media networks are emerging as supermarkets use their customer data, digital platforms, and in-store assets to sell targeted advertising to brands. This creates a high-margin revenue stream beyond traditional grocery sales while helping suppliers reach shoppers more effectively at the point of purchase. The first-party data advantage from loyalty programs is estimated to be worth AUD 500 million to 1 billion in annual retail media and product development value for Woolworths and Coles combined.
Why it matters: Retail media represents a competitive moat that ALDI cannot easily replicate, providing margin diversification beyond grocery sales.
Business implication: Retailers must develop sophisticated data platforms and advertiser relationships to capture this opportunity.
Future impact: Retail media will become a significant profit centre, potentially exceeding traditional grocery margins.
What the Market Numbers Actually Tell Us
A market expanding from USD 54.32 billion to USD 79.23 billion over nine years suggests significant commercial activity across grocery retailers, FMCG manufacturers, logistics providers, and technology suppliers. The 4.16 per cent compound annual growth rate signals steady, population-driven expansion. Food and beverages dominate at 71.6 per cent, anchored by Australia's full-service supermarket model where fresh food, packaged grocery, and beverages drive weekly shopping missions. Hypermarkets and supermarkets lead the distribution channel at 48.9 per cent, despite online growing at 7.8 per cent CAGR. ACT and NSW command 33.4 per cent of market revenues, reflecting Sydney's concentration of high-income households and highest grocery expenditure density. For investors and industry participants, the trajectory indicates that grocery retail remains a resilient, defensive sector with growth driven by population expansion and channel evolution.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of online infrastructure, premium private label, and multicultural grocery. Australia's multicultural premium grocery segment is among the market's most underserved opportunities, with Asian-background households spending AUD 3,500-5,000 annually on specialty groceries that mainstream retailers only partially address. Meal kit and ready-to-cook grocery integration represents a format innovation increasing basket values while commanding premium pricing. Convenience format development in Australia's densifying urban apartment markets offers growth potential as traditional supermarket formats struggle to serve high-density living. Companies that can navigate the regulatory landscape, invest in automated fulfilment infrastructure, and develop premium private label ranges with credible health and sustainability positioning are well-positioned to capture value in this evolving market.