Australia Alcoholic Beverages Market Size, Share, Report 2026-2034
Australia alcoholic beverages market is set to grow from USD 33.1B to USD 40.3B by 2034. Explore RTD trends, premiumisation, and opportunities.
 Ranjeet Sharma
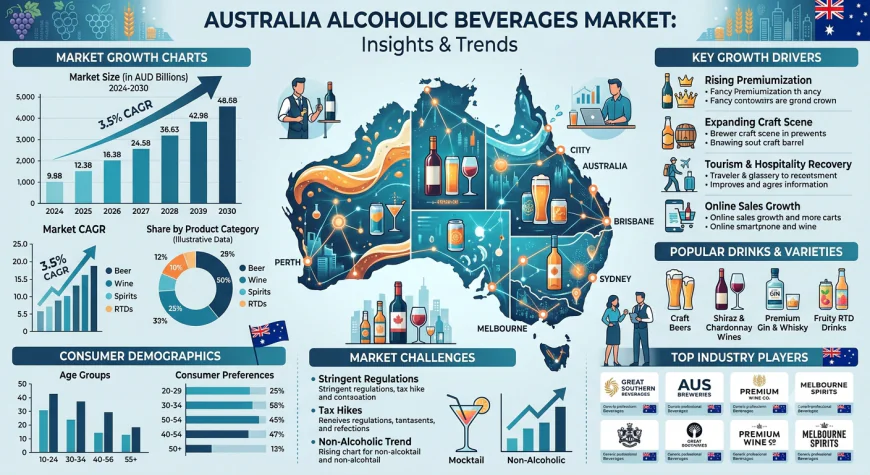
Australian beverage executives are confronting a cultural shift that would have seemed unimaginable a generation ago. Younger consumers are drinking less alcohol, not more. They want lighter options, bolder flavours, and products that fit their wellness-focused lifestyles. Yet they are also willing to pay premium prices for craft spirits with authentic stories and independent retail availability. This paradox—moderation alongside premiumisation—is reshaping the entire industry. The Australia alcoholic beverages market sits at the centre of this transformation. Valued at USD 33.1 billion in 2025, the market is projected to reach USD 40.3 billion by 2034, exhibiting a compound annual growth rate of 2.14 per cent during 2026-2034. These figures reflect a mature market where growth comes from value and innovation rather than volume expansion.
What's Driving Growth of Australia's Alcoholic Beverages Market?
Flavoured ready-to-drink products are capturing younger consumers. Australia's alcoholic beverages market has been witnessing a strong shift toward flavoured RTD options, particularly among millennials and Gen Z consumers. This preference is driven by demand for convenience, lower alcohol content, and more diverse flavour choices. Brands are now experimenting with botanicals, fruit infusions, and dessert-style notes, making the segment more vibrant. In December 2024, The Coca-Cola Company announced its acquisition of Billson's, a well-established Australian flavoured alcohol RTD brand, signalling serious commitment to building a stronger presence in the alcoholic drinks space.
Premiumisation is driving selective consumer behaviour and independent retail support. Australia's premium spirits category has gained momentum as drinkers become more selective, looking for superior quality, brand heritage, and exclusivity. Rather than opting for mass-market products, many buyers now prefer premium vodkas, tequilas, and whiskeys that showcase craftsmanship. Independent retailers are playing a key role by offering niche and imported products unavailable in mainstream outlets. In June 2024, Tovaritch! Premium Vodka officially launched in the Australian market, exclusively available through independent retailers.
A cultural shift toward moderate consumption is reshaping product portfolios. Young adults are increasingly seeking drinks that allow them to enjoy social experiences without excessive consumption, favouring low-alcohol beers, spritzers, and flavoured seltzers. This trend has encouraged manufacturers to diversify their portfolios with low-ABV and alcohol-free alternatives that do not compromise on taste. In March 2025, XXXX, a renowned Queensland beer brand, entered the alcoholic ginger beer segment with a 3.5 per cent ABV drink, marking its first product in the category.
E-commerce and digital retail expansion are improving access and convenience. Online channels continue to support wider product access, enabling consumers to discover niche brands and premium products unavailable in their local stores. This channel is particularly important for independent retailers and craft producers seeking to reach consumers beyond their immediate geographic area.
Three Trends Reshaping the Industry
Flavoured RTDs are becoming the entry point for younger drinkers.
Australia's alcoholic beverages market has witnessed a strong shift toward flavoured ready-to-drink options, particularly among millennials and Gen Z consumers. Brands are experimenting with botanicals, fruit infusions, and dessert-style notes, making the segment more vibrant and accessible to consumers who might otherwise avoid traditional beer, wine, or spirits. The RTD category is no longer limited to simple mixes—it has become a platform for innovation and experimentation.
Why it matters: Flavoured RTDs attract consumers who value taste, convenience, and lower alcohol content over traditional product categories.
Business implication: Legacy brands must innovate with new flavours and formats or risk losing younger consumers to agile competitors.
Future impact: RTDs will continue gaining share from traditional beer and wine categories, reshaping the competitive landscape.
Alcohol-free alternatives are moving from niche to mainstream.
In March 2025, Lyre's partnered with Amber Beverage Group as its exclusive distributor in Australia, strengthening its market presence and expanding access to its 14 non-alcoholic spirits and RTD range. This move supports rising demand for alcohol-free alternatives driven by health-conscious Australian consumers. The moderation trend has encouraged manufacturers to diversify their portfolios with low-ABV and alcohol-free alternatives that do not compromise on taste.
Why it matters: Alcohol-free products allow brands to retain consumers who are reducing alcohol intake without leaving the category entirely.
Business implication: Manufacturers must invest in alcohol-free product development and distribution partnerships to capture this growing segment.
Future impact: Alcohol-free alternatives will become a permanent fixture on retail shelves, competing directly with traditional alcoholic products.
Independent retail is becoming a premium spirits battleground.
Rather than opting for mass-market products, many buyers now prefer premium vodkas, tequilas, and whiskeys that showcase craftsmanship. Independent retailers are playing a key role in meeting this demand by offering niche and imported products unavailable in mainstream outlets. The exclusive availability of brands like Tovaritch! Premium Vodka through independent retailers offers them a fresh edge in the premium vodka segment, helping them compete with larger retail chains.
Why it matters: Independent retailers are becoming destinations for consumers seeking unique, premium products.
Business implication: Brands must develop independent retail strategies that leverage exclusivity and storytelling to capture premium consumers.
Future impact: The premium spirits segment will continue to fragment, with independent retailers playing an increasingly important role in brand discovery and trial.
What the Market Numbers Actually Tell Us
A market expanding from USD 33.1 billion to USD 40.3 billion over nine years suggests steady commercial activity across brewers, distillers, wineries, distributors, and retailers. The 2.14 per cent compound annual growth rate signals a mature market where growth comes from premiumisation, innovation, and category diversification rather than volume expansion. Beer represents a significant category, while spirits are gaining share driven by premiumisation. Wine remains important, with still light wine and sparkling wine serving different consumer occasions. Flavoured products are growing faster than unflavoured, reflecting changing consumer preferences. Glass bottles remain the dominant packaging type, though tins are gaining traction for RTDs and convenient formats. Supermarkets and hypermarkets represent the largest distribution channel, while on-trade, specialist retailers, and online channels serve specific consumer needs. New South Wales and Victoria lead regional demand, reflecting population concentration and hospitality activity. For investors and industry participants, the trajectory indicates that alcoholic beverages remain a resilient category with growth driven by value and innovation.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of moderation and premiumisation. Flavoured RTDs represent a high-growth segment attracting younger consumers who might otherwise avoid traditional alcohol categories. Alcohol-free alternatives are gaining traction as consumers seek wellness-focused options without abandoning social drinking occasions. Premium spirits offer higher margins and attract consumers willing to pay for craftsmanship and authentic stories. Independent retail partnerships provide access to consumers seeking unique products unavailable in mainstream outlets. Companies that can navigate the regulatory landscape, invest in product innovation, and develop premium brand narratives are well-positioned to capture value in this evolving market.