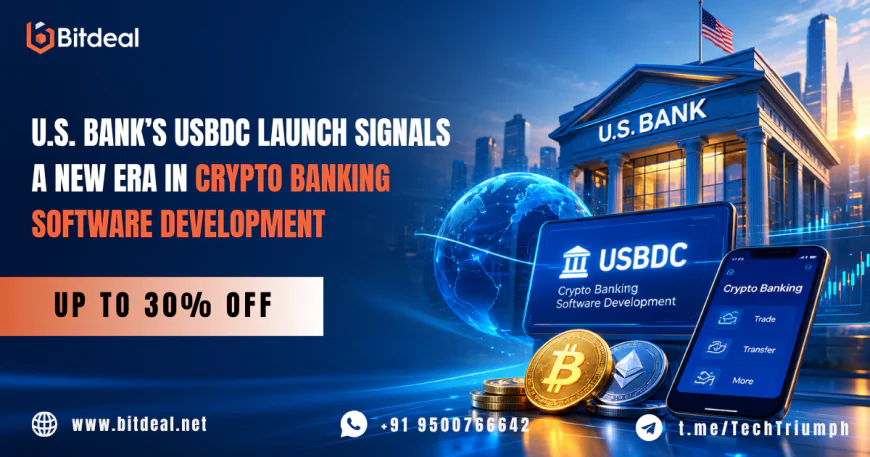
U.S. Bank’s USBDC Launch Signals a New Era in Crypto Banking Software Development
U.S. Bank's USBDC pilot shows why crypto banking software development is shifting from asset support to full infrastructure integration.
 Laura Bennett
Banking and blockchain have circled each other for years, but U.S. Bank’s USBDC pilot shows how closely the two are now converging. Its proprietary dollar-backed stablecoin has been used to move value between the bank’s North American and European entities through the public Stellar network, alongside its existing Digital Asset Platform and banking infrastructure. The development highlights a shift toward blockchain-enabled banking, where stablecoin payments, compliance, blockchain integration, and settlement become part of the same financial software ecosystem.
U.S. Bank's USBDC Puts Stablecoins Into a Banking Context
USBDC is a stablecoin issued by a regulated bank, not a crypto-native company. The pilot tested minting, redemption, freezing, and clawback - capabilities that mirror how banks already manage risk and compliance, just in blockchain terms. The cross-border transfer between U.S.
Bank's own entities offer a concrete use case: 24/7 transaction capabilities beyond correspondent-banking windows. What makes USBDC notable is that it integrates with the bank's existing finance, risk, and compliance infrastructure, rather than running as a standalone crypto payment system.
Crypto Banking Moves From Asset Support to System Integration
"Crypto banking" has often meant letting customers buy, hold, or trade digital assets through a custodial layer bolted onto legacy systems. USBDC is structurally different: a stablecoin built for settlement and payment movement, connected through banking APIs into blockchain networks, with compliance controls built in from the start. Banks no longer need software that just displays crypto balances - they need blockchain banking integration that moves money the way core banking systems already do.
The New Software Layer Behind Blockchain-Enabled Banking
Underneath a pilot like USBDC sits a fairly specific software stack, and the complexity is in making each piece behave like banking infrastructure rather than a standalone crypto tool:
-
Stablecoin transaction processing
-
Digital asset and wallet management
-
Connectivity between fiat and crypto
-
Blockchain integration layers
-
Payment and settlement orchestration
-
KYC, AML, and security controls
Together, these components form the stablecoin payment infrastructure needed for traceable, controlled, and compliant digital asset transactions.
How Bitdeal Approaches Crypto Banking Software Development
Bitdeal is a crypto banking software development company that connects digital asset capabilities with the infrastructure, controls, and workflows financial businesses already rely on, with a focus on five key capability areas.
Banking-Grade Crypto Platform Development
Stablecoin and digital asset platforms are designed around the risk, compliance, and audit controls a bank's teams already expect, so the ledger technology changes without the operational discipline changing with it.
Stablecoin Payment and Settlement Integration
Covering issuance, redemption, and cross-border movement, stablecoin flows are connected to existing payment rails, letting settlement processes reconcile cleanly against a bank's core ledgers.
Digital Asset and Wallet Management
Wallet infrastructure tracks custody, balances, and transaction history with full audit trails, keeping a stablecoin balance as accountable on the books as a deposit account.
Blockchain and Banking System Integration
The connective layer links banking systems to public or permissioned networks, so banking infrastructure and blockchain systems can operate together rather than as bridged workarounds.
Security, KYC and AML Enablement
KYC and AML checks are built directly into the transaction flow, so screening, monitoring, and controls like freezing or clawback are native to payment processing, not bolted on afterward.
Conclusion
USBDC is one pilot, but it points to where the industry is headed. U.S. Bank isn't replacing traditional banking with blockchain - it's demonstrating how blockchain can operate alongside existing banking infrastructure, under the same finance, risk, and compliance controls the industry already relies on. The broader takeaway: crypto banking solutions increasingly need to work within banking-grade infrastructure, where payments, compliance, risk management, and settlement operate as part of one connected system.