India Electric Vehicle Charging Station Market to Reach USD 1,078.8 Million by 2034, at a CAGR of 6.82%
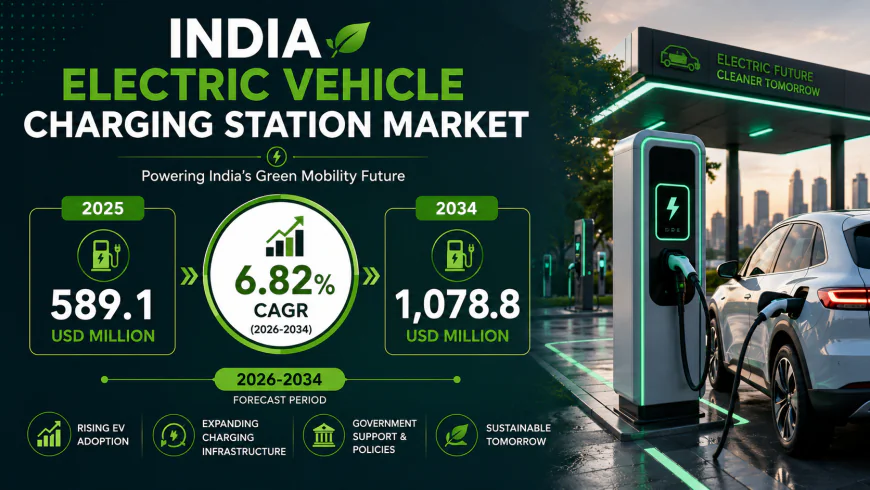
The India electric vehicle charging station market valued at USD 589.1 Million in 2025, is projected to reach USD 1,078.8 Million by 2034, growing at a CAGR of 6.82% from 2026 to 2034.
 Bhumika
How is India Electric Vehicle Charging Station Market Performing?
India's electric vehicle (EV) charging station sector is undergoing one of its most consequential transformations in decades. Rapid EV adoption across two-wheelers, three-wheelers, and passenger segments, landmark policy frameworks, and a technology revolution sweeping through charging hardware and software layers are collectively pushing the market toward a scale that would have seemed ambitious just five years ago.
The India electric vehicle charging station market valued at USD 589.1 Million in 2025, is projected to reach USD 1,078.8 Million by 2034, growing at a CAGR of 6.82% from 2026 to 2034. Behind that number is a structural story — one driven by policy ambition, fleet electrification, and digital infrastructure working in concert.
Market Statistics At-A-Glance
- Market Size (2025): USD 589.1 Million
- Projected Size (2034): USD 1,078.8 Million
- CAGR (2026–2034): 6.82%
- By Application: Commercial segment holds 79.2% market share in 2025, driven by fleet electrification commitments and logistics operator demand.
- By Charging Level: Level 3 leads with 58.7% market share owing to high per-unit hardware value and expressway corridor deployment.
- By Region: North India has the largest share of 33.8%, supported by Delhi-NCR's high EV penetration and active policy environment.
- Market competition features both utility-backed incumbents and technology-led CPO startups focusing on network expansion and smart charging platforms.
Key Drivers Behind India's EV Charging Station Market Growth
- Government Policy Support and FDI Liberalization
The single most transformative policy driver in India's EV charging sector has been sustained government commitment through schemes such as FAME II and PM e-DRIVE, which have accelerated charging infrastructure rollout through capital subsidies, public charging targets, and incentives for ecosystem participants. The Ministry of Power's mandate for public charging infrastructure at commercial complexes, combined with BIS IS 17017 standards and OCPP compliance requirements, has created regulatory certainty that directly supports CPO expansion and EVSE deployment across the country. - Rising EV Adoption and Fleet Electrification
India's rapid EV sales growth across two-wheelers, three-wheelers, and passenger segments is structurally expanding charging demand across residential, commercial, and public networks. Logistics, e-commerce, and ride-hailing operators including Ola Electric, BluSmart, Zomato, and Swiggy, are transitioning to EV fleets, driving demand for depot-based and high-utilization charging infrastructure. Commercial charging's 79.2% dominance in 2025 reflects this fleet-first electrification pattern, with delivery operators deploying 100,000+ electric vehicles requiring commercial hub charging in FY2025 alone. - Declining Hardware Costs and Domestic Manufacturing
Technology is not merely improving deployment economics, it is restructuring the value chain. Localization and scale in EVSE manufacturing are reducing charger and installation costs, improving project viability, and accelerating network expansion. Domestic manufacturing accounted for 44% of installed EVSE units in 2025, up from 28% in 2022, a structural shift with margin implications for global EVSE suppliers. Declining Level 2 EVSE costs, combined with improving battery economics, are making charging infrastructure more accessible for smaller CPOs and residential installations. - Fuel Retail Integration and Highway Corridor Expansion
Oil marketing companies like Indian Oil Corporation, Hindustan Petroleum Corporation Limited, and Bharat Petroleum Corporation Limited, are integrating EV chargers at existing fuel stations. Leveraging pre-built grid connectivity and land infrastructure enables faster, more capital-efficient rollout versus greenfield sites. Concurrently, deployment of 150–350 kW ultra-fast chargers is accelerating along high-traffic corridors, led by players such as ChargeZone, NTPC Limited, and Fortum, reducing charging time and enabling intercity EV travel. - Smart Charging and Software Platform Scaling
SaaS-driven CPMS platforms from Tata Power EZ Charge, Statiq, and Kazam are enabling interoperability, real-time monitoring, and subscription-based billing, with software emerging as a faster-growing layer of the value chain. DISCOM-led pilots by BESCOM and Maharashtra State Electricity Distribution Company Limited are introducing Time-of-Use tariffs and load management systems. Smart charging is emerging as a key tool to shift EV demand to off-peak hours and support grid stability, with AI-driven CPMS platforms using ML models to reduce grid overage costs by 12–18%.
➤ Evaluate Market Opportunity with the Business Sample Report
Key Market Challenges:
-
Low Utilization Rates and Project Economics remain the market's most significant financial constraint. Early-stage demand results in low charger utilization, impacting standalone project economics and extending payback periods for CPOs. Many public charging stations operate well below breakeven utilization thresholds, creating dependency on government subsidies and cross-subsidization from fleet contracts to remain viable in the early market phase.
-
Grid Infrastructure Limitations continue to constrain reliable deployment. Inconsistent power supply, limited transformer capacity, and elevated commercial tariffs in non-metro regions increase operating costs and reduce charger reliability. Upgrading grid infrastructure to support high-power DC fast charging requires coordination between CPOs, DISCOMs, and local authorities — a multi-stakeholder process that slows deployment velocity in Tier 2 and Tier 3 cities.
-
Demand–Supply Mismatch in Tier 2/3 Cities presents a chicken-and-egg problem. Limited charging visibility continues to hinder EV adoption in smaller cities, while proactive infrastructure deployment ahead of demand requires patient capital that many CPOs cannot access. This mismatch slows both EV adoption and charging network expansion in the high-growth potential markets beyond India's major metropolitan centers.
Market Segmentation Snapshot
Application Insights:
-
Commercial - The commercial segment dominates with a market share of 79.2% of the total India EV charging station market in 2025.
-
Residential
Charging Level Insights:
-
Level 3 - Level 3 leads with a share of 58.7% of the total India EV charging station market in 2025.
-
Level 2
-
Level 1
Regional Insights:
-
North India - North India exhibits a clear dominance with a 33.8% share of the total India EV charging station market in 2025.
-
South India
-
West and Central India
-
East India
How will the India EV Charging Station Market Evolve in the Coming Years?
India's EV charging station market is expected to evolve rapidly over the coming years, supported by rising EV adoption, government policy support, and technology advancements in charging hardware and software. The market is projected to reach nearly USD 1,078 Million by 2034, driven by increasing demand for commercial charging, highway corridor expansion, and smart charging platform scaling.
Consumers and fleet operators are becoming more sophisticated about charging speed, reliability, interoperability, and total cost of ownership. The industry is also being transformed by technological advancements such as ultra-fast 150–350 kW chargers, OCPP 2.0.1 interoperability, AI-powered load management, and renewable-integrated charging hubs. These innovations are improving charging efficiency, network utilization, and customer experience. Additionally, government initiatives focused on expanding charging infrastructure, standardizing connectors, and promoting domestic EVSE manufacturing are expected to strengthen market growth. The rise of technology-led CPO startups and greater foreign investment in charging networks will further encourage innovation, competitive pricing, and service quality improvements, making EV charging more accessible to a broader population across India.
Note: If you need specific information that is not currently within the scope of the report, we can provide it to you as a part of the customization.
Recent Developments & News
-
In March 2026, ChargeZone announced plans to set up over 1,000 supercharging stations across key national highway corridors by FY27, as it looks to expand high-speed charging infrastructure in line with rising electric vehicle adoption. This partnership aims to combine highway corridor access with fast-charging technology expertise, reinforcing market expansion driven by inter-city EV travel enablement.
-
In October 2025, Statiq (Sharify Services Pvt. Ltd.) announced it is seeking to raise $15 to 18 million in funding from new and current investors, reflecting strong investor conviction in technology-led charging network models and asset-light deployment strategies.
➤ Get a Custom Report Based on Your Business Needs
Competitive Landscape
The report offers an in-depth examination of the competitive landscape, including market structure, key player positioning, leading strategies for success, a competitive dashboard, and a company evaluation quadrant.
Key Highlights of the Report
-
Comprehensive analysis of historical trends (2020-2025) and forecast (2026-2034).
-
Detailed segmentation by charging station type, vehicle type, installation type, charging level, connector type, application, and region.
-
Insights into market dynamics including growth drivers, challenges, and technological trends.
-
Evaluation of competitive landscape with focus on network expansion and smart charging platforms.
-
Coverage of regulatory changes impacting charging standards and infrastructure mandates.
-
Market sizing in million USD with clear CAGR and growth forecasts.
Frequently Asked Questions
Q1. How big is the India EV charging station market?
➤ The India EV charging station market was valued at USD 589.1 Million in 2025, making it one of the fastest-growing EV charging markets in the Asia-Pacific region by infrastructure deployment velocity.
Q2. What is the projected growth rate of the India EV charging station market?
➤ The market is expected to grow at a CAGR of 6.82% from 2026 to 2034, reaching USD 1,078.8 Million by 2034.
Q3. Which application segment holds the largest market share?
➤ Commercial applications dominate with a 79.2% share in 2025, driven by fleet electrification commitments from logistics operators, ride-hailing platforms, and e-commerce delivery companies.
Q4. What are the key factors driving market growth?
➤ Government policy support (FAME II, PM e-DRIVE), rising EV sales across all vehicle categories, fleet electrification by logistics and ride-hailing platforms, declining Level 2 EVSE costs, and fuel retail network integration are the primary growth catalysts.
Q5. What are the major challenges facing the market?
➤ Low charger utilization rates impacting project economics, grid infrastructure limitations in non-metro regions, high capex for fast charging deployment, and demand–supply mismatch in Tier 2/3 cities represent the primary structural challenges.
Conclusion
The India EV charging station market's path to USD 1,078.8 Million by 2034 is structurally anchored, not speculative. The FAME II and PM e-DRIVE policy frameworks are in place. The fleet electrification mandate is institutional. The technology layer — from OCPP 2.0.1 to AI-powered load management — is maturing rapidly. The EV adoption engine shows no sign of slowing. The CPOs and technology platforms that invest most decisively in highway corridor expansion, smart charging software, and fleet depot solutions during the 2026–2029 window will define India's EV charging competitive hierarchy for the decade that follows. The market is open, the policy environment is the most favorable it has ever been, and the EV consumer base is increasingly mainstream.
Verified Data Source: IMARC Group