Germany Cryptocurrency Market Size, Share, Trends and Outlook 2034
The Germany cryptocurrency market size reached USD 1,22,794.0 Million in 2025. The market is projected to reach USD 2,72,745.2 Million by 2034, exhibiting a growth rate (CAGR) of 8.99% during 2026-2034.
 Yadwender Kumar
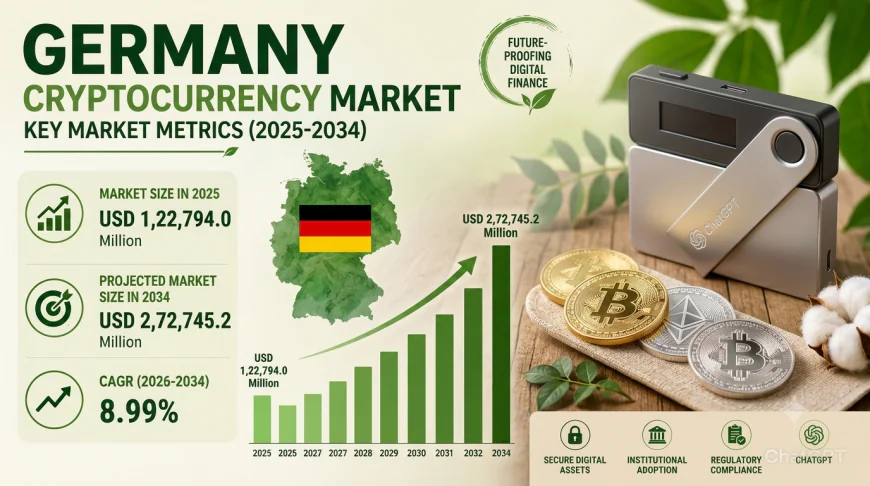
The Germany cryptocurrency market is witnessing strong growth driven by a favorable regulatory environment, increasing institutional investment, a tech-savvy population eager to explore digital assets, and the country’s position as Europe’s leading cryptocurrency hub. The market size reached USD 1,22,794.0 Million in 2025 and is projected to reach USD 2,72,745.2 Million by 2034, exhibiting a compound annual growth rate (CAGR) of 8.99% during 2026-2034. Germany holds the largest share with 23% of the total Europe cryptocurrency market in 2025, benefiting from progressive regulatory frameworks, strong institutional adoption, and a sophisticated financial services infrastructure supporting digital asset innovation. This market is strategically important to Germany’s economy as it directly supports the nation’s financial services sector, fintech innovation, and positions the country at the forefront of tokenized finance innovation in Europe.
The Germany cryptocurrency market is poised for sustained expansion, driven by progressive regulatory frameworks and strong institutional adoption. With a projected CAGR of 8.99% through 2034, the market presents significant opportunities for established financial institutions and new entrants focused on compliant custody, trading infrastructure, and innovative blockchain solutions.
GERMANY CRYPTOCURRENCY MARKET SUMMARY
- The Germany cryptocurrency market size reached USD 1,22,794.0 Million in 2025.
- The market is projected to reach USD 2,72,745.2 Million by 2034, exhibiting a CAGR of 8.99% during 2026-2034.
- Germany holds the largest share with 23% of the total Europe cryptocurrency market in 2025.
- The market is driven by a favorable regulatory environment, increasing institutional investment, a tech-savvy population, and growing integration of digital assets into mainstream financial services.
- Key segments include type (Bitcoin, Ethereum, Bitcoin Cash, Ripple, Litecoin, Dashcoin, and others), component (hardware and software), process (mining and transaction), and application (trading, remittance, payment, and others).
- Regional coverage includes Western Germany, Southern Germany, Eastern Germany, and Northern Germany.
- Germany’s favorable tax treatment of cryptocurrency holdings, including exemptions for long-term investments, and clear licensing requirements under the German Banking Act create an attractive environment for digital asset businesses seeking regulatory certainty.
PORTER’S FIVE FORCES ANALYSIS – GERMANY CRYPTOCURRENCY MARKET
The competitive dynamics of the Germany cryptocurrency market can be analyzed using Porter’s Five Forces framework.
Porter’s Five Forces Analysis – Germany Cryptocurrency Market
- Competitive Rivalry: High, with intense competition between global exchanges (Binance, Coinbase, Kraken) and emerging domestic platforms. Rivalry is driven by regulatory compliance capabilities, security features, user experience, and product innovation. Business implication: Exchanges must differentiate through regulatory compliance, superior security, and integrated traditional financial services to attract and retain users.
- Supplier Power (Technology Providers): Moderate. Providers of blockchain infrastructure, custody solutions, and mining hardware have moderate negotiating power due to the specialized nature of their services. However, the open-source nature of many blockchain protocols limits excessive supplier power. Business implication: Market participants should diversify technology partnerships and invest in proprietary capabilities where strategic.
- Buyer Power (Retail and Institutional Investors): Increasing. Investors have growing bargaining power as they become more knowledgeable about digital assets and have access to a wide variety of platforms and products. Institutional investors, including pension funds and asset managers, are increasingly demanding regulated services with comprehensive reporting capabilities. Business implication: Service providers must focus on compliance, transparency, and user experience to meet evolving investor expectations.
- Threat of Substitutes: Moderate. Traditional financial instruments (stocks, bonds, ETFs), alternative digital assets, and decentralized finance (DeFi) protocols pose substitution threats. The growing acceptance of tokenized traditional assets also creates alternative investment pathways. Business implication: Cryptocurrency platforms must innovate with new products and integrate traditional financial services to remain competitive.
- Threat of New Entrants: Moderate. High barriers exist for establishing a regulated exchange or custody service (licensing, capital requirements, compliance infrastructure), but lower barriers exist for fintech applications and DeFi platforms. Germany’s clear regulatory framework encourages new entrants while maintaining market integrity. Business implication: Established players should build defensible positions through regulatory expertise, security infrastructure, and strong institutional relationships.
Competitive Rivalry – Moderate to High (Healthy)
- Multi-tier competition spans global exchanges (Binance, Coinbase, Kraken), traditional financial institutions entering the space (Deutsche Bank, Sparkassen through DekaBank), and emerging fintech platforms — driving differentiation through regulatory compliance, security features, and integrated traditional financial services rather than destructive price competition.
- Germany’s regulatory leadership includes granting the first DLT Pilot Regime license for blockchain-based securities trading and settlement, positioning Germany at the forefront of tokenized finance innovation.
- In July 2025, Germany’s Sparkassen group lifted its three-year ban on cryptocurrency, revealing intentions to provide Bitcoin and crypto trading via DekaBank by summer 2026. The service would be incorporated directly into the Sparkasse app within a regulated framework, marking a significant strategic shift for Germany’s largest savings bank network with around 50 Million clients.
Request for Sample Report:
https://www.imarcgroup.com/germany-cryptocurrency-market/requestsample
MARKET GROWTH DRIVERS:
Several key factors are propelling the expansion of the Germany cryptocurrency market. The progressive regulatory environment serves as a powerful foundation for market development, with Germany’s clear licensing requirements under the German Banking Act and favorable tax treatment of cryptocurrency holdings creating an attractive environment for digital asset businesses. The rising retail participation is a significant demand driver, as barriers to entry rapidly diminish with user-friendly crypto trading apps and wallets. Younger generations, particularly millennials and Gen Z, are viewing cryptocurrencies as an alternative investment and a hedge against inflation and low interest rates in traditional savings products.
Thriving Fintech Sector
The expansion of the fintech industry is impelling the Germany cryptocurrency market growth. German fintech startups are developing crypto-friendly platforms, such as digital wallets, trading apps, and decentralized finance (DeFi) services, making it easier for users and businesses to engage with cryptocurrencies. These innovations reduce friction in buying, selling, and storing digital assets, helping to normalize crypto utilization. Moreover, collaborations between fintech firms and traditional financial institutions are leading to hybrid services like crypto-backed loans and investment products, which appeal to mainstream investors. According to industry reports, at the beginning of 2024, Germany had 77.70 Million internet users, with internet penetration at 93.3%, providing a strong digital foundation for fintech and crypto adoption.
Institutional Adoption and Integration
Germany’s robust legal framework provides comprehensive guidelines for cryptocurrency custody, trading, and issuance activities, attracting both domestic enterprises and international firms establishing European operations within its jurisdiction. The German cryptocurrency ecosystem demonstrates remarkable maturity, with major banks integrating digital asset services and fintech companies pioneering innovative blockchain solutions. Institutional investors, including pension funds, insurance companies, and asset managers, increasingly allocate to cryptocurrencies through regulated German service providers offering compliant custody, trading infrastructure, and comprehensive reporting capabilities meeting fiduciary standards.
GERMANY CRYPTOCURRENCY MARKET SEGMENTATION
Segmentation analysis provides a detailed view of the Germany cryptocurrency market by category:
- Type Insights: Bitcoin, Ethereum, Bitcoin Cash, Ripple, Litecoin, Dashcoin, Others.
- Component Insights: Hardware, Software.
- Process Insights: Mining, Transaction.
- Application Insights: Trading, Remittance, Payment, Others.
- Regional Insights: Western Germany, Southern Germany, Eastern Germany, Northern Germany.
COMPETITIVE LANDSCAPE
The Germany cryptocurrency market features a dynamic competitive landscape, with multi-tier competition spanning global exchanges, traditional financial institutions, and emerging fintech platforms. Key companies operating in the market include:
- Coinbase
- Binance
- Kraken
- Deutsche Bank
- DekaBank (Sparkassen group)
- Bitfinex
- Bitstamp
Strategic developments are shaping the competitive arena, notably Sparkassen’s July 2025 decision to lift its three-year ban on cryptocurrency and provide Bitcoin and crypto trading via DekaBank by summer 2026, serving approximately 50 Million clients through the Sparkasse app within a regulated framework.
REGIONAL ANALYSIS:
Regional dynamics within the Germany cryptocurrency market are shaped by varying levels of fintech concentration and institutional adoption. Western Germany, particularly financial centers like Frankfurt, emerges as a critical hub for cryptocurrency trading, custody, and institutional services. Southern Germany benefits from a strong technology and startup ecosystem supporting blockchain innovation. Eastern Germany and Northern Germany, though smaller in market share, are seeing growth from fintech development and increasing retail participation.
- Western Germany (Frankfurt): Dominant region for institutional cryptocurrency services, home to major banks and financial infrastructure supporting digital asset innovation.
- Southern Germany (Munich, Bavaria): Strong technology and startup ecosystem driving fintech and blockchain innovation.
- Eastern Germany: Emerging market with growing fintech development and retail adoption.
- Northern Germany: Smaller but growing market, driven by technology adoption and financial services integration.
RECENT INDUSTRY DEVELOPMENTS
July 2025: Germany’s Sparkassen group lifted its three-year ban on cryptocurrency, revealing intentions to provide Bitcoin and crypto trading via DekaBank by summer 2026. The service would be incorporated directly into the Sparkasse app within a regulated framework, marking a significant strategic shift for Germany’s largest savings bank network with around 50 Million clients.
July 2025: Deutsche Bank announced its entry into cryptocurrency services, further legitimizing digital assets within Germany’s traditional financial sector.
2025: Germany granted the first DLT Pilot Regime license for blockchain-based securities trading and settlement, positioning the country at the forefront of tokenized finance innovation in Europe.
November 2025: According to GTAI data, the value of digital assets in Germany reached 1.7 billion euros as of 2025, with venture capital financing at 327 million euros as of 2023. Additionally, 27% of domestic organizations were using blockchain technology as of 2024, representing a 6% growth compared to 2023.
Note: If you need any specific information that is not covered currently within the scope of the report, we will provide the same as a part of customization.
Request Customization: https://www.imarcgroup.com/request?type=report&id=40285&flag=E
Write this before about us -
- Report Format, Delivery, and Customization Details
- Report Format Mode: PPT, PDF, and Excel
- Report Delivery Mode: Online Delivery, Physical Delivery
- Report Delivery Time: Report Delivered Over Email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
- Report Confirmation Mode: Yes via Email
- Report Customization Mode: Yes via Email / Call
- Report Table of Content: Yes
- Report List of Figures: Yes
- Report Methodology Mode: Yes
- Request For Sample Report: Yes